



Is GBP/USD set for a sympathy bounce? European open – 25th July 2023
With GBP/USD having fallen for seven consecutive days and showing signs of slowing momentum above key support levels, we could be close to (if not already at) the time for a sympathy bounce for bulls over the near-term.
Share this:
Asian Indices:
- Australia's ASX 200 index rose by 37.6 points (0.51%) and currently trades at 7,344.00
- Japan's Nikkei 225 index has fallen by -139.29 points (-0.43%) and currently trades at 32,561.65
- Hong Kong's Hang Seng index has risen by 590.51 points (3.16%) and currently trades at 19,258.66
- China's A50 Index has risen by 396.85 points (3.18%) and currently trades at 12,894.72
UK and Europe:
- UK's FTSE 100 futures are currently down -12 points (-0.16%), the cash market is currently estimated to open at 7,666.59
- Euro STOXX 50 futures are currently down -6 points (-0.14%), the cash market is currently estimated to open at 4,377.03
- Germany's DAX futures are currently down -30 points (-0.18%), the cash market is currently estimated to open at 16,160.95
US Futures:
- DJI futures are currently down -15 points (-0.04%)
- S&P 500 futures are currently down -1 points (-0.02%)
- Nasdaq 100 futures are currently down -1.75 points (-0.01%)
- Sentiment was positive during the Asian session on expectations that China will increase stimulus, after State agency Xinhua quoted the Politburo of saying macro adjustments will be implemented “in a precise and forceful manner" and strengthen counter-cyclical adjustments via prudent monetary policy and pro-active fiscal stimulus
- The China A50 broke to a 5-week high in line with our bullish bias and shows the potential to reach 13,500 (as long as it can hold above today’s low)
- The PBOC showed that they’re serious about pushing back against currency depreciation by raising the yuan fix by 500bp, sending USD/CNY sharply down to a 6-day low
- Whilst Europe’s weak PMIs point to a much faster slowdown, they also point to lower price pressure which therefor removes some heat for the ECB to hike in September. And that helps explain how the DAX took it all within its stride to print another ‘sideways’ day.
- The German Ifo business report is the main calendar event today at 7:00 BST, but given it has turned lower over the past few months and we had weak PMIs overnight, it is debatable as to how much of a surprise a weak print would be. That said, it could further scale back bets of a September ECB hike or even raise some hopes of a pauser this week, and weigh further on EUR/USD.
- AUD/USD and NZD/USD were the strongest majors during the Asian session as they tracked Asian indices higher
- EUR/USD closed beneath the May high of 1.1095, and that level may provide a level for bears to fade into if its Asian-retracement higher continues to drift that way without conviction
- EUR/GBP fell to a 3-day low after printing a couple of hammers near 7-week highs, although support has been found around a 38.2% Fibonacci level near 0.8620. We’re looing for evidence of a swing low after the currency pullback and for momentum to realign with the bullish momentum of the daily timeframe.
- USD/CHF looks like it wants to reach for the 2021 low at 0.8758, and yesterday’s upside break of its sideways rage on the 1-hour chart could keep it on bullish watchlists for intraday traders
- 1-day implied volatility levels sits ~65% of the 20-day average, which means intraday traders may want to retain smaller targets unless we’re dealt with a fresh volatility-inducing catalyst
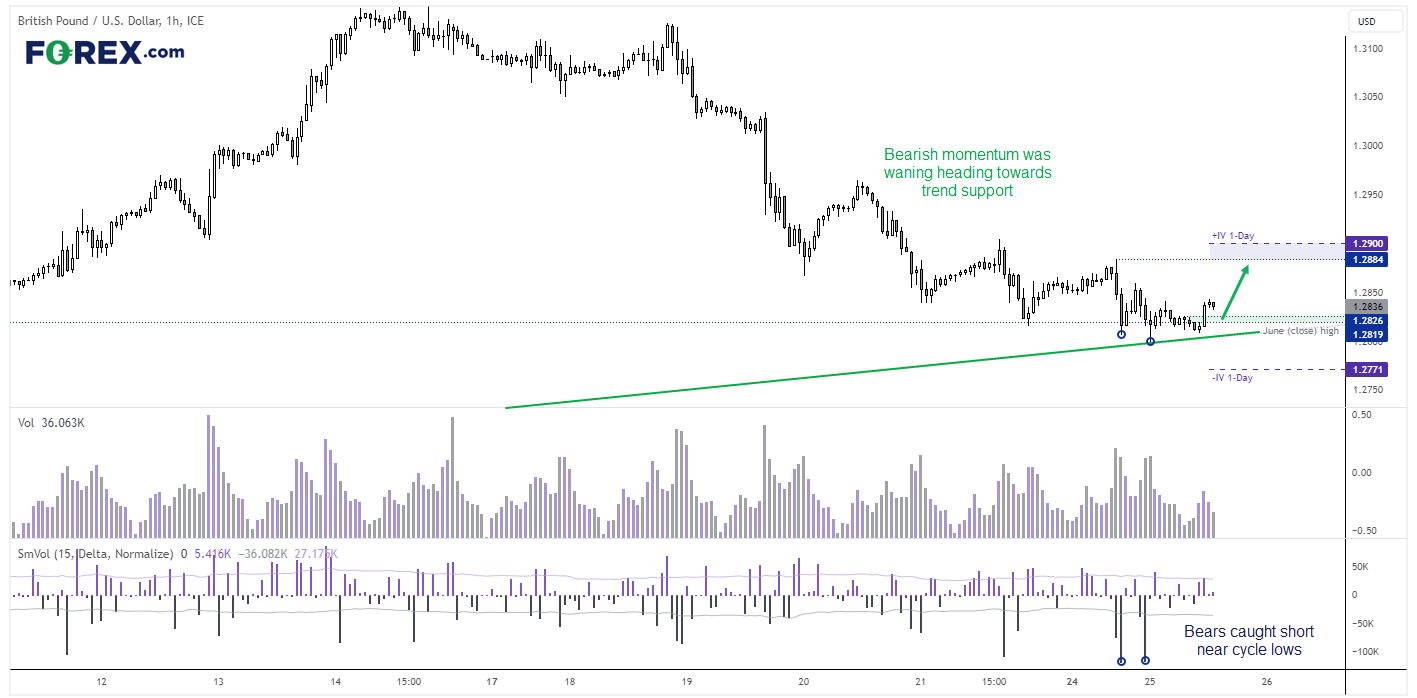
GBP/USD 1-hour chart:
GBP/USD has fallen for seven consecutive days, which is its most bearish sequence since March 2020. Yet with bearish momentum waning and a looming FOMC meeting, its downside could be limited over the near-term and could face risks of a technical bounce.
The 1-hour chart shows prices are respecting trend support and holding above the June (close) high. Two of the more prominent cycle lows leading into recent cycle lows were accompanied with very negative delta volumes, which suggests bears may have been caught short at these lows and may look to cover to further support prices. We also saw volumes rise alongside prices in yesterday’s NY session, so the near-term strategy is to seek dips for a near-term bullish play.

View the full economic calendar
View the full economic calendar
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.

EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.