



Lloyds Jumps 2percent Despite 26percent Fall In Profits
Lloyds, the last of the big 4 banks to report full year earnings. To say the bar was set low would be an understatement.
Share this:

Lloyds, the last of the big 4 banks to report full year earnings. To say the bar was set low would be an understatement.
Results
- Annual profit -26% to £4.4 billion vs £3 billion expected
- Underlying profits -7% to £7.5 billion
- Net income -4% to£17.1 billion
Lloyds reported a 26% decline in annual profits owing to bad loans and high compensation payout from PPI. PPI redress totaled £2.5 billion in 2019 however this is expected to be the end of the payouts after the PPI deadline passed at the end of summer 2019.
Impairments on bad loans spiked by 38% to £1.3 billion vs. £937 million, the previous year owing to a reduction in NIM and in part to the failure of two large companies which knocked the commercial division. Whilst the bank couldn’t confirm the name of the companies Lloyds was known to have been one of the main lenders to collapsed holiday firm Thomas Cook.
Tough 2019, improving conditions 2020?
Last year the bank struggled with slowing global growth but perhaps more importantly domestic political uncertainty, as Brexit dragged on business and consumer confidence. This year the macro climate in the UK appears to be setting off on the right foot but the problems have by no means evaporated.
GDP at the end of 2019 beat expectations, whilst in January the labour market remained strong, inflation increased, and retail sales jumped indicating a bounce in the UK economy. Given the strong correlation between Lloyds and the UK macro climate, this is encouraging. However, there are still plenty of potential pitfalls ahead as the UK negotiates a trade deal with the EU and the macro climate in the UK is expected to remain challenging. Despite this, the outlook from Lloyds was relatively stable.
March’s Budget To Lift Lloyds Further?
Whilst low interest rates squeezed margins at the lender last year, an expansionary fiscal policy could underpin the share price in early 2020. Higher government spending would take the pressure off the Bank of England to cut interest rates, thus supporting the net interest margin’s at the banks. All eyes will turn towards Rishi Sunak’s Budget next month to see whether he can deliver the higher spending the markets hope for.
Chart thoughts
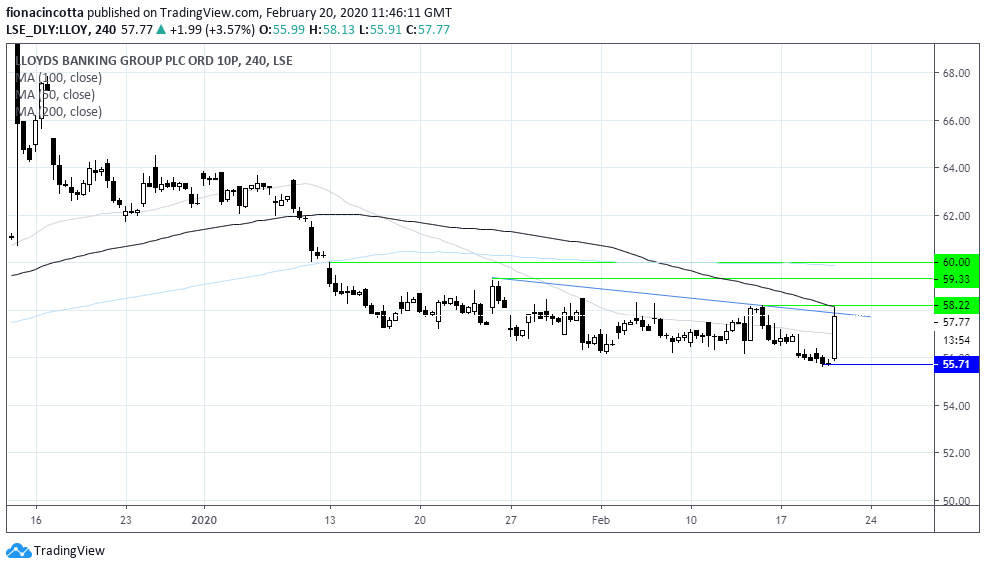
The share price has jumped over 2.5% this morning, taking Lloyds above its 50 sma on 4 hour chart. The rally has been capped by resistance around 58.1p (100 sma & 14 Feb high). A meaningful move through this strong resistance could see the doors opened to 59.3 (24th Jan high) prior to 60p (10 Jan high).
On the flip side support can be see around 55.65p (yesterday’s low).
Lloyds, the last of the big 4 banks to report full year earnings. To say the bar was set low would be an understatement.
Results
- Annual profit -26% to £4.4 billion vs £3 billion expected
- Underlying profits -7% to £7.5 billion
- Net income -4% to£17.1 billion
Lloyds reported a 26% decline in annual profits owing to bad loans and high compensation payout from PPI. PPI redress totaled £2.5 billion in 2019 however this is expected to be the end of the payouts after the PPI deadline passed at the end of summer 2019.
Impairments on bad loans spiked by 38% to £1.3 billion vs. £937 million, the previous year owing to a reduction in NIM and in part to the failure of two large companies which knocked the commercial division. Whilst the bank couldn’t confirm the name of the companies Lloyds was known to have been one of the main lenders to collapsed holiday firm Thomas Cook.
Tough 2019, improving conditions 2020?
Last year the bank struggled with slowing global growth but perhaps more importantly domestic political uncertainty, as Brexit dragged on business and consumer confidence. This year the macro climate in the UK appears to be setting off on the right foot but the problems have by no means evaporated.
GDP at the end of 2019 beat expectations, whilst in January the labour market remained strong, inflation increased, and retail sales jumped indicating a bounce in the UK economy. Given the strong correlation between Lloyds and the UK macro climate, this is encouraging. However, there are still plenty of potential pitfalls ahead as the UK negotiates a trade deal with the EU and the macro climate in the UK is expected to remain challenging. Despite this, the outlook from Lloyds was relatively stable.
March’s Budget To Lift Lloyds Further?
Whilst low interest rates squeezed margins at the lender last year, an expansionary fiscal policy could underpin the share price in early 2020. Higher government spending would take the pressure off the Bank of England to cut interest rates, thus supporting the net interest margin’s at the banks. All eyes will turn towards Rishi Sunak’s Budget next month to see whether he can deliver the higher spending the markets hope for.
Chart thoughts
The share price has jumped over 2.5% this morning, taking Lloyds above its 50 sma on 4 hour chart. The rally has been capped by resistance around 58.1p (100 sma & 14 Feb high). A meaningful move through this strog resistance could see the doors opened to 59.3 (24th Jan high) prior to 60p (10 Jan high).
On the flip side support can be see around 55.65p (yesterday’s low).
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Klarna IPO 2025: Key Facts, Valuation & BNPL Outlook
Klarna’s long-awaited IPO lands with a ~$14B valuation target—well below its 2021 peak but far above its 2022 trough. With 111M users, ~790k merchants, and five straight profitable quarters, Klarna hopes to prove it’s more than just a BNPL pioneer. Our cheat sheet breaks down the company’s history, valuation, competitors, revenues, and what to watch as KLAR lists on the NYSE in the busiest IPO week since 2021.
JPMorgan Q4 Earnings: Growth, Risks, and Outlook
JPMorgan Chase releases Q4 earnings on Jan 15, with EPS expected at $4.03 and revenue at $41.58B. Analysts will watch net interest income, cost control, and credit provisions as rising rates boost profits but risks like delinquencies and geopolitical tensions persist. The bank has outpaced the S&P 500 in 2025 YTD, reflecting resilience. Will it maintain its streak of beating estimates? Learn about its growth drivers, risks, and market impact ahead of this pivotal report.
Earnings preview: Bank of America, Goldman Sachs & Citigroup
US financial services and banks continue to release earnings. All of them reported higher earnings numbers when compared to last year. We continue with 4 more.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.