



Market Brief Traders Calm Their Middle East Fears
See a summary of the top market themes and trends from today's US trading session!
Share this:

View our guide on how to interpret the FX Dashboard.
- After opening lower on fears of continued escalation in the tensions between the US and Iran/Iraq, markets calmed down throughout today’s US session with traders reassured by soothing comments from France and China. That said, most analysts still expect retaliation and another proverbial “shoe to drop” in one form or another.
- A separate situation to watch will be developments around the planned signing of a “Phase One” trade deal between the US and China next week - China’s Global Times signaled today that “a speedy signing is not of the essence,” raising fears of another potential delay.
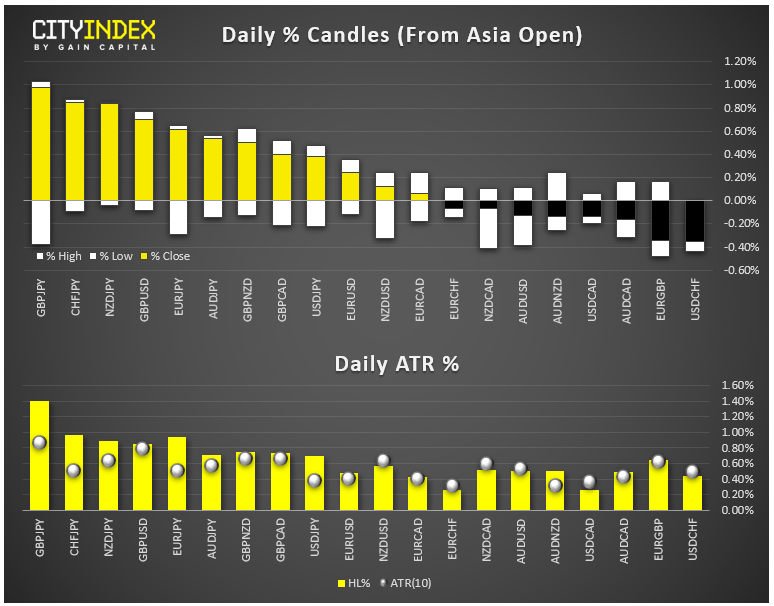
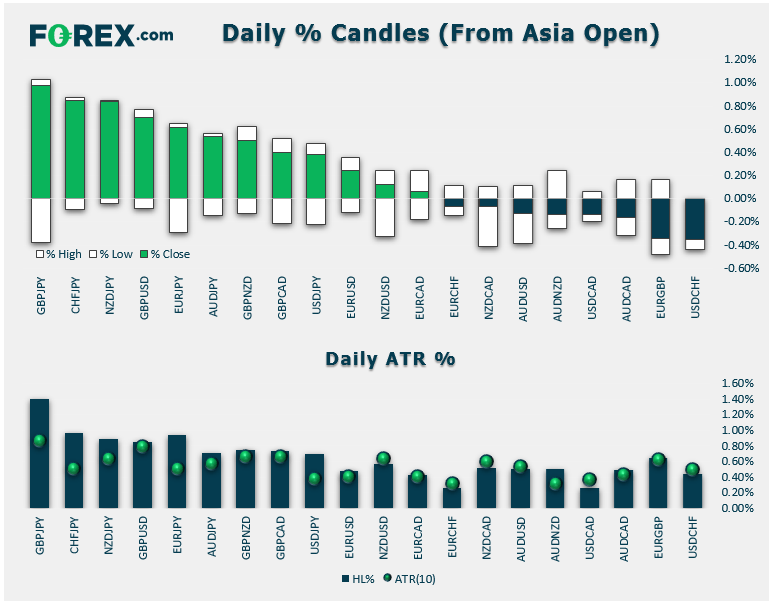
- FX: The British pound was the day’s strongest currency, erasing Friday’s losses entirely. The Japanese yen and Australian dollar were the weakest, though AUD/USD is showing several bullish technical signs.
- Commodities: Oil finished the day essentially flat after a big rally in the Asian session; gold tacked on 1% and hit an intraday high near $1600 on the tensions in the Middle East
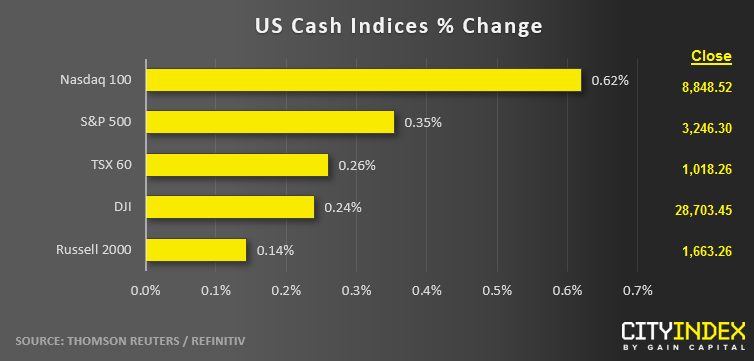
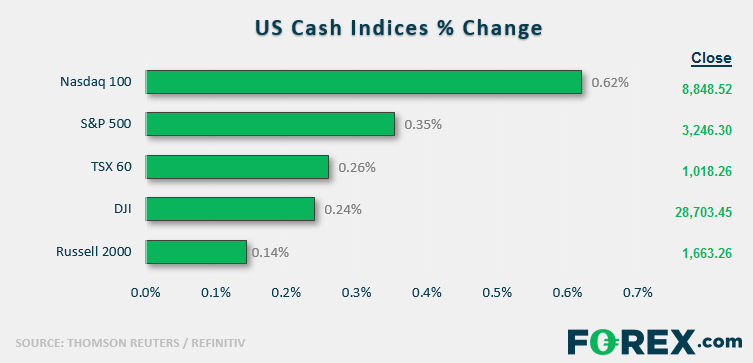
- US indices fought back from early losses to close modestly in positive territory.
- Communication Services (XLC) was the strongest major sector on the day. Industrials (XLI), Materials (XLB), and Financials (XLF) brought up the rear.
- Stocks on the move:
- FAANG stocks led the way higher for broader markets (FB +2%, AAPL +1%, AMZN +1%, NFLX +3%, GOOG +2%).
- Goldman Sachs (GS, +1%) and Morgan Stanley (MS, -0%) shrugged off news that their financial reporting practices were being investigated by the Bank of England.
- Retailer Bed Bath & Beyond (BBBY) gained 3% on a WSJ report that the company was selling roughly half its real estate to a PE firm.
*There are no market-moving macroeconomic releases scheduled for Tuesday’s Asian session*
View our guide on how to interpret the FX Dashboard.
- After opening lower on fears of continued escalation in the tensions between the US and Iran/Iraq, markets calmed down throughout today’s US session with traders reassured by soothing comments from France and China. That said, most analysts still expect retaliation and another proverbial “shoe to drop” in one form or another.
- A separate situation to watch will be developments around the planned signing of a “Phase One” trade deal between the US and China next week - China’s Global Times signaled today that “a speedy signing is not of the essence,” raising fears of another potential delay.
- FX: The British pound was the day’s strongest currency, erasing Friday’s losses entirely. The Japanese yen and Australian dollar were the weakest, though AUD/USD is showing several bullish technical signs.
- Commodities: Oil finished the day essentially flat after a big rally in the Asian session; gold tacked on 1% and hit an intraday high near $1600 on the tensions in the Middle East
- US indices fought back from early losses to close modestly in positive territory.
- Communication Services (XLC) was the strongest major sector on the day. Industrials (XLI), Materials (XLB), and Financials (XLF) brought up the rear.
- Stocks on the move:
- FAANG stocks led the way higher for broader markets (FB +2%, AAPL +1%, AMZN +1%, NFLX +3%, GOOG +2%).
- Goldman Sachs (GS, +1%) and Morgan Stanley (MS, -0%) shrugged off news that their financial reporting practices were being investigated by the Bank of England.
- Retailer Bed Bath & Beyond (BBBY) gained 3% on a WSJ report that the company was selling roughly half its real estate to a PE firm.
*There are no market-moving macroeconomic releases scheduled for Tuesday’s Asian session*


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.