



Global Markets Slide as AI Valuations Unwind | DAX Breaks Support, Fed Turns Cautious
US equities fell sharply as renewed concern over inflated AI valuations triggered broad risk aversion. The S&P 500 dropped below its 50-day moving average, with Nvidia and Tesla leading losses, while bond yields edged higher after hawkish Fed remarks. Washington lowered food tariffs to ease inflation, and Brazil positioned itself as a potential US rare-earth partner. The DAX broke below 23,650 support, confirming bearish momentum, while oversold signals suggest a short-term bounce is possible. Bitcoin fell below $90,000 as risk appetite faded.
Share this:

Market Overview – 18 November 2025
US Markets
- Wall Street slide: All major US indices saw their sharpest drop in weeks, with the S&P 500 falling below 6,700 and closing under its 50-day moving average (6,707).
- Breadth: Every S&P 500 sector finished lower except Communications and Utilities.
- AI valuation drag: Renewed caution over stretched AI valuations weighed on risk assets. Nvidia slipped ahead of Wednesday’s earnings; Dell and HPE fell after broker downgrades, while Alphabet gained >3 % on news of a Berkshire stake.
- Macro focus: Traders awaited Thursday’s delayed September jobs report following the end of the government shutdown.
- Asia reaction: Regional equities mirrored US weakness; Nikkei –3.2 % led losses as chipmakers sold off.
- Japan policy pressures: Yen weakness and expectations of a large fiscal package lifted long JGB yields to their highest since 1999.
- Crypto: Bitcoin dropped below USD 90 000, its lowest since April; Ethereum < USD 3 000.
Trade and Tariffs
- US tariff cuts: Washington lowered import duties on popular foods — including coffee, bananas, tomatoes, and beef — to ease voter frustration over high grocery prices.
- The average agricultural tariff fell from 13.0 % → 10.3 %, while the overall import rate eased slightly from 14.6 % → 14.4 %.
- Exporters from Australia, New Zealand, Guatemala, Costa Rica, and Ecuador benefit most.
- US–Switzerland deal: Tariffs on Swiss goods cut from 39 % → 15 %.
- Switzerland pledged USD 200 bn US investment by 2028, largely from pharmaceutical firms.
- Swiss Q3 GDP fell –0.5 % q/q (vs –0.1 % expected); KOF sees recovery from 2026, with tariff cuts adding 0.3–0.5 ppt p.a. to growth.
- The CHF strengthened to 0.918 / EUR, its firmest since 2015; markets doubt a return to negative SNB rates.
US Commercial Real Estate
- Rebound: Q3 2025 transaction volumes +17 % y/y, led by multifamily, logistics, and data-centre assets.
- Catalyst: September’s 25 bp Fed rate cut and renewed investor confidence drove demand for long-lived, income-generating assets.
- Focus areas: Durable, inflation-resistant sectors — e.g., urban logistics and housing aligned with demographic shifts.
Rare Earths / Brazil–US Cooperation
- Brazil proposal: Seeking partnership with Washington to develop rare-earth production and lessen China’s dominance.
- Reserves: 21 mt (world’s #2 after China’s 44 mt) but output only 20 t / yr vs China 270 t.
- Requires heavy investment to scale mining capacity; viewed as a strategic counterweight in the US–China supply-chain rivalry.
- Brazil mining sector P/E 7.1 vs China 13.0, signalling potential valuation upside.
Federal Reserve Commentary
- Trump: Reiterated his goal for 1 % inflation (Bloomberg).
- Governor Waller:
- Supports a 25 bp cut in December, calling it “labour-market insurance.”
- Warned that job-growth slowdown and rising layoffs justify a cautious easing path.
- Said higher market rates suggest scarce reserves; balance sheet may need to expand again within months.
- Believes the Fed should prioritise employment risks over residual inflation overshoot.
- Neutral rate uncertain; small cuts preferred to avoid undermining confidence.
- Argued that firms are funding AI capex by slowing hiring, while households trim spending—tightening labour conditions further.
DAX Technical Analysis 4 H
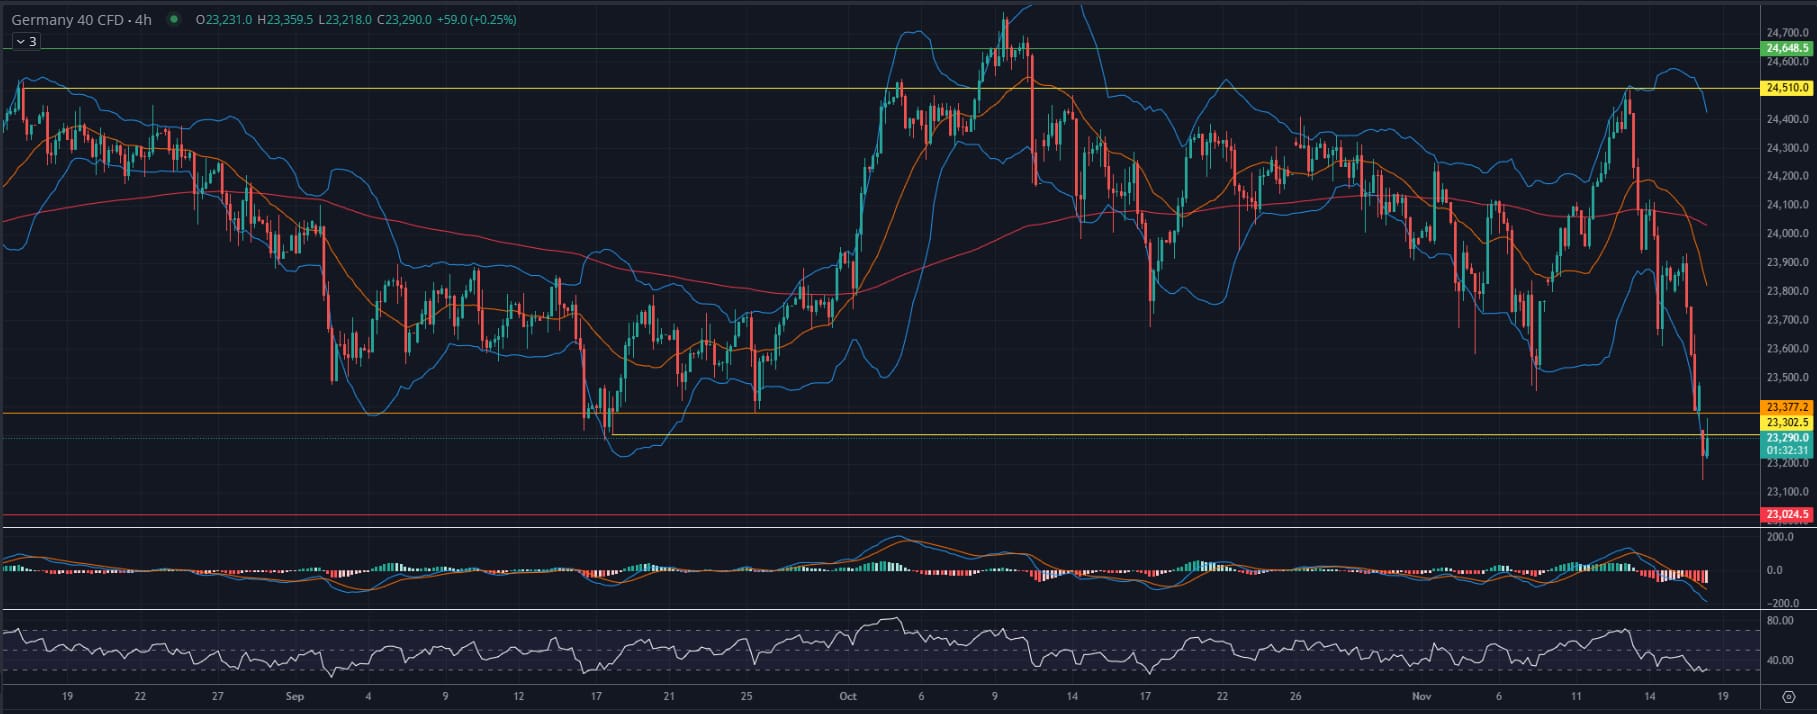
The Germany 40 CFD (4H) has broken decisively below 23,650, extending losses toward the 23,300 support zone — the lower boundary of its multi-month range. The RSI (34) is oversold, hinting at near-term exhaustion, while the MACD remains deeply negative, confirming strong bearish momentum. Price is riding the lower Bollinger Band, suggesting persistent selling pressure but also stretched conditions.
Immediate support is at 23,300, followed by 23,025; these levels mark the last major demand zones before broader downside risk opens. Resistance now sits at 23,650–23,800, where the 20 EMA and 50 EMA converge. A rebound from current levels is possible, but recovery attempts face heavy resistance unless the index reclaims 24,000. Tone: bearish trend continuation, but oversold short-term with potential for a technical bounce.
Overall:
Global markets opened the week risk-off amid stretched AI valuations, tech downgrades, and rising bond yields. The US lowered select import tariffs to ease inflation pressures, while Brazil positioned itself as a new rare-earth partner for Washington. Fed officials maintained a dovish bias, but cautious rhetoric and weak crypto sentiment reinforced defensive positioning across risk assets.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.


Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.


Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.