
Markets Brace for Nvidia Earnings | DAX Near Oversold Zone, Trump buys Bonds
Global markets traded cautiously ahead of Nvidia’s earnings, expected to trigger a record USD 320 bn market-cap swing. US stocks fell, led by tech weakness and fading rate-cut hopes. The DAX extended its slide toward 23,000, entering oversold territory with momentum still weak. Fed officials flagged liquidity stress and hinted at early 2026 balance-sheet expansion. Washington’s tariff cuts and US–Brazil rare-earth cooperation added geopolitical texture, while Apple, Google, and AMD led corporate highlights. Focus shifts to Nvidia’s results and the December FOMC outlook.
Share this:
Market Summary – 19 November 2025
Nvidia Earnings Preview
- Record stakes: Options imply a ~7 % post-earnings move in Nvidia, equivalent to a USD 320 bn market-cap swing—potentially the largest single-day change ever for any company.
- Focus: Investors seek clarity on whether the AI boom is accelerating or cooling. Results are due after the US close Wednesday.
- Context: At ~USD 4.6 trn valuation, Nvidia’s report is viewed as the key sentiment driver for the AI sector this quarter.
Corporate & Sector Highlights
- Apple: Captured 25 % of China’s smartphone market in October, with iPhone 17 sales up 37 % YoY. Overall Chinese smartphone sales rose 8 % YoY.
- Google: Shares hit new highs after Berkshire Hathaway revealed a USD 4.9 bn stake, reinforcing confidence following strong earnings and resilience during the AI pullback.
- US Small Business Sentiment (BoA):
- 74 % of small/mid-sized firms expect higher revenue next year; ~60 % plan expansion.
- Confidence hinges on tariff stability (53 %), cooling inflation (52 %), and lower rates (52 %).
- Profitability for small firms remains resilient in 2025.
Germany: Q3 Earnings Season
- DAX companies: Aggregate profit +2 % YoY, driven by financials, healthcare, and energy tech.
- Auto sector: Earnings –60 % YoY, offsetting broader strength; without autos, total growth would have been +15 ppt higher.
- Outlook: Analysts see –9 % Q4 profit decline, but potential rebound +14 % in 2026 as exports and sentiment stabilize.
Germany 40 Technical Analysis
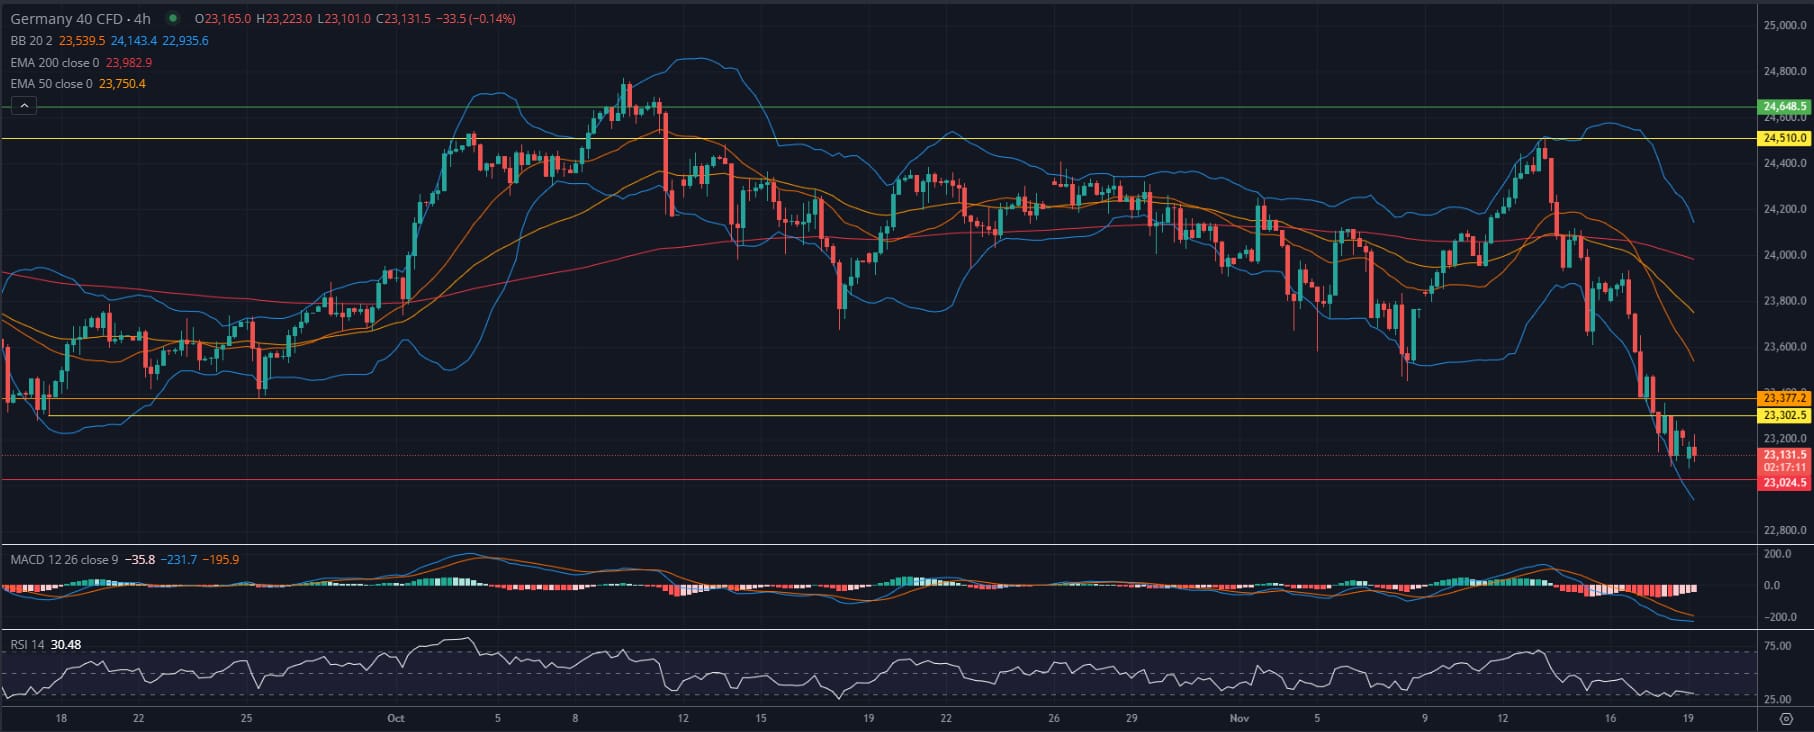
The Germany 40 CFD (4H) remains in a downtrend, extending its decline after breaking below key support at 23,300. Price is now testing the 23,100–23,000 zone, aligning with the lower Bollinger Band and near the March swing low, a critical support area. The RSI (30) is deeply oversold, indicating potential for a technical rebound, though momentum remains weak. The MACD is entrenched in negative territory, confirming persistent downside pressure.
Immediate resistance sits at 23,300–23,380, with stronger supply expected near 23,750 (50 EMA). A recovery above those levels would signal stabilization, while a breakdown below 23,000 risks further downside toward 22,800–22,600. Tone: bearish trend intact, but nearing oversold rebound territory.
Federal Reserve – Rates & Liquidity
- Policy tension: Debate over a possible December rate cut continues as liquidity pressures rise.
- Repo strains: Overnight repo rates exceeding the Fed’s Interest on Reserve Balances (IORB) indicate tight bank reserves.
- Likely response: Market expects the Fed to expand its balance sheet from Jan 2026, adding USD 20 bn/month in T-bills and USD 15 bn/month in MBS reinvestments to prevent year-end repo stress.
- Short-term relief: Treasury’s general account drawdown (~USD 100 bn) and Standing Repo Facility (SRF) usage should temporarily ease pressure.
- Key focus for December FOMC: not only rates, but also liquidity-management guidance.
US Tariffs & Trade
- Food imports: Tariffs cut on coffee, bananas, tomatoes, beef, reducing the average agricultural duty 13.0 % → 10.3 %.
- Swiss goods: Tariffs reduced 39 % → 15 %; Switzerland pledges USD 200 bn US investment (mainly pharma) by 2028.
- Growth impact: Lower tariffs could lift Swiss GDP +0.3–0.5 ppt annually from 2026; CHF strength (0.918/EUR) remains a drag.
Rare Earths & Brazil
- Brazil–US partnership talks: Brazil, holder of the world’s second-largest rare-earth reserves (21 mt), aims to boost output from 20 t to rival China’s 270 t.
- Sector outlook: Brazilian mining P/E 7.1 vs China 13.0—seen as undervalued; new cooperation could diversify US supply chains away from China.
US Real Estate
- Commercial rebound: Q3 2025 transactions +17 % YoY, driven by multifamily, logistics, and data-centre assets.
- Catalyst: September’s 25 bp Fed rate cut improved sentiment; investors favour income-producing, inflation-resilient assets.
Trump’s Portfolio Disclosure
- Total new investments: ≥ USD 82 mn (Aug–Oct), spanning corporate and municipal bonds.
- 175 transactions filed under federal ethics rules.
- Corporate bonds purchased: Broadcom, Qualcomm, Meta, Intel, Home Depot, CVS, Goldman Sachs, Morgan Stanley, JPMorgan.
- Strategic link: Intel bond purchase followed government stake acquisition under Trump’s direction, prompting scrutiny over overlap.
- Theme: Positions align with domestic manufacturing, tech independence, and infrastructure priorities.
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Forecast: AUD/USD Support Reversal Sparks Monthly Range Breakout 10 23 2026
A sharp reversal off key support has fueled the AUD/USD recovery, with resistance now in focus ahead of next week’s Fed decision and Australian CPI.
Crude Oil Forecast: Weekend Iran Strike Fears Lift Oil Toward War Highs
Brent crude oil is accelerating above $110 as traders price in the risk of a US-Israeli strike on Iran over the weekend. How much more of a geopolitical premium can oil build in before the close?
Nasdaq 100 Forecast: NDX Falls as the tech rout continues and oil prices soar
U.S. stocks are pointing to a modestly lower open after a sharp AI sell-off yesterday, as telecom stocks slide. Brent rises towards $115 adding to inflation pressures ahead of the FOMC rate decision.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.