

S&P 500 forecast: AI linked stocks remain under pressure
And just like that, it is Friday again and the end of a volatile week. Today offers little on the macro calendar to change the prevailing narrative, leaving markets largely at the mercy of risk appetite, oil prices and the growing unease around the AI trade.
Share this:
And just like that, it is Friday again and the end of a volatile week. Today offers little on the macro calendar to change the prevailing narrative, leaving markets largely at the mercy of risk appetite, oil prices and the growing unease around the AI trade. In the week ahead, we have plenty of central bank meetings, but we will tackle those next week. This morning finds European equities lower, led by France’s benchmark index, which fell more than 1%, while Germany’s DAX was down around 0.7% and US index futures were also in the red. The selling was not confined to equities. Gold briefly slipped below $4,000 overnight as the liquidation in metals continued, while crude oil pushed higher again as the situation in the Middle East remained unresolved heading into the weekend. Against this backdrop, we maintain a modestly bearish S&P 500 forecast today.
Risk remains off the table
Yesterday’s session was particularly damaging for risk appetite, and there is little so far to suggest a meaningful change in tone. Equities and metals came under intense pressure as higher oil prices further fanned inflation concerns, while renewed doubts over the economics of AI investment added to a list of growing uncertainties, which markets do not like. Bonds, meanwhile, rallied as investors sought safety, pulling yields lower. Interestingly, the traditional dollar safe-haven trade has yet to emerge. The yen and Swiss franc have instead been the main beneficiaries of the defensive rotation, suggesting investors are looking for protection without necessarily wanting to add exposure to the US currency.
Negative bonds and stocks correlation re-asserts itself
It looks like the negative correlation between bonds and equities appears to be reasserting itself. Ten-year Treasury yields fell back below 5% for the first time in a month, despite the renewed rise in oil prices. That is significant because it suggests the latest equity weakness is beginning to overwhelm concerns about a more aggressive Federal Reserve response to energy-driven inflation.
That does not necessarily mean the dollar is about to embark on a sustained decline. The bar for markets to completely price out the prospect of a December Fed hike remains relatively high, which should limit the scope for a deeper USD correction for now.
There is, however, a more worrying interpretation of falling yields. Rather than simply reflecting lower expectations for Fed tightening, they could be signalling that investors are becoming increasingly defensive as the AI trade loses momentum. The current cycle of enthusiasm around AI has been built on the assumption that enormous investment in chips, data centres and infrastructure will ultimately translate into equally enormous returns. But that assumption is now being tested.
Short bets grow on expensive tech stocks
According to Bloomberg, hedge funds have been building bearish equity positions at a pace not seen in years. Goldman Sachs says its prime brokerage clients have been shorting stocks at roughly five times the rate at which they have been buying them, pushing short exposure towards a five-year high while overall bullish positioning has also been reduced.
That positioning is clearly a warning sign for equities, but it also creates the conditions for a sharp squeeze if sentiment suddenly improves. Markets can become oversold quickly when positioning becomes this one-sided.
For now, though, the bigger issue is that several sources of uncertainty are reinforcing each other. Higher energy prices are reviving inflation concerns, geopolitical risks are keeping investors defensive, and questions over whether AI spending can generate sufficient returns are putting pressure on the very stocks that have driven much of the equity market’s gains.
The result is an increasingly fragile backdrop for risk assets. Until oil prices stabilise and confidence in the AI investment cycle improves, rallies in equities may continue to look more like opportunities to reduce risk than the start of a durable recovery.
S&P 500 forecast: technical analysis and levels to watch
In fact, if the S&P 500 now breaks the short-term trend line that has been in place since the summer decisively, then it could give rise to further technical selling and long-side liquidations. Yesterday, it tested the trend line and broke it momentary before bouncing off the lows. The bears are having another go at it today.
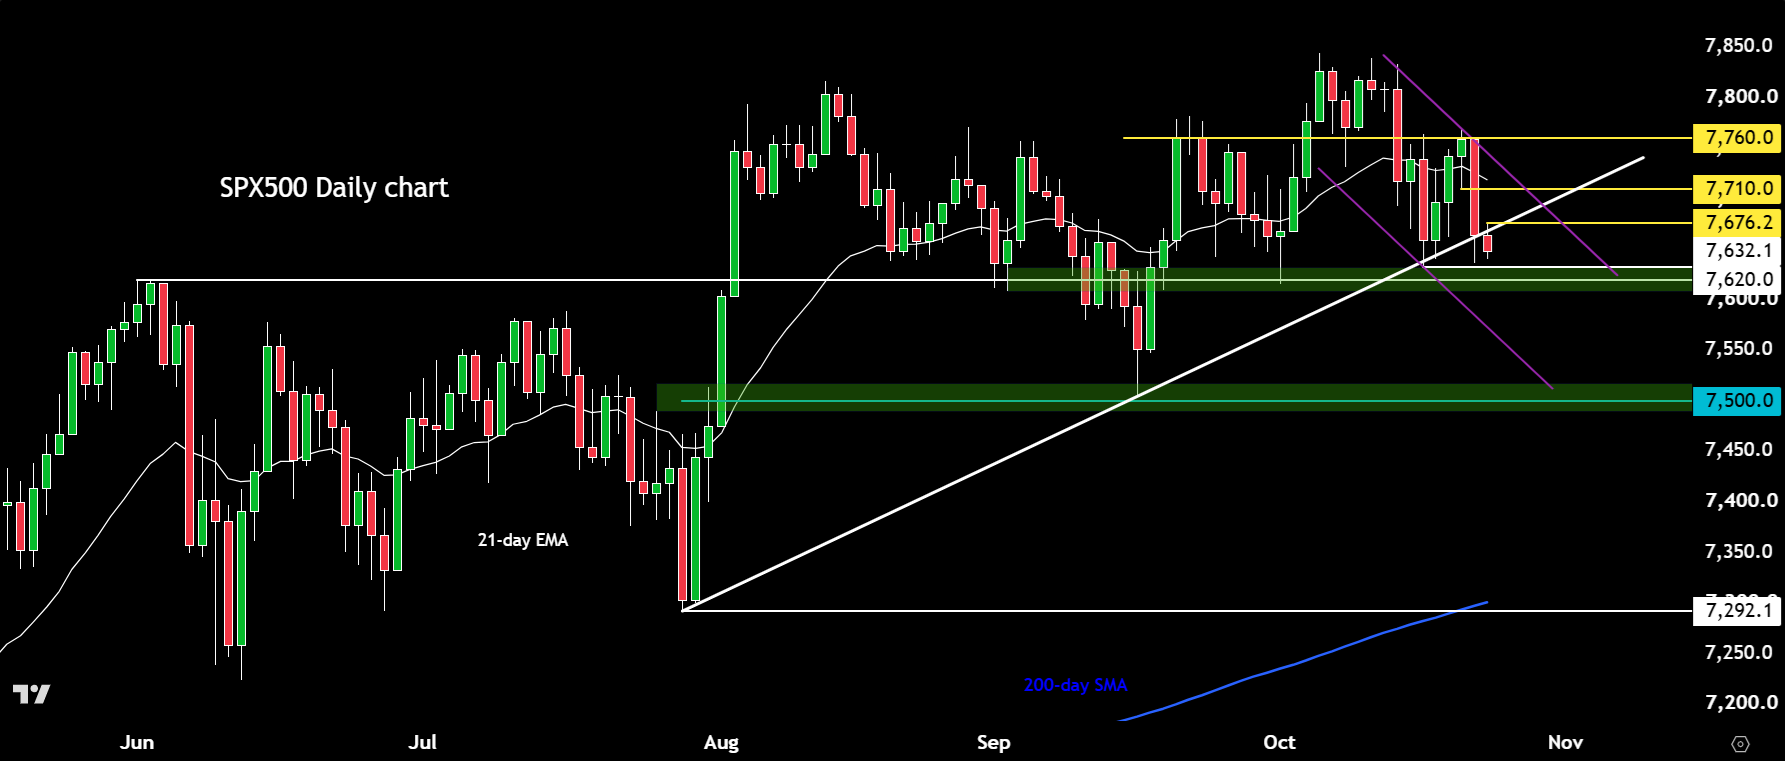
Meanwhile key short-term support sits at around 7620-35 area on S&P 500 chart. This is the zone to watch for a potential breakdown that could then pave the way for a deeper correction with the next obvious support not seen until around 7,500.
On the upside, initial resistance is the underside of the trend line and today’s earlier highs near 7676. Above that Wednesday’s low of 7,710 comes into focus next, followed by the bear resistance trend of the bearish channel slightly above. Break that and things will start to improve from a technical analysis view point for the S&P 500 forecast.

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 forecast: AI linked stocks remain under pressure
And just like that, it is Friday again and the end of a volatile week. Today offers little on the macro calendar to change the prevailing narrative, leaving markets largely at the mercy of risk appetite, oil prices and the growing unease around the AI trade.
Nasdaq 100 Slides as Meta Posts Strong Results and Drops 6%
The Nasdaq 100 sell-off is being driven by doubts over AI spending, as investors punish strong earnings that fail to justify stretched valuations.
USD/JPY, Nikkei Break Lower as AI Meltdown Spreads
Thursday’s tech tantrum has become Friday’s fire sale. With Nikkei support giving way and the yen strengthening, could the selling start feeding on itself?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.