



Markets Rally on Softer US CPI | Tech Leads, DAX Reclaims Bullish Structure
US equities rebounded on softer CPI, lifting rate-cut expectations and powering a tech-led rally, with semiconductors outperforming. Shutdown-distorted labour and consumption data kept macro uncertainty elevated, while Japan’s rate hike pushed yields to multi-year highs. Eurozone inflation stayed near target, resource stocks surged, and the DAX regained bullish momentum above key Fibonacci levels. Market tone: constructive but prone to near-term volatility.
Share this:
Market Summary
Equities & Rates
- US equities rebounded after softer-than-expected November CPI boosted rate-cut expectations.
- Nasdaq +1.38%, S&P 500 +0.79%, Dow +0.14%.
- Markets now price a 58% chance of Fed easing by March.
- Tech outperformed:
- Micron +10.2% on strong AI-driven profit guidance, lifting semiconductor peers; the Philadelphia Semi Index +2.6%.
- Trump Media +41% after announcing a $6bn all-share merger with TAE Technologies.
- Lululemon +3.5% on reports of a major activist stake.
Asia
- Asian markets followed the US tech rally.
- Nikkei +1%+ after the BoJ hiked rates to 0.75% and hinted at further tightening; Topix +0.8%.
- JGB yields hit ~2%, highest since 2006, as investors assess the BoJ’s tightening trajectory.
Macro
US labour, inflation, and consumption data were distorted by the shutdown
- Jobs:
- October’s reported –105k jobs entirely reflected the DOGE deferred resignation program, which removed 162k federal jobs on paper.
- Private payrolls were actually +52k in Oct and +69k in Nov.
- Unemployment rose to 4.6% mostly due to temporary layoffs of furloughed federal workers.
- Retail sales:
- Headline flat in October, but:
- Auto sales –1.6% after EV credit expiry pulled demand forward.
- Gasoline spending –0.8% thanks to lower prices.
- Online sales +1.5%, showing early holiday buying strength.
- Headline flat in October, but:
- Inflation:
- Headline CPI eased to 2.7% YoY (vs 3.0% Sep).
- Core CPI slowed to 2.6% (vs 3.0% expected).
- Shutdown disruptions — with data collection beginning only Nov 14 — may have artificially depressed some categories such as core goods.
- Market reaction:
- Treasury yields fell only slightly (10-yr ~4.1%).
- Equity indices, still down ~2% on the week, remain driven by concerns about AI investment intensity, not macro relief alone.
Nasdaq-100 Reconstitution (December)
Removed: TTD, LULU, ON, CDW, GFS, BIIB
Added: FER, MPWR, ALNY, WDC, STX, INSM
Eurozone
Inflation near target — ECB on hold
- November Eurozone CPI to be published tomorrow, but major countries released early data:
- Germany HICP: 2.6% (highest in nine months; above 2.4% consensus).
- Spain: 3.1% (above consensus).
- Italy: 1.1% (well below consensus).
- ECB sees stable inflation path and expects moderate growth (2025–2028: 1.2–1.4%).
- Markets showed little reaction as US CPI dominated attention.
Europe – Resources Sector
- European resource stocks gained >20% over the last three months.
- Drivers: sharp rises in copper, aluminium, silver, gold; copper boosted by supply disruptions at a major mine and low inventories.
- After ~14% earnings decline in 2025, analysts expect >30% EPS growth in 2026.
- Sector trades at ~14x forward earnings, ~25% above its 20-year median → increased risk of volatility next year.
DAX
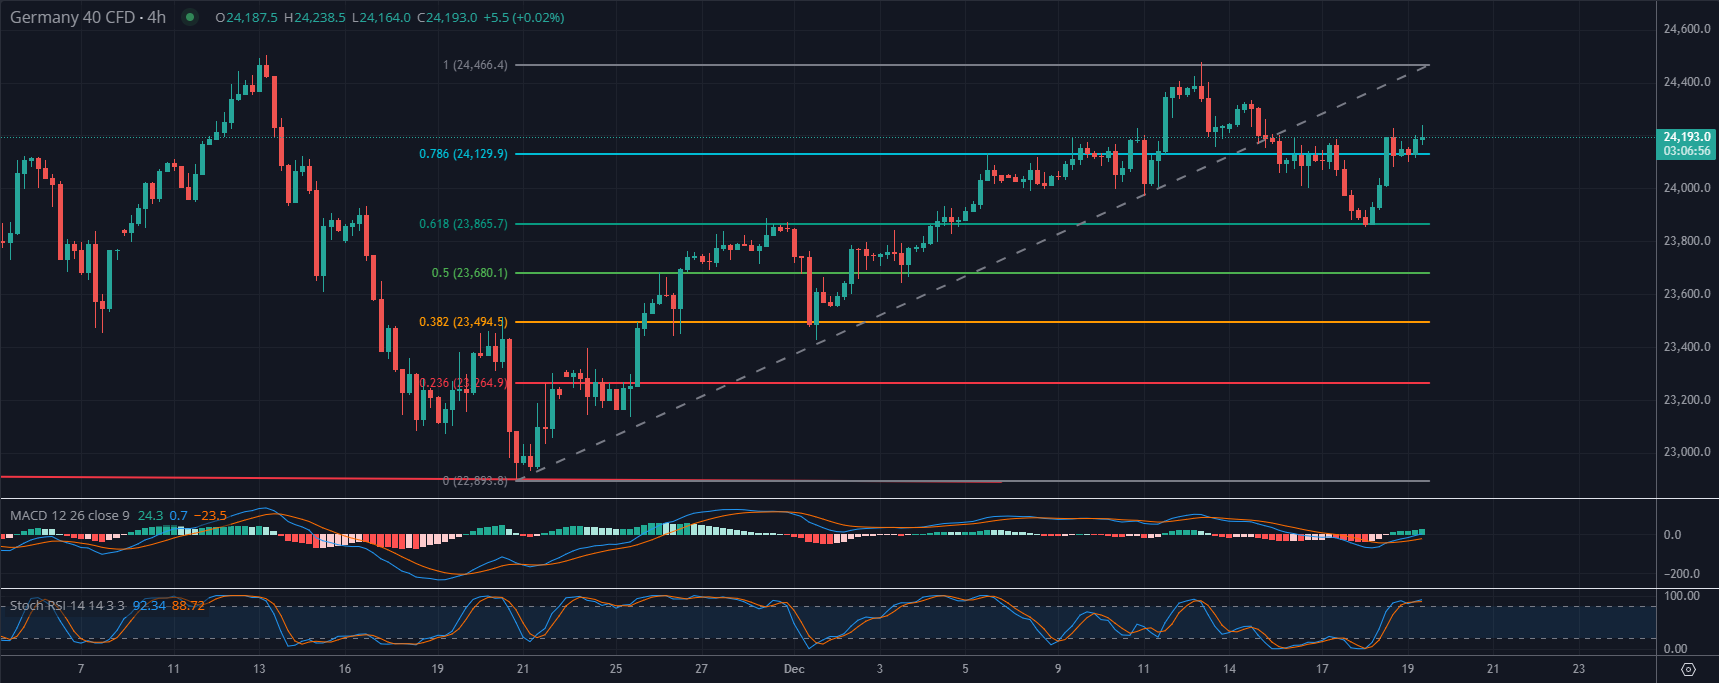
The 4-hour chart for Germany 40 shows a strong recovery after the recent correction, with price now trading at 24,193.6 and holding above the ascending trendline drawn from late November. The index has reclaimed the 24,129 level, which corresponds to the 78.6% Fibonacci retracement of the prior bullish leg, signaling renewed buying pressure. The short-term structure is bullish again, as price is consolidating above the broken trendline and near the upper retracement zone. The next resistance is the recent high at 24,466.4, while immediate support lies at 24,129 and then 23,857 (61.8% Fib).
Momentum indicators confirm the bullish shift. MACD has crossed into positive territory, with the histogram expanding, indicating strengthening upward momentum. Stochastic RSI at 88.72 is in overbought territory, suggesting the rally may face short-term exhaustion or consolidation before another leg higher. If price sustains above 24,129, the next upside target is 24,466.4; failure to hold this level could trigger a pullback toward 23,857 and 23,681 (50% Fib). The technical bias favors continuation toward the recent high, but overbought conditions warrant caution for near-term volatility.
In short: Markets rallied on softer US inflation and strong semiconductor momentum, even as underlying US data remain distorted by the shutdown. Japan tightened policy, pushing yields to multi-year highs. Eurozone inflation remains close to target, resource stocks surged on supply tightness, and the Nasdaq-100 will see notable constituent changes.
-Philip Papageorgiou – Market Analyst
--X ex Twitter: PhilipForexCom
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.


Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.


What Stretched 10-Year Yields Mean for Major Currency Pairs in Q4
U.S. 10-year Treasury yields are nearing a long-term resistance zone with overbought RSI readings, raising near-term pullback risk for the dollar.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.