

Market Brief: Markets Quiet in Holiday Session as DAX Holds Bullish Structure
Global markets traded quietly amid widespread holidays, while futures edged higher ahead of key US GDP and PMI data. Gold slipped and yields fell as investors priced in mid‑year Fed cuts. Chinese equities remain shut for Lunar New Year, with medium‑term sentiment supported by tech easing ahead of the Xi–Trump summit. The DAX holds firmly above the 100/200‑SMA, forming an inverse H&S structure pointing toward 25,050 resistance.
Share this:
TODAY – MARKET SNAPSHOT
Market Holidays
- US: Washington’s Birthday
- China: Lunar New Year
- South Korea: Korean New Year
- Canada: Family Day
Asia
- Muted trade on holiday closures: China, South Korea and Taiwan were shut for Lunar New Year, leaving thin liquidity. Japan’s Nikkei +0.2% and MSCI Asia-Pacific ex‑Japan +0.4% posted modest gains.
- Japan GDP disappoints: Q4 GDP grew 0.2% annualised (vs. 1.6% est.), dampening sentiment and reinforcing expectations of further fiscal support.
Global Macro
- Futures slightly higher: US and European equity futures edged up ahead of Friday’s US Q4 GDP (3.0% est., down from 4.4%) and global manufacturing PMIs.
- AI capex weighing on buybacks: Hyperscaler capital expenditure has reached USD 660bn, contributing to a 7% YoY decline in S&P 500 buybacks and driving rotation into defensives. Software stocks are down 24% over the last three months.
Rates
- Treasury yields fall: The US 2‑year yield closed at 3.408%, the lowest since mid‑2022. Markets now price a 68% probability of a Fed cut in June and ~62bps of easing in 2026.
FX & Commodities
- Dollar steadies: DXY slightly firmer; USD/JPY 153.05.
- Gold under pressure: Gold fell 1.3% to USD 4,973/oz.
- Oil flat: Prices steady amid reports OPEC+ may resume output increases in April.
MARKETS RECAP
US Macro
- Stronger payrolls: Job growth exceeded expectations; unemployment edged lower.
- Moderating CPI: Headline inflation softened more than expected; core CPI unchanged month‑on‑month.
Equities
- Nikkei rally: Japanese markets surged following Sanae Takaichi’s strong election win.
- FTSE 100 record highs: Supported by miners and resilient consumer staples.
Crypto & Metals
- Cryptocurrencies stabilise: Late‑week buying supported the complex.
- Gold and silver recovery intact: Both metals maintained their rebound despite volatility.
CHINA – PRE‑NEW‑YEAR MARKET CONDITIONS
Chinese equities ended Friday lower, reversing mid‑week gains as investors reduced risk ahead of the Lunar New Year. Mainland exchanges remain closed through next Monday, while Hong Kong reopens on Friday.
In the coming quarters, China is expected to focus on stabilising the property market, boosting domestic demand, and strengthening strategic industries. Premier Li Qiang recently called for accelerated progress in technological innovation and AI across the value chain.
Sentiment may also benefit from the April Xi–Trump summit, along with the US decision to ease certain tech restrictions ahead of the meeting. Following the recent consolidation, Chinese equities retain medium‑term catch‑up potential.
US INFLATION – FED OUTLOOK
US inflation cooled more than expected in January: headline CPI fell from 2.7% to 2.4%, and core CPI slipped to 2.5%, the lowest level in nearly five years. Equities reacted mildly positively, Treasuries were in demand, and the USD softened slightly. Markets continue to expect the next Fed cut in July, with just over two 25bp cuts priced for 2026.
With inflation easing, the Fed’s focus is shifting more toward labour‑market dynamics. This stance is likely to remain unless underlying price pressures re‑accelerate or inflation expectations move higher. Importantly, before the March 18 FOMC meeting, policymakers will receive three more inflation reports: February CPI and December & January PCE.
US TRADE – EQUITIES
US markets finished Friday mixed. Small caps outperformed (RUT +1.18%), and equal‑weight indices showed strong breadth, while mega‑cap sectors (Tech, Communication Services, Consumer Discretionary) weighed on broader benchmarks.
The CPI report was the main event: headline inflation was softer, core in line. Goods disinflation continued, but services inflation picked up again, raising concerns flagged by Fed’s Goolsbee. Treasuries bull‑steepened following the release.
SPX +0.05%, NDX +0.18%, DJI +0.10%.
TARIFFS / TRADE
- US–Ecuador trade agreement expected within weeks.
- China to waive VAT on selected seeds, genetic resources and police dogs through 2030; zero‑tariff access for 53 African nations from May.
- China told France & Germany that it seeks partnership rather than rivalry and wants deeper cooperation.
US HEADLINES
- Goolsbee: Services inflation remains elevated; rates can still move lower.
- Trump: Will impose new voter‑ID rules via Executive Order.
- Pentagon: Threatened to cut ties with Anthropic over military‑AI usage restrictions.
APAC TRADE – EQUITIES
- Regional markets opened stronger, though gains were capped by holiday closures.
- ASX 200: tech‑led gains.
- Nikkei: flat after weak GDP.
- Hang Seng: modest rise but pressured by tech weakness and confusion over a Pentagon list later withdrawn.
FX
- DXY slightly higher; EUR/USD & GBP/USD rangebound.
- GBP faced resistance near 1.3650 after BoE’s Mann warned of sluggish UK growth.
- USD/JPY moved above 153 after weak Japanese GDP.
FIXED INCOME
- USTs stable in thin trading; 10‑yr futures above 113.00.
- Bunds lacked direction.
- JGBs slightly higher, capped below 132.00.
COMMODITIES
- Oil rangebound amid speculation OPEC+ could raise output from April.
- Gold paused after Friday’s post‑CPI rally.
- Copper subdued with China shut.
- US startup Hertha Metal claims it can produce steel at 25% lower cost.
NOTABLE ASIA‑PAC HEADLINES
- Xi emphasised domestic demand as the main growth driver.
- China establishing a permanent rural revitalisation funding framework.
- Regulators summoned major platforms: Alibaba, Douyin, Meituan.
- Disney issued cease‑and‑desist to ByteDance over AI video training.
DATA RECAP
Japan:
- GDP Q4 (Q/Q): 0.1% (est. 0.4%)
- GDP Annualised: 0.2% (est. 1.6%)
UK:
- Rightmove House Prices (Feb): 0.0% m/m, 0.0% y/y
GEOPOLITICS
Middle East
- US preparing options for potential multi‑week operations against Iran.
- Trump told Netanyahu he would support a strike on Iran’s missile program if diplomacy fails.
- US–Iran indirect talks resume Tuesday in Geneva.
- Iran open to compromises tied to sanctions relief.
- Israel approved registering West Bank lands as state property; Palestinians condemned the move.
Russia–Ukraine
- Trump: Zelensky “has to get moving”; says Russia wants a deal.
- US Secretary of State Rubio met Zelensky; uncertain Russia is serious about ending the war.
- Ukraine targeted Russian fuel facilities in Taman.
- UK & EU weighing seizure of Russia’s “shadow fleet” tankers.
- G7 exploring a maritime services ban on Russian oil.
Other
- EU’s von der Leyen warned of external attempts to weaken EU unity; stressed that mutual defence is an EU obligation.
EU / UK HEADLINES
- BoE’s Mann: UK economy “sluggish and tepid.”
- ECB’s Lagarde: Europe must prepare for geo‑economic fragmentation; strategic autonomy needed.
- ECB to expand repo backstop to eligible central banks globally from Q3.
DAX Technical Analysis
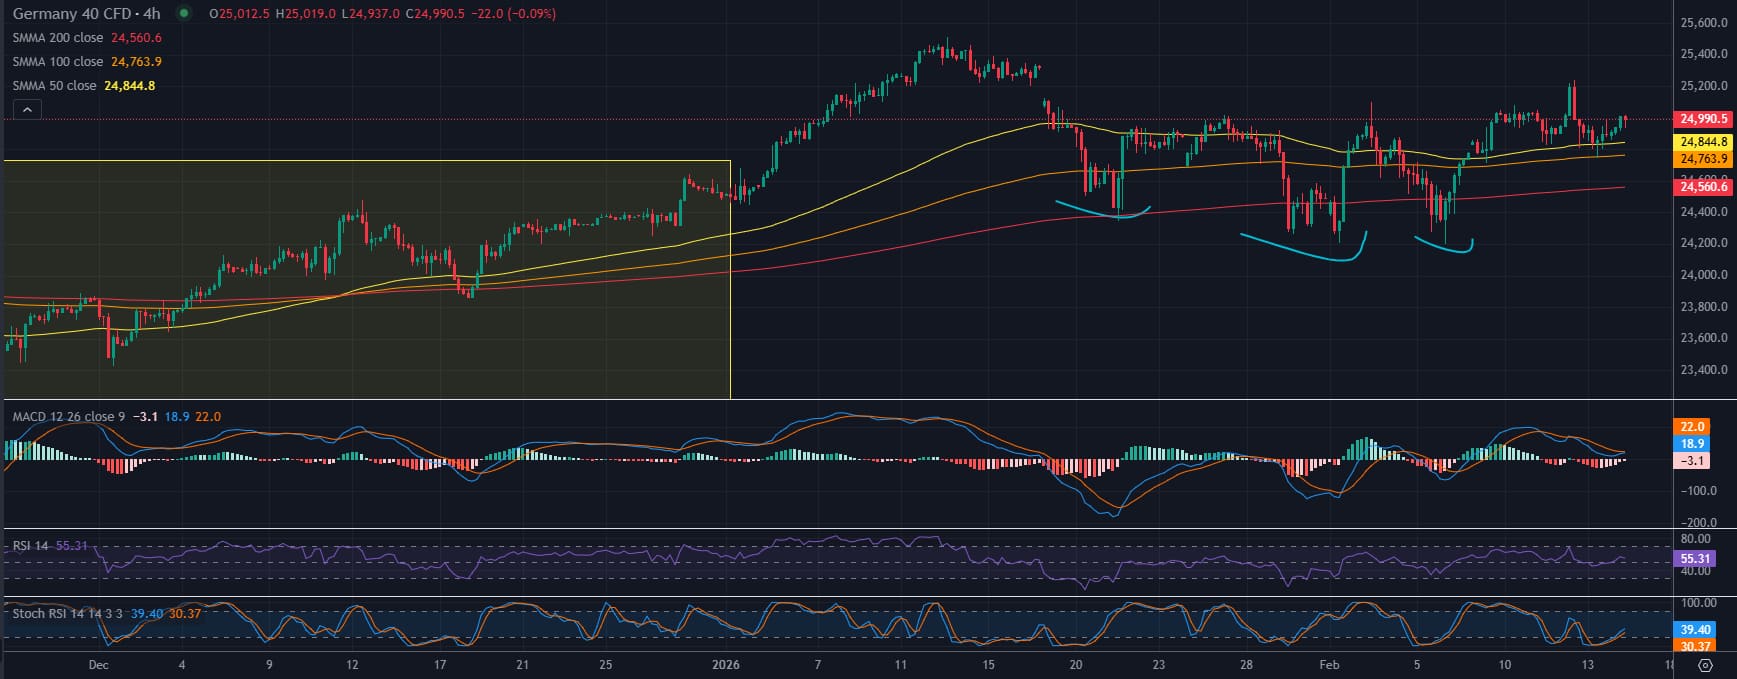
The Germany 40 continues to stabilize above the 100‑SMA and 200‑SMA on the 4H timeframe, reinforcing the market’s medium‑term bullish tilt despite recent volatility. The repeated higher‑lows around 24,450–24,500 form a well‑defined inverse head‑and‑shoulders pattern, suggesting accumulation and a gradual shift in momentum back toward buyers. Price is now holding above the cluster of moving averages, with the 50‑SMA beginning to turn upward—often an early signal that downside pressure is fading. Immediate resistance sits near 25,050, where multiple rallies have been rejected, making this the key level to break for bullish continuation.
Momentum indicators support this constructive structure. MACD has pulled back but remains above its zero line, indicating that underlying momentum is still positive despite the current consolidation. RSI sits in neutral territory, providing room for a renewed upward move, while the Stochastic oscillator is curling higher from mid‑level readings, which often precedes short‑term bullish swings. Overall, the setup remains supportive of a continuation move higher as long as price holds above 24,500, with a breakout above 25,050 likely opening the path toward the February highs.
-Philip Papageorgiou – Markt Analyst
--X ex Twitter: PhilipForexCom
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Faces Defining Day with ECB, US GDP and Earnings
Today's session is dominated by three major catalysts: the ECB rate decision, US GDP and inflation data, and a packed earnings calendar featuring Amazon, Intel, Mastercard, Caterpillar and Volkswagen. While the DAX has reclaimed the critical 25,500 level, and sliced up right to around 26,000. The move back toward support will likely be determined by central bank guidance, inflation signals and corporate earnings.
Nasdaq 100 forecast: Alphabet results reignite AI concerns
Disappointing results from a couple of major global technology names have put the AI trade back under scrutiny, with Nasdaq 100 futures falling around 1% after giving up the post-FOMC gains seen overnight. For now, our short-term Nasdaq 100 forecast remains more on the cautious side of things than outright bearish. The index remains close to its record highs and continues to find dip buyers. But could that change soon?

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.