
DAX Faces Defining Day with ECB, US GDP and Earnings
Today's session is dominated by three major catalysts: the ECB rate decision, US GDP and inflation data, and a packed earnings calendar featuring Amazon, Intel, Mastercard, Caterpillar and Volkswagen. While the DAX has reclaimed the critical 25,500 level, and sliced up right to around 26,000. The move back toward support will likely be determined by central bank guidance, inflation signals and corporate earnings.
Share this:
DAX 40 Technical Analysis: ECB Decision and US Data Put Markets on Alert
Thursday, 29 October 2026
Market overview: A cautious open ahead of the ECB
The DAX 40 closed Wednesday at 25,704, gaining 0.44% as improving sentiment around AI-related stocks helped European equities stabilize. However, the overnight mood is more mixed, with disappointing Alphabet results weighing on US technology futures and investors preparing for today’s European Central Bank decision and key US economic releases.
The near-term technical picture remains constructive, but the index is approaching resistance after its recent recovery above 25,500. The next target that buyers need to push through is now 25,800.
Asia recap: Technology optimism meets earnings disappointment
Japan’s Nikkei held up relatively well, supported by semiconductor shares, while South Korea’s KOSPI came under pressure after Samsung’s results failed to satisfy elevated market expectations.
As the session progressed, the regional picture remained divided: the Nikkei was modestly higher, while the KOSPI fell around 2.2%, Taiwan’s market also declined approximately 1.9%, and Hong Kong traded close to flat. Alphabet’s roughly 10% after-hours drop added to the weight on technology sentiment, although Microsoft’s stronger cloud results balanced the move.
European open: a broadly flat start
European equity futures show a largely muted cash-market open, with Euro Stoxx 50 futures down approximately 0.4%, DAX at around 0.00%, France up 0.5%.
Now all eyes will be on the ECB’s policy decision, US third-quarter GDP and inflation data, and even more earnings from the biggest tech and industrial companies. Also noteworthy are reports of renewed diplomatic contact between Washington and Tehran, which have therefore helped oil prices retreat slightly, although the general geopolitical outlook, still remains unsure of any resolution.
DAX 40 technical analysis: Buyers face resistance near 26,000
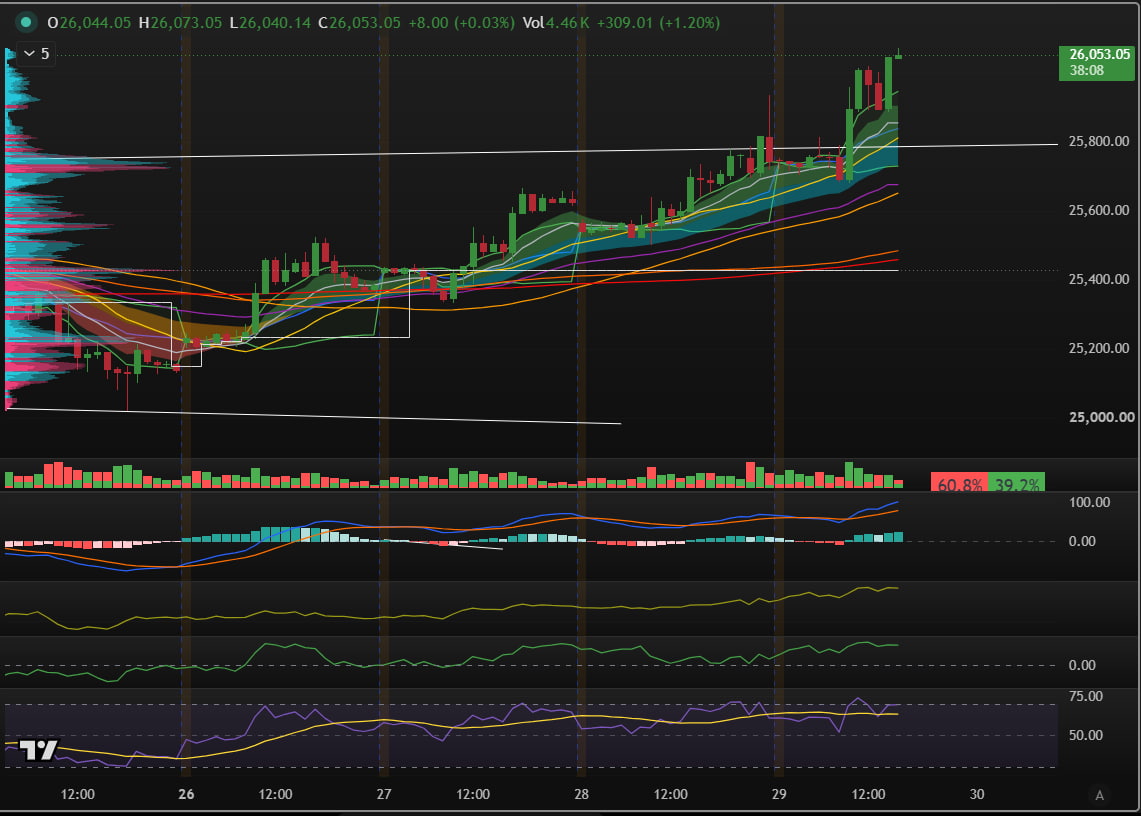
The DAX has recovered above the 25,500 area as I mentioned to be THE critical level that the DAX needed to break. This previously acted as an important support and resistance level. Now, the ability to hold this region has improved the short-term bullish outlook, while many of the 4H technical readings also show the index above its 20, 50, 100 and 200-day moving averages. The daily RSI also rose to 66, MACD is still above the 0 histogram as well.
The immediate resistance zone sits around 26,000 – 26,100. A sustained break above this area would strengthen the bullish case and open the way towards the psychologically important 26,000 level followed by resistance at 26,150. However a longer term recovery would become more convincing if the index can hold above 25,500, just enough to tilt the EMA 200 back into an ascending direction.
On the downside, initial support is located around 25,600, followed by the more important 25,500 region. A move below 25,500 would weaken the current recovery and bring 25,400 back into focus. This is also consistent with the recent technical view that 25,500 and 25,400 are important support levels.
Key events today
The ECB interest rate decision, ECB Monetary Policy Statement and ECB Press Conference are todays main European events, where investors are looking for guidance from policymakers as to the inflation, growth and the outlook for future interest-rate decisions in the Eurozone.
In the US, the first estimate of third-quarter GDP, September personal income and spending, core PCE inflation data and weekly jobless claims can cause volatility in bond yields, the dollar and equities. On yesterday’s Federal Reserve meeting, they held rates at 3.75%–4.00%, as expected, but two policymakers dissented in favour of a rate increase, this means we should watch US inflation risks more from now on.
Today’s calendar:
• 11:00 CET: Eurozone economic and industrial confidence; final consumer confidence.
• 13:30 CET: US third-quarter GDP, personal income and spending, core PCE-related data and initial jobless claims.
• 14:15 CET: ECB interest rate decision, Deposit Facility Rate, ECB Marginal Lending Facility, ECB Monetary Policy Statement.
• 14:45 CET: ECB Press Conference
• Throughout the session: Comments from ECB officials, including Christine Lagarde (16:25) and Piero Cipollone. Also German Vuba Mauderer Speaks at 15:30.
Earnings to watch today
Amazon.com (AMZN)
Eli Lilly (LLY)
Mastercard (MC)
Intel (INTC)
Caterpillar (CAT)
SanDisk (SNDK)
Starbucks (SBUX)
Monster Beverage (MNST)
BYD (BYD)
L3 Harris Technologies (LHX)
Coinbase Global (COIN)
Volkswagen (VW)
Today’s corporate calendar is filled with names in all sectors. This week over 1/3rd of all S&P companies are reporting. Also today is particularly important for Germany and the wider European market as important companies like Volkswagen, Adidas and MTU Aero Engines are among the major German names reporting, which can show us insights into automotive demand, consumer spending and aerospace activity.
Trade Safe,
By Philip J Papageorgiou - Head of Investment Research
Follow me on X (ex Twitter) - PhilipForexCom
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Faces Defining Day with ECB, US GDP and Earnings
Today's session is dominated by three major catalysts: the ECB rate decision, US GDP and inflation data, and a packed earnings calendar featuring Amazon, Intel, Mastercard, Caterpillar and Volkswagen. While the DAX has reclaimed the critical 25,500 level, and sliced up right to around 26,000. The move back toward support will likely be determined by central bank guidance, inflation signals and corporate earnings.
DAX Faces Fresh Pressure from Tech Rout and Middle East Risks
The DAX has come under renewed pressure as another technology-led sell-off on Wall Street undermines global risk sentiment. While the index remains above key October lows, the recent recovery is losing momentum as investors reassess AI valuations, rising energy prices and escalating geopolitical risks. With oil climbing and major technology stocks facing renewed selling pressure, the focus has shifted back to support levels rather than fresh highs.
USD/JPY, DXY Outlook: Hawkish Holds and Key Resistance Levels
USD/JPY and DXY face key resistance levels as markets weigh Fed and BOJ rate expectations, inflation and geopolitical developments
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.