



Nasdaq 100 Outlook: Stocks slip on China news & ahead of FOMC minutes
US stocks are pointing to a weaker start as traders return from the Independence Day holiday. Weakening growth in China and news that China is placing curbs on exports of metals used in the semiconductor industry is weighing ion sentiment ahead of the FOMC minutes later today. The markets will look to the minutes for clues over the future path for interest rates.
Share this:

US futures
Dow futures -0.41% at 34230
S&P futures -0.5% at 4426
Nasdaq futures -0.49% at 15198
In Europe
FTSE -0.65% at 7470
Dax -0.7% at 15930
- FOMC minutes will be released later
- Chip stocks fall after China restrictions & weak data
- USD rises on safe-haven flows
- Oil looks to OPEC+, API inventory data
China restricts exports of chip-making metals
US stocks are pointing to a modestly weaker open after China announced curbs to chip-making material exports, as service sector growth slowed, hurting sentiment and as investors look ahead to the minutes from the June FOMC meeting.
As traders return following the Independence Day holiday, the mood has been dampened by news that China will restrict the export of metals used in the semiconductor industry in the latest tit-for-tat move in an escalating US- Sino tech trade war.
Attention is now turning to the minutes from the June FOMC meeting, where the Fed paused its rate hiking cycle after 10 straight rate hikes but pointed to two more hikes this year.
Fed Reserve Chair Powell sounded hawkish again when he spoke at the ECB annual conference last week. The committee believes that more work needs to be done, but the market will look for clues over any divisions over where the peak rate could be.
The market is pricing in a 88% probability of a 25 basis point hike in July, but the market is not convinced that the Fed will hike for a second time this year. The minutes could provide further clues. However, given the data released since the June FOMC meeting, including cooling inflation, the minutes could be considered outdated.
Corporate news
Nvidia and Micron Technology are falling pre-market due to the China restrictions.
Netflix rises after Goldman Sachs upgraded the stock and price target to $400 from $230, thanks in part to the crackdown on password sharing.
Nasdaq 100 outlook – technical analysis
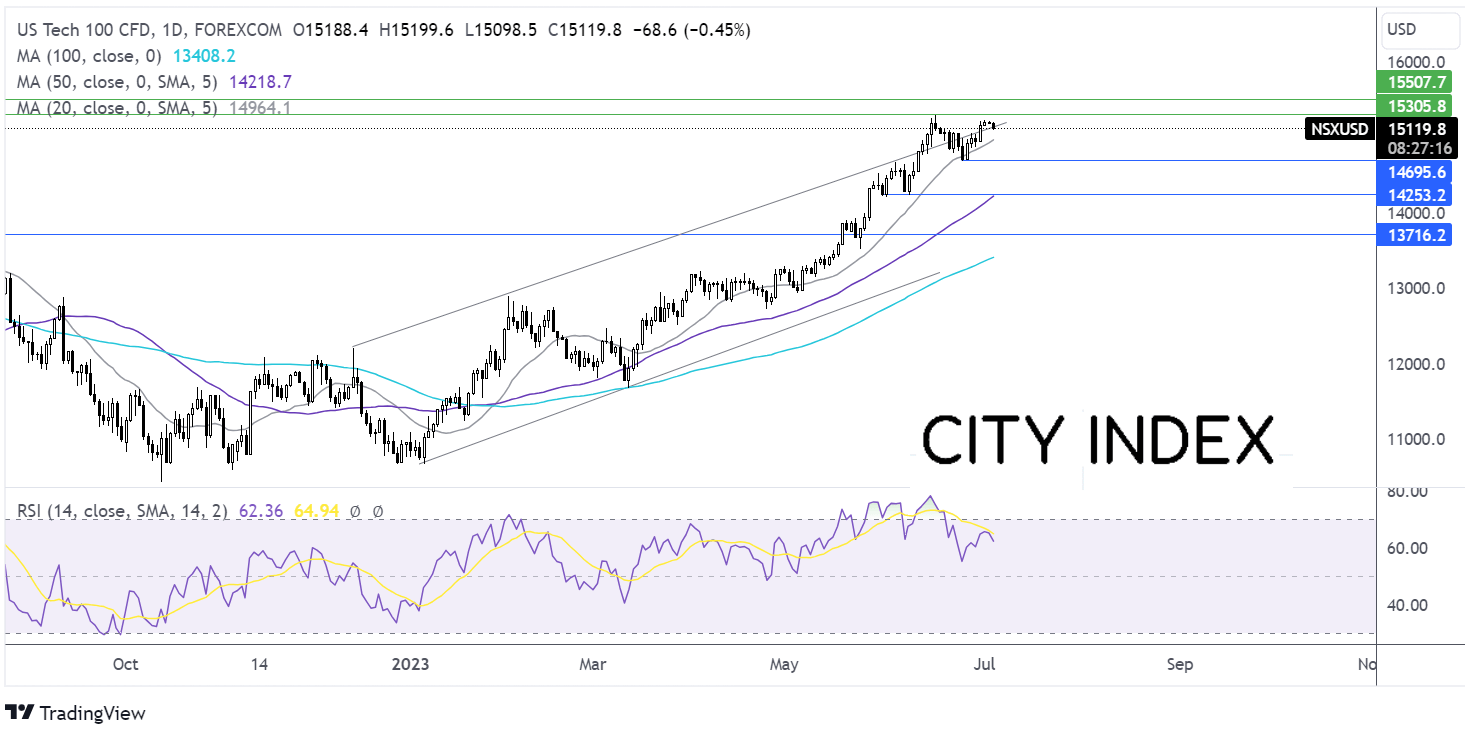
After a steep run-up, the rally in the Nasdaq 100 appears to be running out of steam. The price ran into resistance above 15200 last week and has eased back, testing the multi-month rising trendline support. A break below the support exposes the 20 sma at 14955, ahead of 14680, last week’s low. A break below here creates a lower low. On the flip side, should the rising trendline support hold, buyers could look for a rise above 15240, last week’s high, ahead of 15290, the 2023 peak.

FX markets – USD rises, EUR steady
The USD is edging cautiously higher on safe-haven flows amid concerns over slowing global growth and ahead of the FOMC minutes due later today.
EURUSD is holding steady as investors digest softer business activity in June and cooling inflation. PPI fell more than expected, dropping -1.9% MoM and -1.5% YoY in May. The data suggest that CPI could continue cooling. Meanwhile, the eurozone composite PMI fell more than expected to 49.9 from 52.8 and into contraction.
GBPUSD is holding steady as investors digest the latest business activity data. The services PMI slowed to 53.7 in June, down from 55.2, in line with preliminary estimates, despite inflation cooling. This is still above the 50-level separating expansion from contraction. However, it was still the biggest monthly decline since August 2022.
EUR/USD +0.03% at 1.0885
GBP/USD +0.02% at 1.2710
Oil trades flat as OPEC+ meets
Oil prices are holding steady but still remain only marginally higher in the week despite both Russia and Saudi Arabia announcing further production cuts on Monday, ahead of the OPEC+ meeting, which kicked off today.
Both cuts from Russia and Saudi Arabia came in addition to a previously agreed OPEC+ deal to limit supply into 2024, decided in April, and brings the total output reductions announced to 5 million barrels per day or around 5% of global oil output. However, these surprise cuts have failed to result in a sustained rise in oil prices.
Oil prices remain subdued for several reasons, including concerns over the recovery in China losing momentum, higher interest rates for longer, and rising US output.
China services PMI eased to 53.9 and comes after manufacturing PMI data eased earlier in the week. Slowing China growth and higher interest rates in the US and globally are weighing on the oil demand outlook.
US API inventory data is due later and is expected t show a draw of 1.8 million barrels in the week ending June 30.
WTI crude trades +0.1% at $71.50
Brent trades at +0.4% at $76.15
Looking ahead
15:00 US factory orders
19:00 FOMC minutes




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.


Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.

Nasdaq 100 Forecast: NDX slips as Treasury yields keep rising
U.S. stocks are falling at the start of Q4, as gains in software stocks offset concerns over soaring Treasury yields. U.S. Treasury yields continue to rise, with the 10-year yield up 2 basis points at 5.31% and the 30-year at 5.66%, multi-decade highs.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.