



S&P 500 forecast Hot PPI unlikely to be game changer for US stocks
US index futures dropped after the latest inflation data showed a completely different picture to the CPI print released on Tuesday, though it is far too early to change our S&P 500 forecast to bearish. Today’s PPI data revealed a surprise rise to 3.3% y/y for July which was much higher than 2.5% expected, and that raised concerns that the impact of tariffs on inflation are finally starting to show.
Share this:

US index futures dropped after the latest inflation data showed a completely different picture to the CPI print released on Tuesday, though it is far too early to change our S&P 500 forecast to bearish. Today’s PPI data revealed a surprise rise to 3.3% y/y for July which was much higher than 2.5% expected, and that raised concerns that the impact of tariffs on inflation are finally starting to show. With input costs rising, this may impact earnings for companies in Q3 and Q4. Yet, the downside was limited, suggesting that investors are not too concerned just yet and that they still believe a 25 basis point cut in September is coming.
Earlier in the day, US futures appeared poised to head to new highs – and they still might – with European markets also pushing higher in the first half of Thursday’s session. Underscoring the positive vibes, we saw Bitcoin hit a new record high above $24.5K before profit taking saw it drop about 5% from its intraday high. The US dollar continued to remain on the back foot, which saw the USD/JPY pair take a dip to near 146.00.
With PPI out of the way, investors are looking ahead to the release of retail sales and the UoM surveys on Friday. Dip buying remains the strategy of choice against a backdrop of strong momentum and rising expectations of multiple Fed rate cuts over the next several months. The PPI jump could be a one off, but certainly needs to be monitored closely in the coming months.
What to make of the PPI data?
Well, it clearly shows Powell was right about inflation concerns and a lesson for Trump and co to let the experts do their jobs. The rising costs as highlighted by PPI report, but a not so-strong-CPI report shows companies are so far absorbing these. But as margins tighten, producer will have no choice but to pass on some of these costs onto the consumer.
So far, the market is still nearly fully expecting a 25 basis point cut in September. It is likely that the Fed will see through the rise as the one-time increase and their concerns about the jobs market may make them more open to the idea of resuming rate cuts from September.
We’ve still got a fair bit of data to chew over before the Fed next meets — another jobs report, an inflation print, and a smattering of other macro releases. But with that soft labour market reading, hefty downward revisions to previous months, and an inline CPI print this week, today’s hot PPI data has reduced the case for a September rate cut ever so slightly.
Some have been floating the idea of the Fed going bigger, but frankly, it’s a stretch, especially given today’s PPI data. US Treasury Secretary Bessent reckons a 50bp cut in September is the right call, arguing that rates are a full 150–175bps above where they should be. Trouble is, markets aren’t buying it. Without some clear nod from Fed officials, or an ugly collapse in the jobs numbers, a half-point cut seems firmly in the ‘unlikely’ column.
Friday’s focus will be on consumers and geopolitics
Friday’s calendar brings the University of Michigan’s consumer sentiment survey, offering a peek into inflation expectations. But before that, retail sales will drop, and they might prove the bigger market shaker. Expectations are for a modest slowdown in spending growth — confirmation of that could put renewed pressure on the dollar, while the S&P 500 forecast is unlikely to be hit hard unless we see a massive disappointment on the headline sales figure.
And then there’s the political wildcard — the Trump-Putin meeting on Friday. Hopes are quietly building for a ceasefire in Ukraine and perhaps a longer-term path to peace. That said, it’s a delicate and deeply entrenched situation; optimism is welcome, but realism probably remains the safer bet.
Technical S&P 500 forecast: key levels to watch
From a purely technical point of view, the trend on the S&P 500 remains bullish even if the negative divergence on the RSI points to waning momentum. Markets have bought every dip since the April bottom, with the downside being progressively shallower and support levels have been defended. Resistance levels get taken out easily. All this shows that buying the dip in an upward trending market is the trade to focus on, regardless of macro factors.
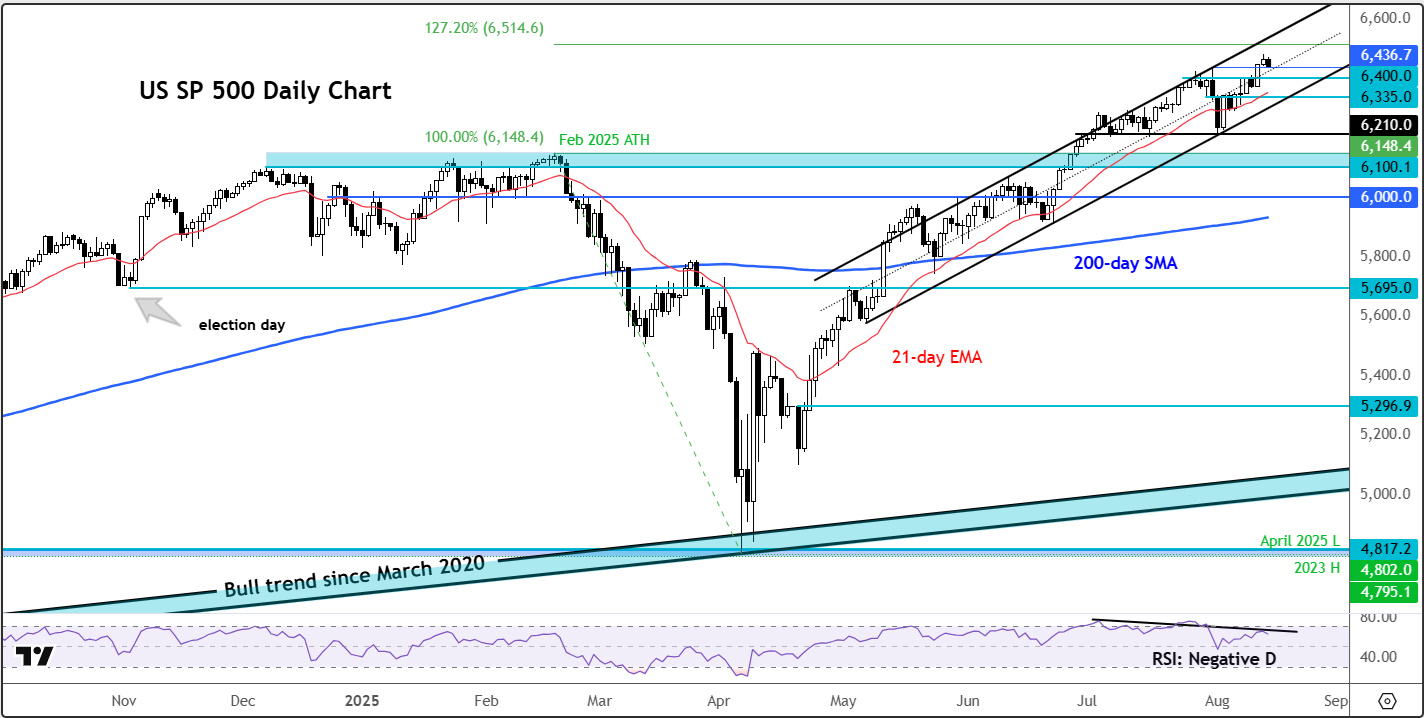
The latest breakout to new highs has left behind several support levels that were formerly resistance. On our US SP 500 index, which is derived from the S&P 500 futures, these include 6436, 6400 and 6335. Below these levels, prior support at 6210 comes into focus and then the old record high from February at 6148.
On the upside, there is no prior reference points to highlight as potential resistance, so Fibonacci extension levels and round handles like 6500 are your guides. The 127.2% Fibonacci extension from the downswing that commenced in February comes in at 6514, where we may see some profit-taking around should we get there.
-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R


The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.

Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.

EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.