


S&P500 Forecast: SPX inches higher after CPI rises, as expected
US stocks are edging lower after losses in the previous session as investors digest the latest US inflation data while looking ahead to more Fed speakers later today. US inflation was in line with forecasts, rising 0.2% MoM (2.6% YoY), while core inflation was also as expected, rising 0.3% MoM (3.3% YoY). The data supports a December rate cut.
Share this:
US futures
Dow future 0.21% at 44001
S&P futures 0.15% at 5998
Nasdaq futures 0.14% at 21111
In Europe
FTSE 0.01% at 8020
Dax -0.37% at 18986
- US inflation rose 0.2% MoM, 2.6% YoY
- Treasury & USD ease, stocks inch higher
- Fed speakers are in focus later
- Oil steadies around a 2-week low
US CPI brings no surprises
U.S. stocks are edging higher after losses in the previous session and as investors digest the latest US inflation data, while looking ahead to more Fed speakers later today.
US inflation was in line with forecasts, rising 0.2% on a monthly basis (2.6% YoY), while core inflation was also as expected, rising 0.3% on a monthly basis (3.3% YoY). While the Fed focuses on the core PCE measure for inflation, for traders, the CPI report is as significant.
Given the few surprises in the report, the market reaction has been relatively muted. US treasury yields and the USD have eased slightly, and futures have recovered from earlier lows, suggesting a measure of relief that inflation wasn’t hotter, given the recent solid economic data from the US while supporting a December rate cut.
US stocks had struggled yesterday owing to the sharp rise in U.S. Treasury yields. Yesterday, the benchmark 10-year yield rose to its highest level since July.
Bond yields have soared following Trump's victory on expectations of lower taxes and higher tariffs, which will increase government borrowing and push up the deficit. These same policies are considered to be inflationary, potentially slowing the Feds' path for rate cuts.
The market is currently pricing in a 63% probability of the Fed cutting rates by 25 basis points in the December meeting, this was down from almost 80% prior to the election last week.
There are plenty of Fed officials scheduled to speak later today and could shed more light on the Fed’s future path for rate cuts. Yesterday Neel Kshkari
Corporate news
Rivian is set to open 12% higher after the EV maker and Volkswagen announced an injection of funds into the joint venture.
Spotify is set to open over 8% higher after posting solid subscriber subscriber growth in the quarter and issuing a strong forecast for the year ahead.
Tesla is rebounding from steep losses in the previous session despite the National Highway Traffic Safety Administration announcing that Tesla will recall 2431 vehicles in the US over safety concerns. Tesla has been a clear beneficiary of Trump’s victory.
Spirit Airlines is set to open 65% lower after reports the troubled carrier is in final negotiations with bondholders on a restructuring plan.
S&P 500 forecast – technical analysis.
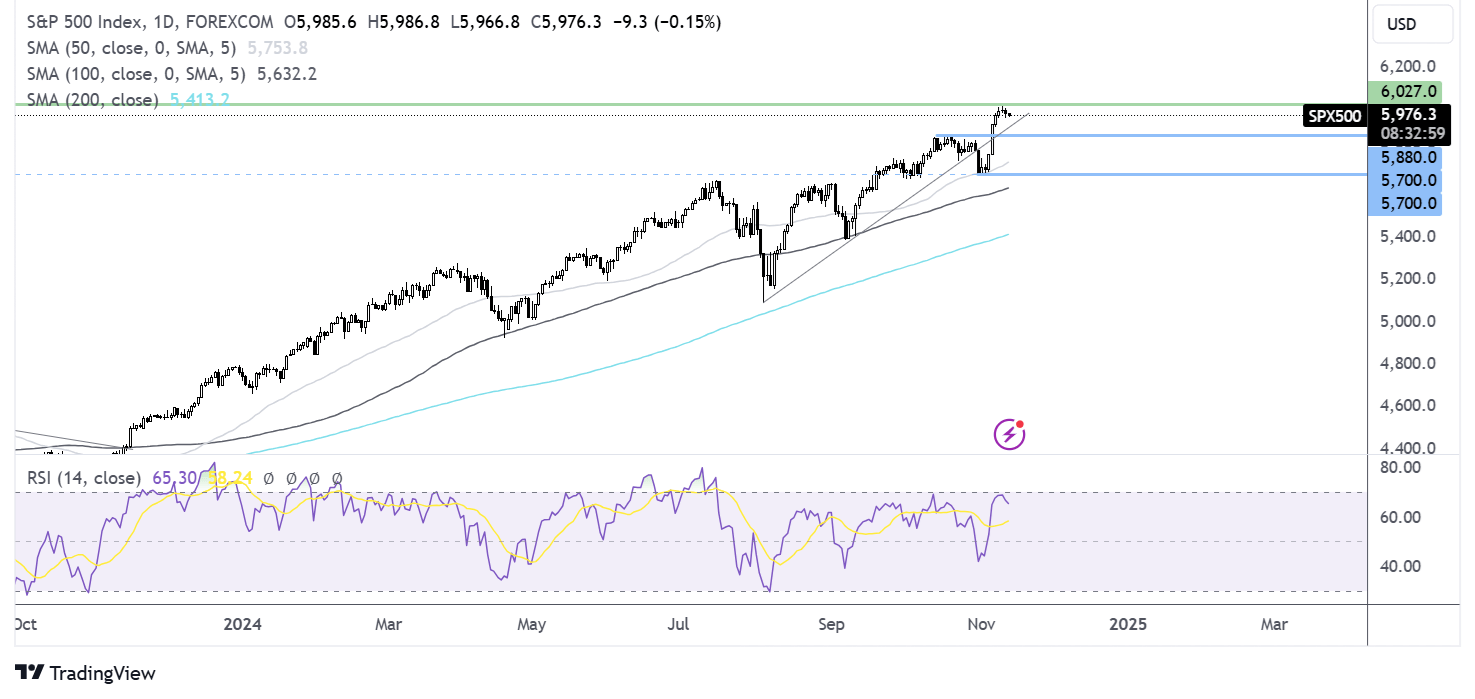
The S&P500 hovers around its all-time high of 6027, easing back modestly but still above the near-term rising trendline. Buyers will look to retake 6027 and push to fresh all time highs. Support can be seen at 5875, the October high. A break below here exposes the 50 SMA and 5700, the November low. A break below here creates a lower low.
FX markets – USD rises, EUR/USD falls
The USD is falling after inflation data brought no surprises, rising in line with forecasts.
EUR/USD has fallen to its lowest level in seven months as markets continue to fret over the potential impact of Trump trade tariffs, which could force the ECB to cut rates more aggressively. The eurozone economic calendar is quiet today, but attention will be on GDP data and the ECB meeting minutes tomorrow.
GBP/USD is hovering around a three-month low amid a quiet day for UK economic data and as investors continue to digest yesterday's mixed job data, which showed higher-than-expected unemployment and sticky wage growth. The data comes after the BoE cut rates last week but is unlikely to cut gains in December.
Oil falls on China demand concerns.
Oil prices are inching higher but remain near a two-week low amid a gloomy demand outlook following OPEC's downward revision to oil demand growth for this year and next.
Earlier in the week, OPEC lowered its forecast for global oil demand amid concerns over the outlook in China. Despite China's stimulus efforts, the market is not convinced that the measures will be sufficient. The IEA will release its monthly oil forecasts report on Thursday.
Meanwhile, the stronger U.S. dollar is also hurting oil prices as a stronger dollar makes buying oil more expensive for holders of other currencies.
.
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Analysis: Earnings Uncertainty Continues to Weigh on the SPX
The trading week is coming to an end, and a phase of weakness remains evident across the S&P 500 in the short term. Recent price action reflects this dynamic, with SPX losing more than 2.00% over the last two trading sessions, bringing selling pressure back into focus.
Nasdaq 100, S&P 500 Smashed as AI Bubble Fears Run Risk Aversion
It’s been a rocky few weeks for stocks starting with a bearish engulf in NVDA a few weeks ago and then the same formation in the S&P 500 two weeks ago. Sellers have since chewed through supports and fear is starting to spread, but is this the beginning of the end for the AI rally?
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.