



S&P 500 Forecast: SPX advances as PPI cools more than expected
U.S. stocks are heading for a higher open as investors digest the latest inflation data. While near-term Fed rate hike expectations have eased, elevated oil prices could rekindle inflation in the coming months.
Share this:
US futures
Dow futures 0.333%, S&P futures 0.20% & Nasdaq futures 0.02%
European futures
FTSE 0.03%, DAX 0.28%
- US stocks rise after PPI cooled by more than expected
- PPI was 4.7% YoY in July vs 5.5% in June
- Fed rate hike expectations cool further
- Oil falls on demand concerns
U.S. Stocks Head Higher After Cooler-Than-Expected PPI
U.S. stocks are heading for a higher open as investors digest the latest inflation data.
U.S. PPI showed that wholesale inflation cooled by more than expected, easing to 4.7% year-on-year in July from 5.5% in June and below the 4.9% forecast.
On a monthly basis, PPI was flat, defying expectations for a 0.2% increase.
The cooler PPI data was helped by a further decline in energy and food costs and could give the Federal Reserve more room to weigh inflation pressures against the recent slowdown in the jobs market.
The data comes after U.S. CPI eased to 3.4% year-on-year in July from 3.5% in June, in line with expectations.
Following the data, Treasury yields have fallen and stocks are rising as there is now more evidence that inflation is not broadly accelerating. This is reinforcing expectations that the Federal Reserve will refrain from hiking interest rates next month.
Fed rate hike expectations have cooled further, with the market now pricing in a 40% probability of a 25 basis point hike in September, down from 55% just a week ago.
However, inflation risks have not disappeared and the 20% jump in oil prices in July means that inflation could be rekindled in the coming months. Furthermore, the U.S. and Iran have made no progress towards reviving the previous peace agreement, leaving geopolitical tensions and the closure of the Strait of Hormuz as key risks to energy prices and the inflation outlook.
Corporate Movers
Tapestry — The parent company of Kate Spade and Coach is falling 7% after underwhelming Q4 results. The firm posted EPS of $1.32 on revenue of $1.88 billion, compared with expectations of $1.28 and $1.87 billion respectively.
JD.com — The U.S.-listed shares of the Chinese e-commerce company fell 4% despite beating expectations on both the top and bottom lines. Adjusted earnings came in at 6.29 yuan per share, ahead of the 5.61 yuan forecast.
Cisco — Shares are falling more than 5.5% pre-market despite better-than-expected results and guidance for Q4 fiscal 2026. The company also announced a global baseline price increase of 3.4% to 4% across its core hardware and technical services portfolio.
Netflix — Shares are up 1.8% after Bill Ackman disclosed a new position in the company, buying 3.15 million shares, four years after exiting the stock with a $400 million loss.
S&P 500 Forecast – Technical Analysis
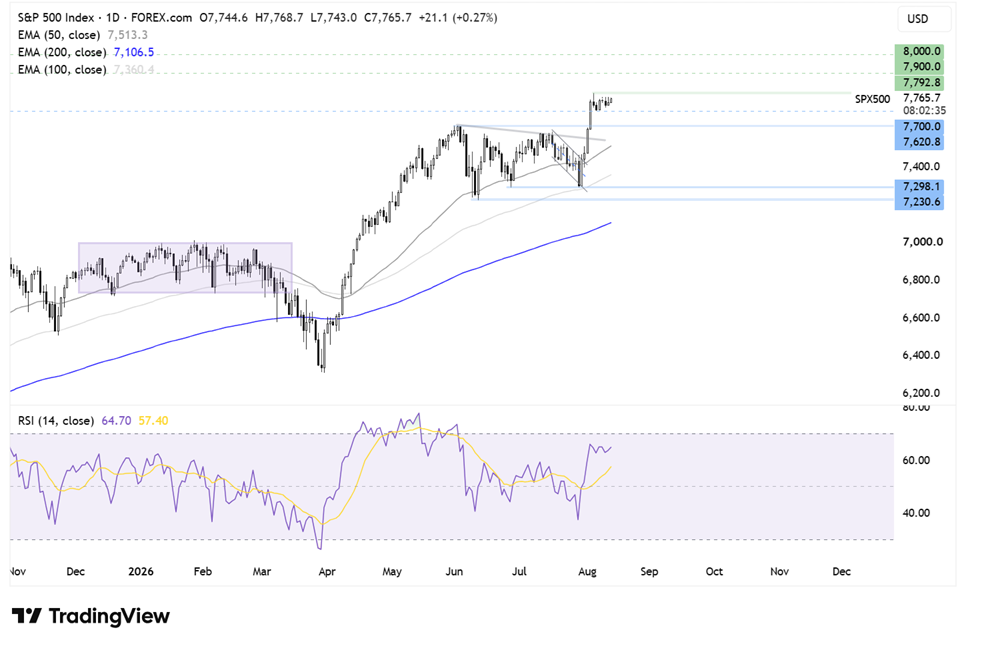
The S&P 500 recovered from the 7,470 July low, rising above the 50 EMA and the falling trend line.
The index is now consolidating above 7,750, with resistance at the fresh record high of 7,790.
Buyers will look to extend gains above 7,790, bringing 7,900 and 8,000 into focus.
On the downside, support is seen at 7,700. A break below here would open the door to 7,620, the June high, before attention turns to 7,550 and the falling trend line support.
FX Markets – Dollar Falls, EUR/USD Rises
The U.S. dollar is modestly lower, with Treasury yields also falling as oil prices decline following lower crude demand forecasts from OPEC and the IEA.The dollar is also reacting to the latest inflation data, which has reduced expectations for a Fed rate hike next month.
EUR/USD is rising after Spanish inflation came in hotter than expected. Spanish inflation rose to 3.9% in July from 3.6% in June, its highest level in two years, driven by higher electricity and fuel costs.The market is pricing in around a 90% probability that the ECB will hike interest rates again in September.
GBP/USD is rising amid a weaker USD and despite mixed UK economic data. UK Q2 GDP grew 0.4% quarter-on-quarter, down from 0.6% in Q1. However, June GDP was stronger than expected at 0.3%, supported by the World Cup and hot weather, which boosted overall economic activity.
While growth remains modest, the increase was driven by consumer spending and business investment rather than government spending, which is a more encouraging sign for the economy.
Oil falls amid a demand downgrade
Oil prices are inching lower on Thursday as investors weigh weaker global demand expectations against higher U.S. crude inventories.
Both benchmarks are trading around 2% lower.
Data showed a large build in U.S. crude stockpiles last week, putting some pressure on prices. However, that pressure could be limited while the Strait of Hormuz remains effectively closed.
U.S. commercial crude inventories rose by 17.4 million barrels last week, the largest weekly increase since January 2023, as exports slumped.
At the same time, OPEC lowered its forecast for global oil demand growth this year to 580,000 barrels per day. The IEA also expects global oil consumption to contract by 1.6 million barrels per day this year.
Meanwhile, there has still been no progress in talks between the U.S. and Iran to reopen the Strait of Hormuz, with the two sides still a long way from reaching an agreement.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.


Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.

What Stretched 10-Year Yields Mean for Major Currency Pairs in Q4
U.S. 10-year Treasury yields are nearing a long-term resistance zone with overbought RSI readings, raising near-term pullback risk for the dollar.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.