

S&P 500 Forecast: SPX rebounds amid revived AI enthusiasm
U.S. stocks are opening higher as returning AI enthusiasm overshadows a jump in Treasury yields.
Share this:

US futures
Dow futures 0.27%, S&P 500 futures 0.9% & Nasdaq futures 1.9%
European futures
FTSE 0.1%, DAX 1%
- US stocks rebound as AI enthusiasm returns
- CoreWeave beats forecast, easing AI slowdown fears
- US Treasury yields jumped to 5% post CPI, hawkish Fed commentary
- Oil rises after falling to a 2-month low
U.S. stocks rebound after CoreWeave calms AI slowdown fears
U.S. stocks are opening higher as returning AI enthusiasm overshadows a jump in Treasury yields.
AI enthusiasm has returned after CoreWeave, a neocloud company at the centre of the AI infrastructure buildout, impressed with its Q3 earnings and revenue outlook, helping to calm concerns over an AI slowdown.
This, combined with optimism surrounding the Anthropic IPO next week, where investment banks involved have signalled strong initial demand for the debut, which is expected to be valued at US$1.4 trillion, is helping to support sentiment.
As a result, the Nasdaq is leading the rebound, outperforming its peers on Wall Street.
However, rising Treasury yields could prove to be a headwind for stocks. Following the hotter-than-expected inflation data yesterday and hawkish commentary from Federal Reserve officials, the market has ramped up expectations for a December rate hike. The market is also pricing in a 10% probability of a 50-basis-point hike next month.
This comes after Fed Governor Christopher Waller said before the CPI report that a hotter-than-forecast core CPI reading could see him support an outsized hike.
With a December hike now priced in, the market could be underestimating how much more work the Fed will need to do to tighten monetary policy. The bond market is closed today for the Veterans Day holiday.
Looking ahead, attention will be on further Fed speakers and PPI inflation data tomorrow.
Corporate movers
CoreWeave has jumped 13% after the neocloud company posted Q3 revenue ahead of expectations, together with a smaller-than-expected loss. Top-line revenue came in at $3.66 billion, marking a 168% surge from a year earlier. This was also ahead of the $3.55 billion forecast. CoreWeave also raised its full-year revenue outlook.
Nvidia is set to open 5% higher, recovering some of the sharp losses seen over the previous two sessions after CEO Jensen Huang was reported to have had an affair with an alleged Chinese spy. Nvidia had fallen 10% across Monday and Tuesday.
S&P 500 forecast – technical analysis
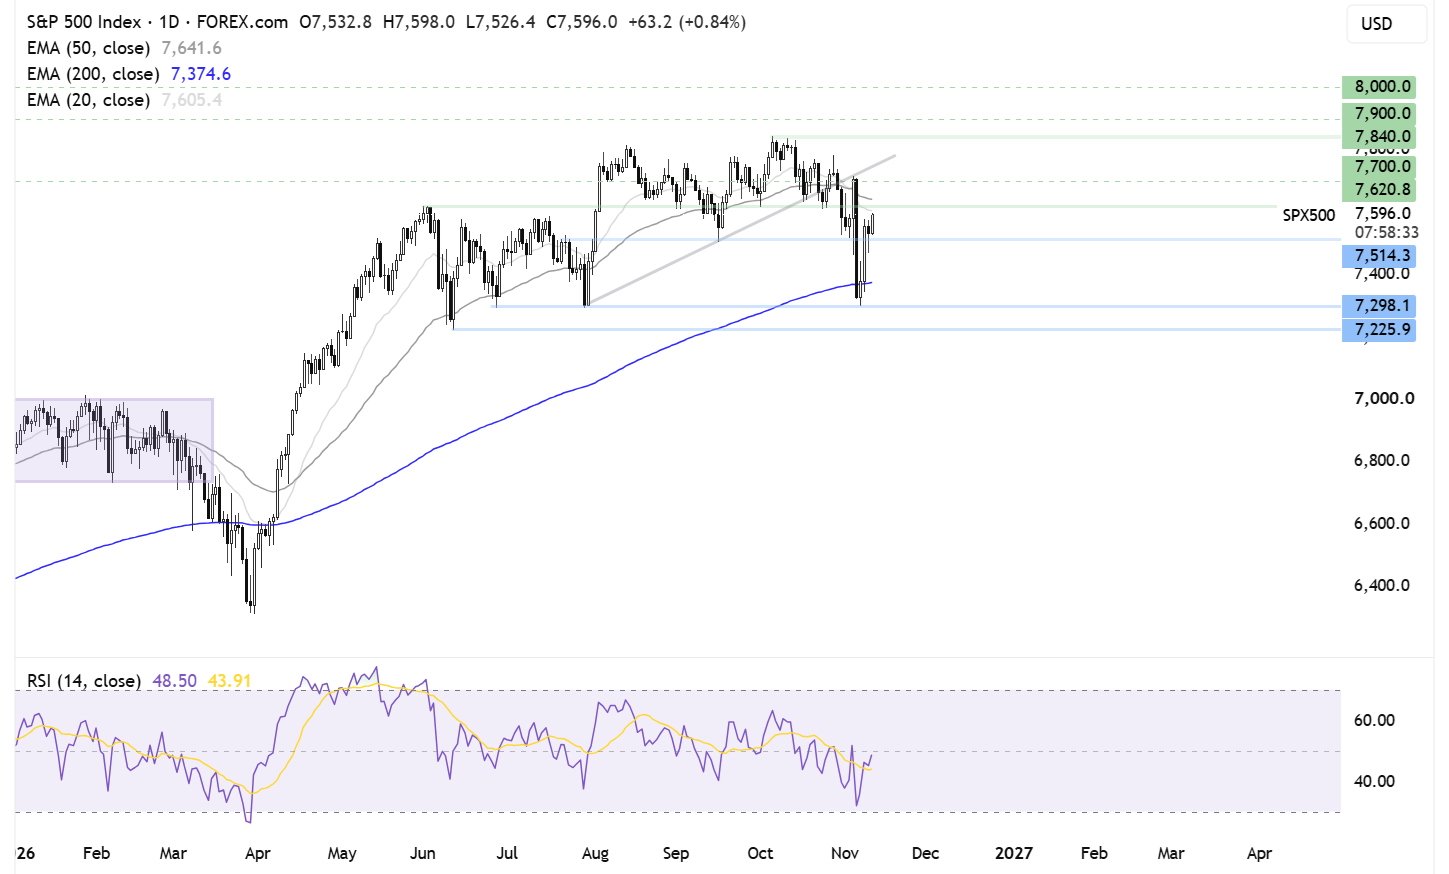
The S&P 500 recovered from the 7,300 low, rising back above the 200 EMA and key support at 7,500. Buyers will look to extend the recovery above resistance at 7,620 and the 50 EMA at 7,645 to put the price on a firmer footing.
A rise above 7,700 opens the door to 7,840 and fresh record highs.
On the downside, immediate support is seen at 7,500, the September low. A break below here exposes the 200 EMA at 7,375, ahead of 7,300, the November low. Sellers would need to take out this level to create a lower low.
FX markets – USD rises, GBP/USD falls
The U.S. dollar has firmed sharply, rising to an almost one-month high after hot inflation and hawkish Fed commentary ramped up rate hike expectations, with the market even pricing in a 10% probability of a 50-basis-point hike in December.
EUR/USD is falling on the stronger U.S. dollar, despite data from Germany showing that inflation cooled to 2.8% year on year in October, down from the nearly three-year high of 3.3% in September, confirming the preliminary reading. This also marked the lowest reading since July. The ECB may hike rates again in December.
GBP/USD is falling towards a weekly low around 1.33 as investors weigh up falling oil prices against the Bank of England's hawkish stance. Policymakers have warned that second-round inflationary effects may require further rate increases. However, falling oil prices could also mean inflationary pressures ease, reducing the need for aggressive hikes.
Oil extends declines on hopes of diplomacy in the Middle East
Oil prices are rising around 1% on Wednesday after dropping to a two-month low yesterday, as the focus remains on U.S.-Iran developments.
Despite today's rise, oil prices have fallen sharply over the past 10 days, with Brent down 22% so far in November and WTI down 17%.
Optimism surrounding a Democrat-led Congress, together with a more conciliatory tone from Trump, has seen the geopolitical risk premium fall away sharply.
That said, there is still no deal on the table, and prices are rising today after Tehran said it would not allow any enriched nuclear materials to leave the country.
Still, output from the Middle East is reportedly at 90% of its February level, just before the U.S.-Iran war began, which could help keep prices subdued.
Latest market news
The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX rebounds amid revived AI enthusiasm
U.S. stocks are opening higher as returning AI enthusiasm overshadows a jump in Treasury yields.
Tankers Still Get Hit but Brent Crude Oil Keeps Falling
Brent crude oil has turned bearish after breaking its uptrend, as de-escalation signals outweigh tanker strikes near the Strait of Hormuz.

DAX Near Record Levels as Earnings Strength Supports Bulls
The DAX remains firmly positioned near record highs after reclaiming the 26,000 level and extending its recovery toward 26,700. Strong earnings momentum, improving industrial activity and renewed confidence in semiconductor and energy-transition stocks continue to support sentiment. With Siemens Energy and Infineon delivering upbeat signals for 2027, investors are increasingly focused on corporate fundamentals rather than macroeconomic uncertainty.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.