



S&P500 Forecast: Stocks jump after a weak NFP report
US stocks are pointing to a stronger open after US non-farm payrolls were weaker than expected. 150K jobs were added in October, below the 180k forecast. September's headline job creation was also revised lower and unemployment ticked higher. The data shows a cooling jobs market in a slowing economy, which supports the view that the Federal Reserve is done with hiking.
Share this:

US futures
Dow futures +0.47% at 34000
S&P futures +0.43% at 4335
Nasdaq futures +0.23% at 14950
In Europe
FTSE -0.07% at 7442
Dax +0.50% at 15224
- NFP saw 150k jobs added vs 180k forecast
- Downward revision to September payrolls & unemployment rose to 3.9%
- Data supports the view that the Fed could be done hiking
- Apple drops amid concerns over current-quarter revenue
NFP saw 130k jobs added vs 150k forecast
U.S. stocks are falling as investors digest the latest U S non-farm payroll report, which was weaker than expected.
The latest jobs report showed that 150k jobs were added in October. This was below the 180k forecast and was the smallest gain in payrolls since June. The weakness in job creation doesn’t look like a one-off given the downward revision in September’s report to 297k from 336k.
Meanwhile, unemployment also ticked higher unexpectedly to 3.9%, up from 3.8%, an almost two-year high. Wage growth came in at 0.2% MoM in October, down from 0.3% in September and missed forecasts of 0.3%.
The data is consistent with a labour market that is cooling and In line with an economy that is starting to slow after the Federal Reserve's aggressive rate hiking cycle.
The data comes after the Federal Reserve kept interest rates on hold in the November meeting at the 22-year high and hinted that the Fed may be done with hiking interest rates. In light of this data, it's clear why Powell adopted a slightly more dovish stance.
In line with expectations that the Federal Reserve is done hiking, treasury yields are extending their declines, and U.S. stock futures are set for positive open.
Meanwhile, gold has pushed back over $2000 on falling yields and on safe-haven flows amid the ongoing Middle Eastern conflict.
Looking ahead ISM services PMIS will come into focus and a weak report could propel stocks and gold higher and the USD lower.
Corporate news
Apple is falling after Q4 earnings, which actually beat market expectations with EPS of $1.46 on revenue over $89.5 billion above the EPS of $1.36 and revenue of $89.31 billion forecast. However, the market is concerned about projections for the current quarter after Apple flagged revenue in its December quarter, which is typically its biggest due to the holiday shopping, which would be in line with last year. However, due to the quarter being a week shorter, that does mean sales are falling by 7%. China was also disappointing as revenue from that key region dropped by 2.5%, fueling concerns over the impact of competition and geopolitical tensions in the region.
Block surged 16% premarket after the payment firm posted better than expected earnings forecast for the coming year and also announced a $1 billion stock buyback plan.
Paramount Global is set to rise over 5% on the open after posting strong revenue and impressive subscription trends in Q3.
S&P500 forecast – technical analysis.
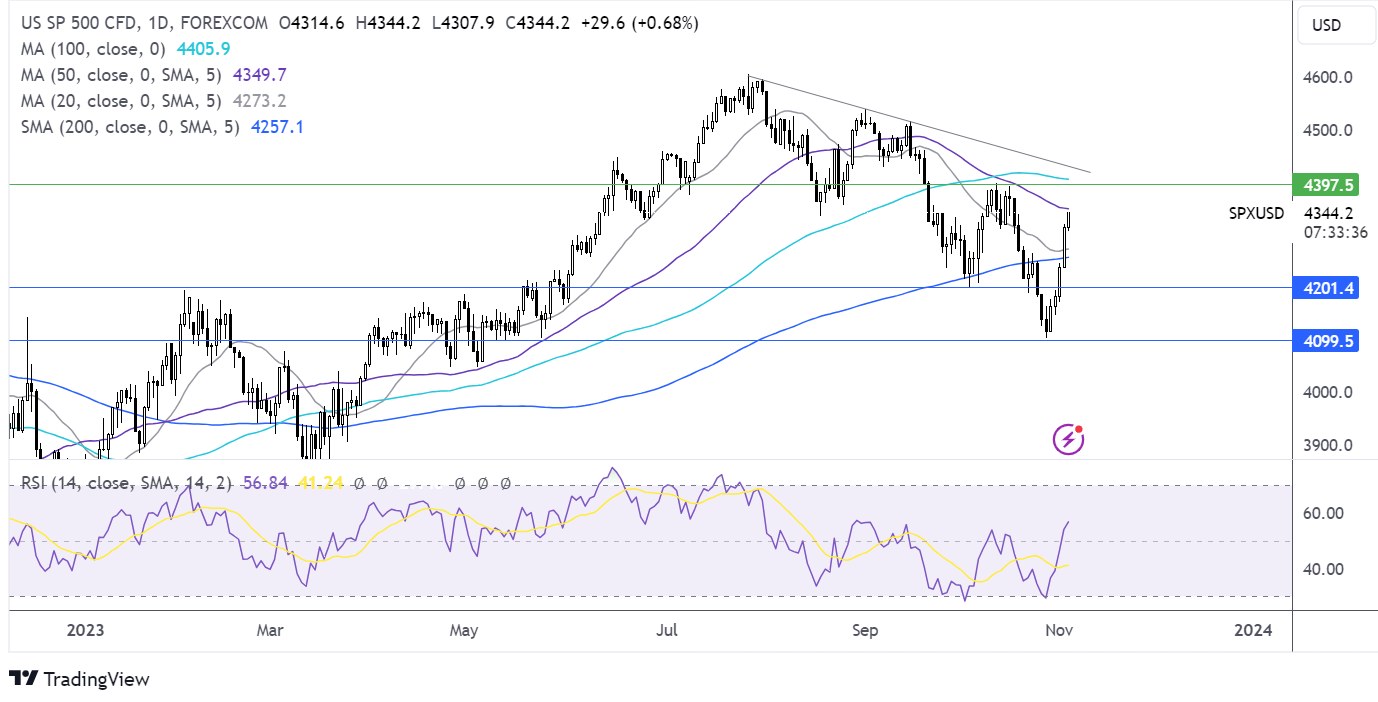
The S&P500 has extended its rebound has extended above the 200 sma to test the 50 sma at 4350. This combined with the RSI above 50 keeps buyers hopeful of further gains. A rise above here opens the door to 4400 the October high. Failure to rise above the 50 sma could see the price fall back to test the 200 sma at 4260.
FX markets –USD falls, EUR rises
The USD falling after the jobs data, which supports the view that the Federal Reserve has finished hiking rates. US treasury yields fall further, pulling USD lower.
EUR/USD is rising, pushing over 1.07 and is on track for a weekly gain. The euro is gaining on a weak USD and finding some support from a larger-than-expected trade surplus of €16.5 billion, ahead of the €16.3 billion forecast but down from €17.7 billion in September. Eurozone unemployment held steady at 6.4%.
GBP/USD is rising above 1.23 on USD weakness and after UK services PMI was upwardly revised to 49.5 from 49.2 in October’s preliminary meeting and up from September’s 49.3. Despite being better than expected the figures still suggest that the UK’s dominant sector acted as a drag on the economy at the start of Q4.
EUR/USD +0.91% at 1.0712
GBP/USD +0.87% at 1.2310
Oil rises but is set for weekly losses
Oil prices are inching higher, adding to yesterday’s gains when they were boosted by improved risk appetite after the Fed and BoE left rates on hold and hinted that they are done hiking.
Oil is set to drop 3% across the week, marking the second straight week of declines as fears of oil supply being impacted by the Middle East conflict eased and amid concerns over the demand outlook in China, the world’s largest oil importer.
China data this week has been broadly weaker than expected, raising doubts over the revival of the Chinese economy. While today’s Chinese services PMI was slightly better than expected, the data also showed that sales grew at the slowest rate in 10 months, and business confidence waned,
Meanwhile, geopolitical concerns remain in focus as the Israel-Hamas conflict continues. The oil market is watching for any escalation of tensions, particularly on the Lebanese border, as Hezbollah attacks increase.
Looking ahead, Baker Hughes rig count which is considered an indicator of future production.
WTI crude trades +1.25% at $81.37
Brent trades +1.3% at $85.60
Looking ahead
13:45 US ISM services PMI
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Forecast: NDX rebounds as oil prices fall and ahead of Apple earnings
U.S. stock indices are moving higher on Monday as tech and AI-related stocks steady following a shocking October. The mood remains cautious following the AI wobble, with more tech earnings due this week, U.S. midterm elections and a full U.S. economic data calendar.

S&P 500 Analysis: Earnings Uncertainty Continues to Weigh on the SPX
The trading week is coming to an end, and a phase of weakness remains evident across the S&P 500 in the short term. Recent price action reflects this dynamic, with SPX losing more than 2.00% over the last two trading sessions, bringing selling pressure back into focus.
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.