




US CPI preview: Are we past peak inflation?
Headline inflation reading may show price pressures fading while the Fed’s preferred “core” (ex-energy and food) CPI measure shows that underlying inflation is still rising
Share this:

When is the July US CPI report?
The US Bureau of Labor Statistics (BLS) will release the July Consumer Price Index (CPI) report Wednesday, August 8 at 8:30 ET.
What are economists expecting for July CPI?
Consensus expectations are for headline CPI to come in at 0.2% m/m, 8.8% y/y, with the Core CPI report expected to print at 0.5% m/m, 6.1% y/y.
Last month’s headline CPI printed at 9.1% y/y, while the Core CPI was 5.9%.
CPI preview
We’ve seen dozens of nails hammered into the proverbial coffin of “team transitory” this year, but perhaps Jerome Powell and company can salvage a small win if inflation drops back below 9% this month.
The biggest factor suggesting that may be the case are gas prices, which have now fallen for over 50 straight days since the start of summer. Analysts estimated that gas prices fell at least 10% in July from June levels, likely subtracting 0.5% or more off the headline CPI reading this month. Likewise, food prices were also substantially lower in July than August, setting up a dynamic where the headline inflation reading may show price pressures fading while the Fed’s preferred “core” (ex-energy and food) CPI measure shows that underlying inflation is still rising as home prices and pent-up demand for economic reopening offset the more volatile components.
Beyond analysis of the individual components of inflation, there are some bigger-picture reasons to expect price pressures to moderate. Recent PMI surveys have indicated that businesses are seeing price pressures abate slightly, and according to the NY Fed, consumer inflation expectations for one year out are falling sharply. From a purely mechanical perspective, inflation was already picking up at this time last year, so the “base effects” from comparing current price increases to last year will make the top-line figures look less dramatic. We estimate that base effects will subtract roughly 0.5% from this month’s inflation forecasts on their own.
US CPI: Where next for the US dollar?
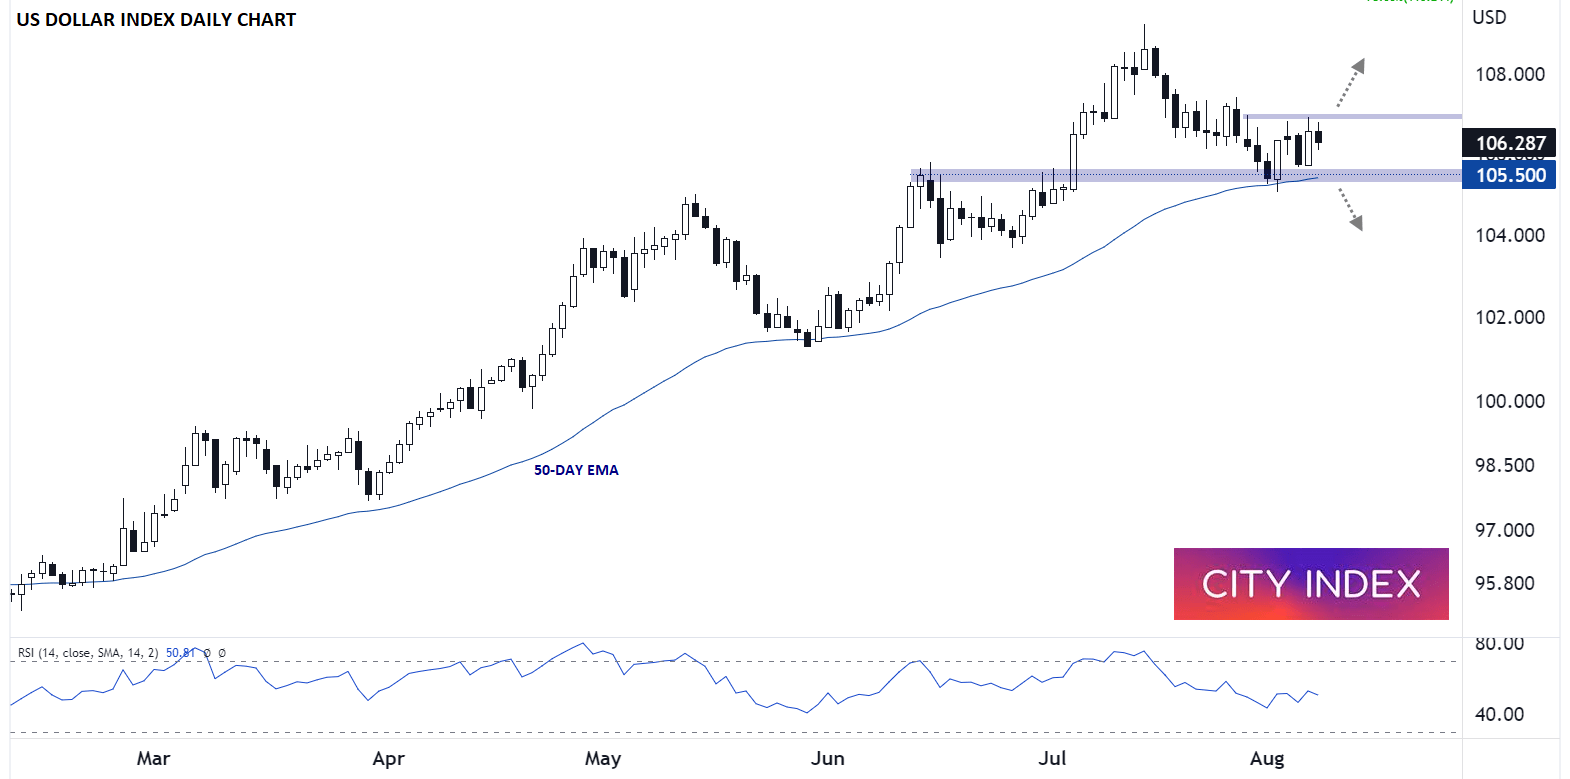
Using the US Dollar Index (DXY) as a proxy, the greenback has been riding its 50-day EMA higher for the past six months. As the chart below shows, the dollar index formed a “bullish engulfing candle” on the daily chart last week; for the uninitiated, this pattern signals a strong shift from selling to buying pressure and is often seen a significant lows in a market:
Source: StoneX, TradingView
If inflation comes in hotter than expected, it would tip the odds in favor of another 75bps interest rate hike from the Fed next month and likely boost the US dollar. A break above the 107.00 handle in that scenario could open the door for a potential retest of the dollar index’s June highs near 109.00. Meanwhile, a soft CPI report could weigh on the buck, with a move below the dollar index’s 50-day EMA near 105.50 suggesting that a deeper pullback toward 104.00 is likely.
When is the July US CPI report?
The US Bureau of Labor Statistics (BLS) will release the July Consumer Price Index (CPI) report Wednesday, August 8 at 8:30 ET.
What are economists expecting for July CPI?
Consensus expectations are for headline CPI to come in at 0.2% m/m, 8.8% y/y, with the Core CPI report expected to print at 0.5% m/m, 6.1% y/y.
Last month’s headline CPI printed at 9.1% y/y, while the Core CPI was 5.9%.
CPI preview
We’ve seen dozens of nails hammered into the proverbial coffin of “team transitory” this year, but perhaps Jerome Powell and company can salvage a small win if inflation drops back below 9% this month.
The biggest factor suggesting that may be the case are gas prices, which have now fallen for over 50 straight days since the start of summer. Analysts estimated that gas prices fell at least 10% in July from June levels, likely subtracting 0.5% or more off the headline CPI reading this month. Likewise, food prices were also substantially lower in July than August, setting up a dynamic where the headline inflation reading may show price pressures fading while the Fed’s preferred “core” (ex-energy and food) CPI measure shows that underlying inflation is still rising as home prices and pent-up demand for economic reopening offset the more volatile components.
Beyond analysis of the individual components of inflation, there are some bigger-picture reasons to expect price pressures to moderate. Recent PMI surveys have indicated that businesses are seeing price pressures abate slightly, and according to the NY Fed, consumer inflation expectations for one year out are falling sharply. From a purely mechanical perspective, inflation was already picking up at this time last year, so the “base effects” from comparing current price increases to last year will make the top-line figures look less dramatic. We estimate that base effects will subtract roughly 0.5% from this month’s inflation forecasts on their own.
US CPI: Where next for the US dollar?
Using the US Dollar Index (DXY) as a proxy, the greenback has been riding its 50-day EMA higher for the past six months. As the chart below shows, the dollar index formed a “bullish engulfing candle” on the daily chart last week; for the uninitiated, this pattern signals a strong shift from selling to buying pressure and is often seen a significant lows in a market:
Source: StoneX, TradingView
If inflation comes in hotter than expected, it would tip the odds in favor of another 75bps interest rate hike from the Fed next month and likely boost the US dollar. A break above the 107.00 handle in that scenario could open the door for a potential retest of the dollar index’s June highs near 109.00. Meanwhile, a soft CPI report could weigh on the buck, with a move below the dollar index’s 50-day EMA near 105.50 suggesting that a deeper pullback toward 104.00 is likely.
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DAX Climbs After Fed Move, Eyes Break Above 26,000 Resistance
The DAX has opened significantly higher following the Federal Reserve's delivery of its first interest rate hike since 2023. Although the Fed signaled further tightening, the market reaction was surprisingly positive, as much of the hawkish expectation had already been priced in. Attention now shifts to the 25,900–26,000 point range, which will likely determine whether the current recovery evolves into a new upward wave or remains merely a short-covering rally.
FOMC Meeting Preview: Three Questions for Chairman Warsh
Assuming the Fed delivers the expected hike, traders will want to know WHAT could prompt another hike, WHY they hiked this time, and HOW to interpret the dot plot.
Crude Oil Price Outlook: WTI and Brent Lead the Market Narrative
Crude Oil Price Outlook: Crude oil remains the market’s dominant narrative despite conflicting headline signals

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.