



US open: Futures mixed after bank earnings, China GDP
US stocks are set to open in a quiet manner after the long weekend and as investors digest the latest banks' earnings and China GDP data.
Share this:

US futures
Dow futures -0.18% at 34196
S&P futures +0.08% at 3993
Nasdaq futures +0.2% at 11517
In Europe
FTSE -0.14% at 7849
Dax -0.08% at 15141
China GDP drops sharply.
US stocks are set to open in a mixed and muted fashion after the long weekend as investors digest more quarterly earnings and a sharp drop in China’s GDP.
Data from China shows that growth in the world's second-largest economy slumped to one of its worst levels in almost 50 years. Q4 GDP grew at 2.9%, down from 3.9% but ahead of forecasts of 1.8%.
Turning to corporate earnings, the banks are once again in focus with results from Goldman Sachs and Morgan Stanley.
S&P500 earnings are expected to fall this earnings season, and revenue rise marginally as companies struggle in a challenging, inflationary environment. A big focus will be on the outlook and the likelihood of a recession.
At the World Economic Forum in Davos, a survey revealed that two-thirds of those questioned expect a global recession in 2023.
Corporate news
Goldman Sachs is falling pre-market after the investment bank missed profit estimates owing to a steep decline in asset and wealth management. GS reported EPS of $3.32, well below the $5.48 forecast. Revenue was $10.59, below the $10.83 expected.
Morgan Stanley is rising after the bank beat forecasts after its trading business was boosted by market volatility which offset the hit from sluggish dealmaking.
Coinbase rises 6.6%, as the crypto exchange benefitted from a 2 week rally in the Bitcoin price.
Where next for the S&P500?
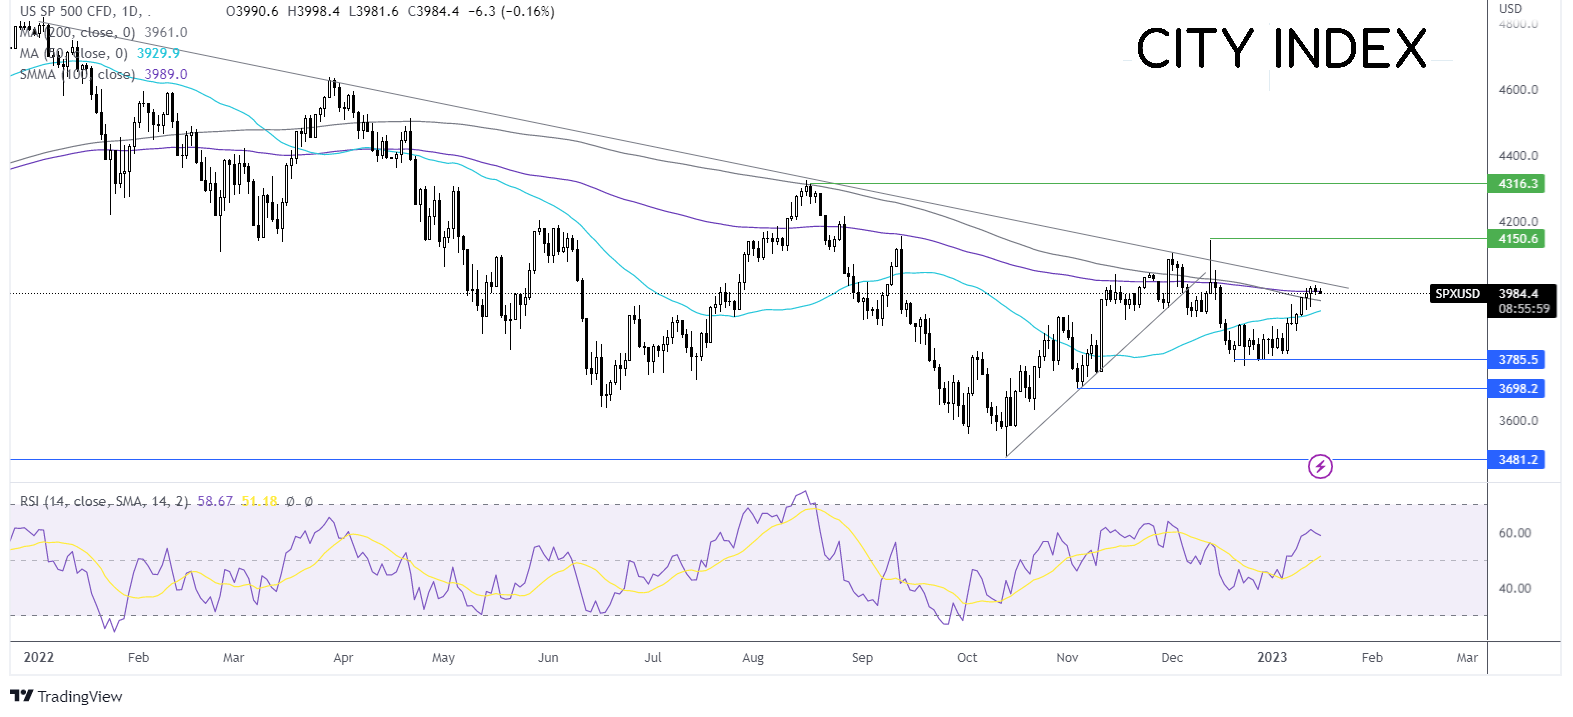
The S&P500 extended its rebound from 3790, the year-to-date low, and pushed higher towards 4000, which is proving to be a tough nut to crack. The index has risen above its 50 sma, which, combined with the bullish RSI keeps buyers optimistic about further gains. Buyers need to rise above 4000, the 100 & 200 sma and the psychological level, to test 4020, the multi-month falling trendline resistance, to extend the bullish run towards 4150, the December high. Failure to rise above 4000 could see the price rebound lower to 3930, the 50 sma ahead of 3790 the 2023 low.
FX markets – USD falls, GBP rises
The USD is falling, giving up earlier gains. The broad trend for the US dollar remains downwards as inflation continues to cool in the USA and the market prices in a less hawkish Federal Reserve.
GBP/USD is rising above 1.2250 and outperforming its peers following stronger-than-expected UK jobs data. while the UK unemployment rate held steady in November, close to record lows at 3.7%, average wages excluding bonuses rose by more than expected to 6.4%, up from 6.1% at a near-record pace, as the labour shortage forces companies to raise pay to retain staff. Higher wages mount pressure on the BoE to hike rates further. There were some signs of the jobs market softening, with vacancies falling by 75000 in December to 1.16 million, the seventh monthly decline.
EUR/USD is rising after stronger-than-expected German economic sentiment, which rebounded firmly in January to 16.9, up from -23.6 and we above forecasts of -15.5. German economic sentiment has turned positive for the first time since the start of the Ukraine war. this suggests that the recession that is expected in the first quarter could be milder than initially feared.
GBP/USD +0.6% at 1.22270
EUR/USD +0.2% at 1.0838
Oil rises despite weak Chinese growth
Oil prices are on the rise after falling around 1% in the previous session. The oil markets are taking the sharp drop in Chinese economic growth in its stride. The rolling back of the zero-Covid measures and the expected economic recovery is overshadowing the data which showed the Chinese economy stagnated in the final quarter of last year.
Recession worries could limit the upside in oil. Expectations of a global recession are on the rise. Slowing global growth would weigh on the oil demand outlook.
Looking ahead, OPEC and the IEA are due to release their monthly supply and demand outlook on Wednesday.
WTI crude trades +1.65% at $80.45
Brent trades at +1.45% at $83.80
Looking ahead
20:00 Fed Williams to speak
US futures
Dow futures -0.18% at 34196
S&P futures +0.08% at 3993
Nasdaq futures +0.2% at 11517
In Europe
FTSE -0.14% at 7849
Dax -0.08% at 15141
Learn more about trading indices
China GDP drops sharply.
US stocks are set to open in a mixed and muted fashion after the long weekend as investors digest more quarterly earnings and a sharp drop in China’s GDP.
Data from China shows that growth in the world's second-largest economy slumped to one of its worst levels in almost 50 years. Q4 GDP grew at 2.9%, down from 3.9% but ahead of forecasts of 1.8%.
Turning to corporate earnings, the banks are once again in focus with results from Goldman Sachs and Morgan Stanley.
S&P500 earnings are expected to fall this earnings season, and revenue rise marginally as companies struggle in a challenging, inflationary environment. A big focus will be on the outlook and the likelihood of a recession.
At the World Economic Forum in Davos, a survey revealed that two-thirds of those questioned expect a global recession in 2023.
Corporate news
Goldman Sachs is falling pre-market after the investment bank missed profit estimates owing to a steep decline in asset and wealth management. GS reported EPS of $3.32, well below the $5.48 forecast. Revenue was $10.59, below the $10.83 expected.
Morgan Stanley is rising after the bank beat forecasts after its trading business was boosted by market volatility which offset the hit from sluggish dealmaking.
Coinbase rises 6.6%, as the crypto exchange benefitted from a 2 week rally in the Bitcoin price.
Where next for the S&P500?
The S&P500 extended its rebound from 3790, the year-to-date low, and pushed higher towards 4000, which is proving to be a tough nut to crack. The index has risen above its 50 sma, which, combined with the bullish RSI keeps buyers optimistic about further gains. Buyers need to rise above 4000, the 100 & 200 sma and the psychological level, to test 4020, the multi-month falling trendline resistance, to extend the bullish run towards 4150, the December high. Failure to rise above 4000 could see the price rebound lower to 3930, the 50 sma ahead of 3790 the 2023 low.
FX markets – USD falls, GBP rises
The USD is falling, giving up earlier gains. The broad trend for the US dollar remains downwards as inflation continues to cool in the USA and the market prices in a less hawkish Federal Reserve.
GBP/USD is rising above 1.2250 and outperforming its peers following stronger-than-expected UK jobs data. while the UK unemployment rate held steady in November, close to record lows at 3.7%, average wages excluding bonuses rose by more than expected to 6.4%, up from 6.1% at a near-record pace, as the labour shortage forces companies to raise pay to retain staff. Higher wages mount pressure on the BoE to hike rates further. There were some signs of the jobs market softening, with vacancies falling by 75000 in December to 1.16 million, the seventh monthly decline.
EUR/USD is rising after stronger-than-expected German economic sentiment, which rebounded firmly in January to 16.9, up from -23.6 and we above forecasts of -15.5. German economic sentiment has turned positive for the first time since the start of the Ukraine war. this suggests that the recession that is expected in the first quarter could be milder than initially feared.
GBP/USD +0.6% at 1.22270
EUR/USD +0.2% at 1.0838
Oil rises despite weak Chinese growth
Oil prices are on the rise after falling around 1% in the previous session. The oil markets are taking the sharp drop in Chinese economic growth in its stride. The rolling back of the zero-Covid measures and the expected economic recovery is overshadowing the data which showed the Chinese economy stagnated in the final quarter of last year.
Recession worries could limit the upside in oil. Expectations of a global recession are on the rise. Slowing global growth would weigh on the oil demand outlook.
Looking ahead, OPEC and the IEA are due to release their monthly supply and demand outlook on Wednesday.
WTI crude trades +1.65% at $80.45
Brent trades at +1.45% at $83.80
Learn more about trading oil here.
Looking ahead
20:00 Fed Williams to speak
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.


S&P 500 Forecast: SPX rises after cooler-than-expected inflation data
U.S. stocks are rising and Treasury yields are falling after data showed that inflation increased at a cooler pace than expected, while U.S. consumer spending rose again in August.
The RBA Hiked Rates and the Australian Dollar Still Fell
AUD/USD fell after the RBA rate hike because the central bank's hawkish stance was already priced in while the U.S. dollar stayed firm.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.