



Market Brief: US Tech Slumps on AI Disruption Fears as DAX Tests Key Support
US equities fell sharply as new AI‑driven disruption fears hit tech, logistics and software. Defensive sectors held up while Treasuries rallied and crude weakened. In Europe, the DAX sits on a major support cluster with momentum cooling and a break of 24,750 watched closely. Trade headlines warmed as the US eased China measures ahead of Trump’s April visit, while APAC markets weakened on tech sentiment. Bitcoin stabilised after dipping below USD 66,000.
Share this:

US Equities
US stocks fell sharply as renewed AI‑disruption concerns hit tech, logistics, software, gaming, and financials, following Algorhythm Holdings’ update that its SemiCab platform enables 300–400% freight‑volume scaling with no additional headcount. Defensive sectors such as consumer staples outperformed. Treasuries rallied in a bull‑flattening move, helped by a strong 30-year auction, while crude followed broader risk sentiment lower. Trump reiterated the need for an Iran deal within a month, warning of severe consequences if no agreement is reached.
SPX -1.55%, NDX -2.04%, DJI -1.34%, RUT -2.15%.
Europe – DAX – Technical Analysis
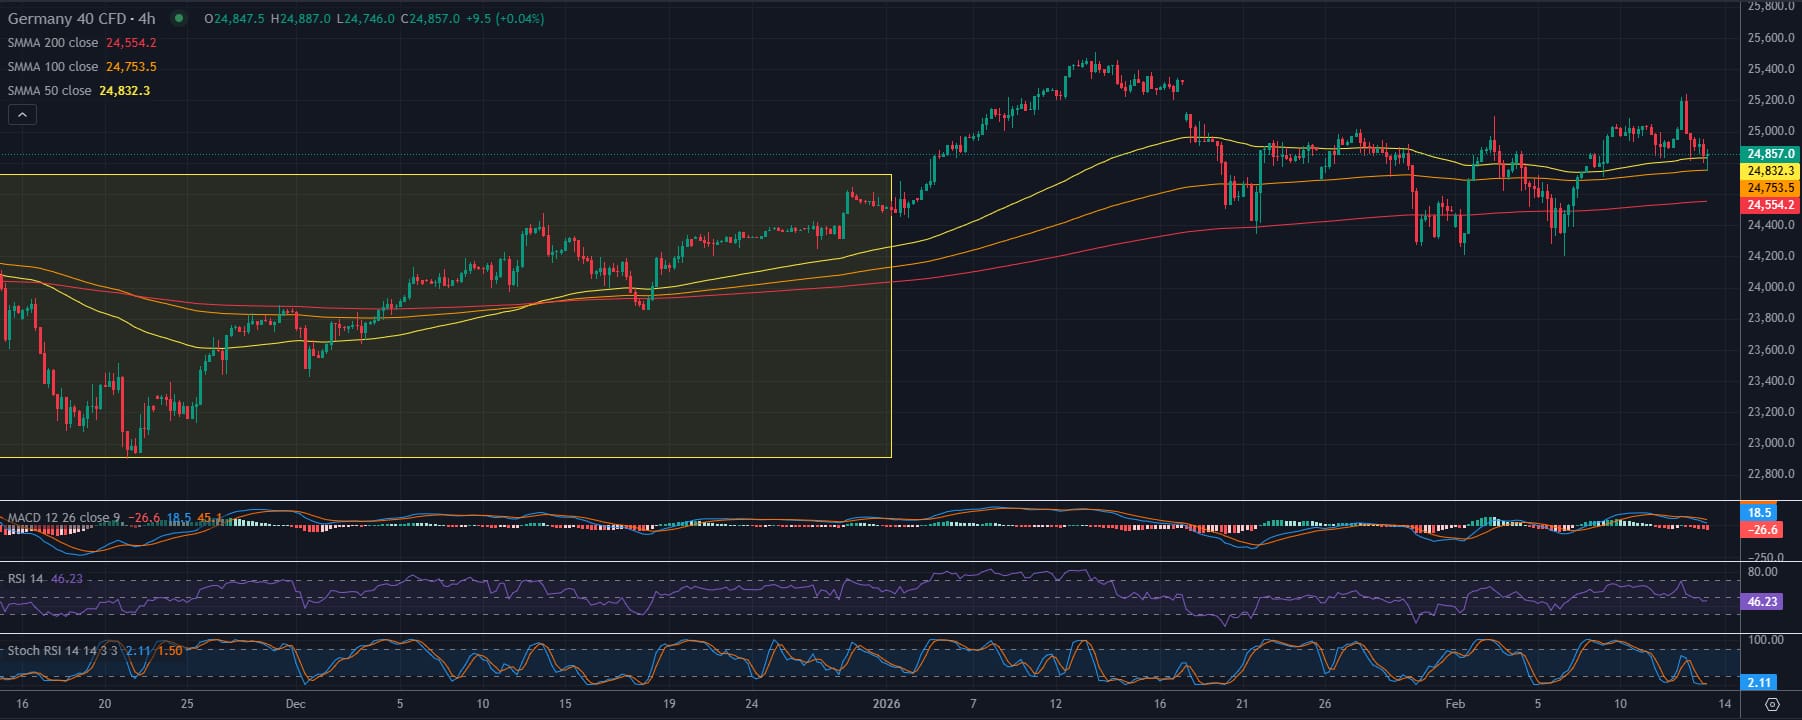
Price has clearly broken out of the long consolidation box you highlighted (roughly mid‑Nov to late‑Dec), followed by a strong impulsive leg into early January. Since then, momentum has cooled, and the index has transitioned into a broad, choppy range. Price is currently sitting right on the cluster of key MAs (50/100/200), suggesting neutral-to-soft short‑term sentiment. The 50‑MA slipping below the 100‑MA is a mild warning signal, and the latest rejection near 25,200 reinforces the idea that upside momentum is weakening.
Indicators support this consolidation bias: MACD is flat around the signal line, RSI is mid‑range (neither overbought nor oversold), and Stochastics show frequent whipsaws typical of range-bound conditions. The key battleground is ~24,750–24,800. A clean break below this zone opens risk toward 24,400/24,300; holding above it keeps a bounce toward 25,100/25,250 in play. If you want, I can mark out precise trade levels or map scenarios on a fresh chart.
Tariffs & Trade
Trump confirmed he will visit China in April, with Xi expected to visit the US later in the year; the White House has paused certain China tech bans ahead of the summit. The administration is reportedly planning to roll back metal and aluminium tariffs due to domestic affordability concerns. The US signed a major reciprocal trade deal with Taiwan removing 99% of tariffs on US goods, while imposing a 15% tariff on Taiwanese imports; a similar framework was agreed with North Macedonia. Taiwan’s President Lai highlighted major economic and strategic benefits. Japan and the US also advanced discussions on a USD 550bn investment fund.
US Headlines
Fed’s Miran noted labour‑market concerns have softened but argued policy may be more restrictive than policymakers assume. The NY Fed announced roughly USD 40bn in reserve management purchases over the next month. Congress adjourned for recess, with DHS funding set to lapse tomorrow night. OpenAI accused DeepSeek of distilling US models and attempting to free‑ride on American AI technology.
APAC Markets
Asian equities traded mostly lower, tracking US weakness, with tech underperforming across the region as AI disruption fears spread. The ASX 200 slipped on tech weakness and earnings digestion. The Nikkei fell amid yen strength and SoftBank’s weaker‑than‑expected Q3 results. Chinese and Hong Kong markets struggled ahead of the Lunar New Year closure despite the pause in US tech‑ban measures. US futures held near Thursday’s lows.
FX
The DXY was directionless after its two-way move Thursday, with attention shifting to upcoming US CPI. EUR/USD and GBP/USD traded narrowly with little fresh data. USD/JPY edged higher amid quiet domestic news flow and limited reaction to BoJ commentary. AUD and NZD were steady amid risk-off sentiment and a modest rebound in metals.
Fixed Income
Treasuries consolidated after a strong rally driven by risk‑off flows, with the curve bull‑flattening. The US 30-year auction was notably strong at 4.750% (2.1bps stop-through). Bunds hovered near YTD highs ahead of German WPI data, while JGBs pulled back from recent peaks.
Commodities
Crude weakened alongside risk assets and after Trump suggested an Iran deal might be reached within a month. The US said Venezuelan production could increase 30–40% in the first year, with Chevron boosting investment. Qatar raised April Al Shaheen prices, and oil flows through the Druzhba pipeline to Slovakia were halted. Gold recovered slightly, while copper saw a limited bounce.
Crypto
Bitcoin edged higher after briefly dipping below USD 66,000.
Asia-Pacific Headlines
BoJ’s Tamura said inflation appears sticky and that the bank could judge its price goal met as early as spring, reiterating that rate hikes will continue if the outlook warrants. PM Takaichi’s adviser suggested a 2024 rate hike is possible, though not in March.
Data Recap
- China House Price Index (Jan): -0.4% m/m, -3.1% y/y
- New Zealand Inflation Expectations (Q1): 1‑yr at 2.6%, 2‑yr at 2.4%
Geopolitics — Middle East
Trump said the US “has to make a deal” with Iran within a month, warning of traumatic consequences otherwise. Israel’s PM Netanyahu said Iran may accept the new terms given past mistakes. The US will send the U.S.S. Gerald R. Ford to the Middle East and will announce a multi‑billion‑dollar Gaza funding plan next week.
EU / UK
UK PM Starmer will call for a multinational defence initiative to reduce rearmament costs. Germany’s Merz reiterated opposition to joint eurobonds.
-Philip Papageorgiou – Markt Analyst
--X ex Twitter: PhilipForexCom



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.


Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.


Dow Jones Forecast: DJIA rises after weaker jobs data
U.S. stocks are rising after weaker-than-expected U.S. jobs data saw markets rein in rate hike expectations.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.