



USD/JPY Outlook: GDP surprise adds to BoJ pressure, but US still calls the shots
Japan’s GDP beat adds weight to BoJ hike bets, but USD/JPY’s fate still hinges on the U.S. economy, with retail sales and import prices now in focus.
Share this:
- Japan Q2 GDP +0.3% q/q, triple expectations
- Trade and consumption drive upside surprise
- BoJ pressure builds, but U.S. data remains key driver
USD/JPY Summary
U.S. Treasury Secretary Scott Bessent’s subtle nudge for the Bank of Japan (BoJ) to get on with rate hikes fits neatly with the message from Japan’s latest GDP report. But if the aim was to knock the dollar lower against the yen, that’s a job more likely to be done in Washington than Tokyo. For all the chatter about BoJ policy, the dominant driver of USD/JPY remains the U.S. economic and policy backdrop, with the next cues likely to come from retail sales and import price data later Friday.
Trade Boosts Japan GDP
Japan’s economy delivered a stronger-than-expected performance in Q2, with real GDP rising 0.3% q/q, triple the pace expected. The upside surprise was driven largely by trade, with net exports contributing 0.3 percentage points to growth as exports jumped 2% despite U.S. tariffs.
Private consumption, which accounts for more than half of economic activity and is therefore an important driver of inflationary pressures, rose 0.2%, double expectations. The BoJ will be encouraged by signs of consumer resilience but will likely want to see further transmission from stronger wages growth into stronger spending before feeling confident that inflation is self-sustaining.
The GDP deflator, a broad measure of economy-wide inflation that captures price changes across all goods and services produced domestically, rose 3% from a year earlier, down three-tenths from Q1.
The combination of firmer growth, resilient trade, and elevated inflation strengthens the case for the BoJ to resume rate hikes before year-end. While that may please Bessent, who unusually suggested this week that Japan’s central bank was behind the curve in fighting inflation, when it comes to the dominant longer-term driver of USD/JPY movement, that remains an almost entirely U.S. story.
But the U.S. Remains Key for USD/JPY
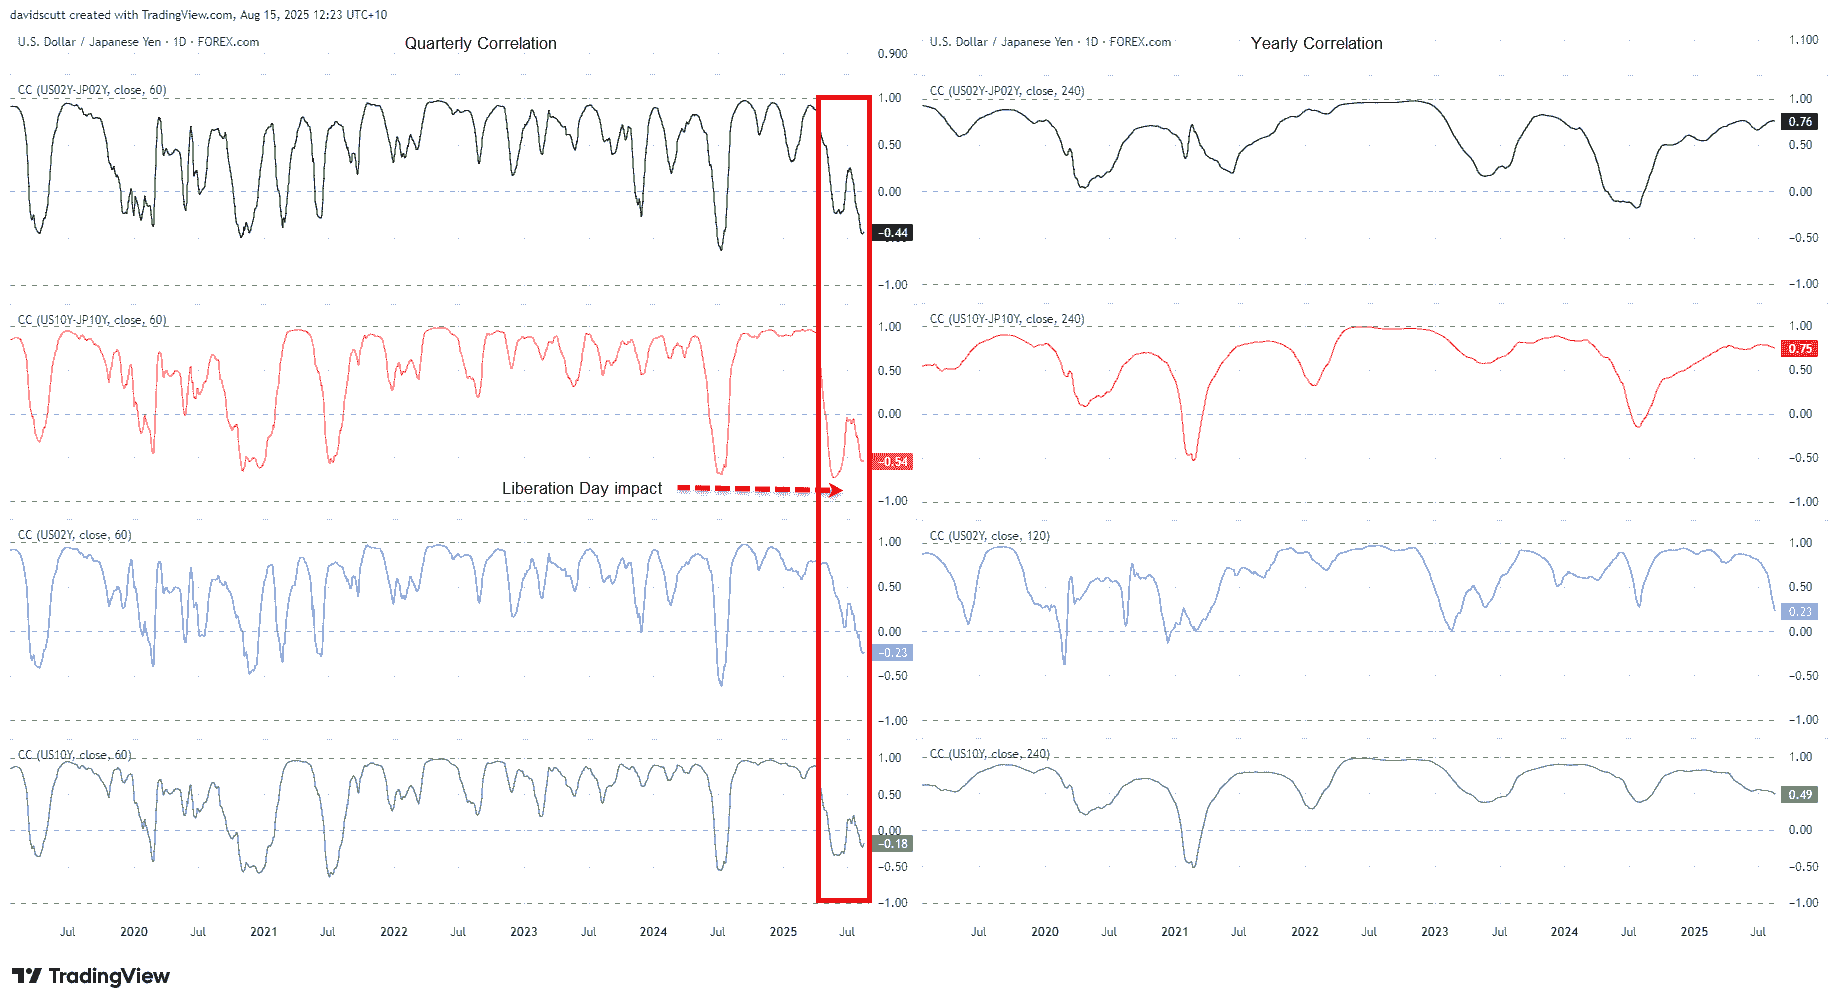
Source: TradingView
You can see that in the correlation analysis below tracking USD/JPY against moves in U.S.–Japanese yield spreads and outright Treasury yields over a rolling quarterly and annual basis. While not uniform over time—as demonstrated earlier this year when USD/JPY fell despite higher U.S. yields and wider spreads following the Liberation Day turbulence—the relationship is often strong to very strong, underlining why it’s U.S. economic data and policy that matter most for USD/JPY traders.
U.S. Retail Sales, Import Prices in Focus
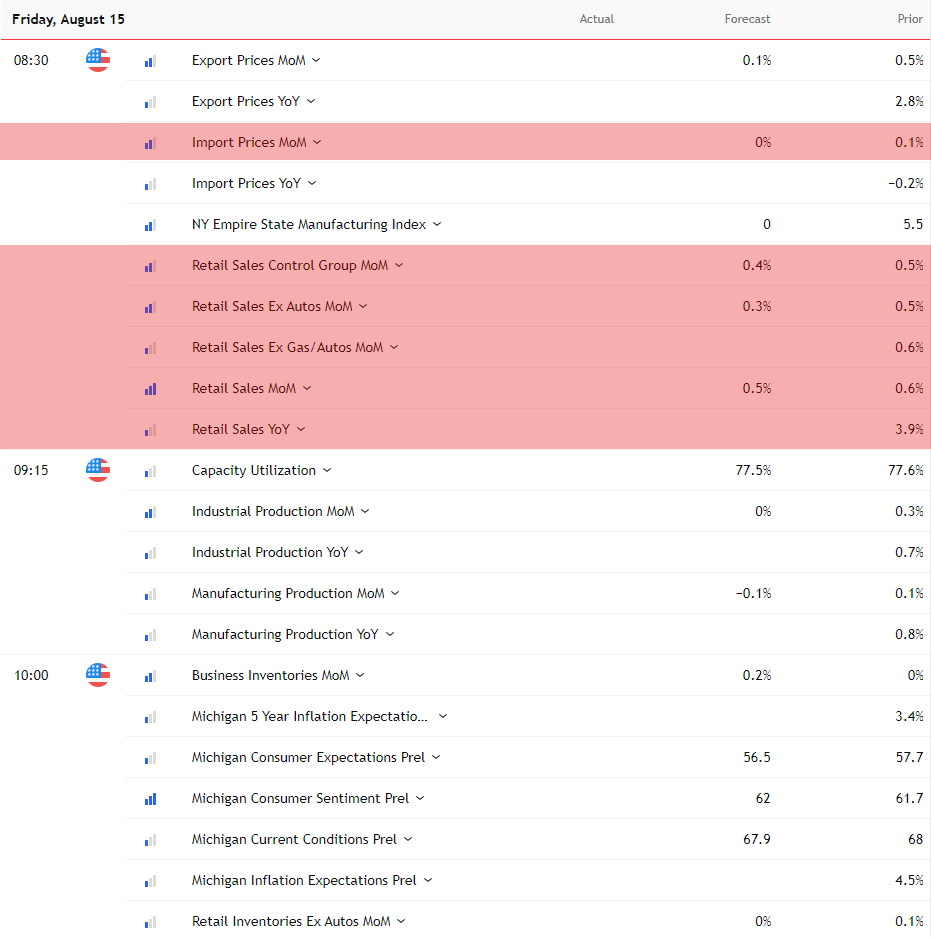
Source: TradingView
With the U.S. CPI and PPI reports out of the way, retail sales and import price data released later Friday are the next risk events set to shake things up for USD/JPY, providing insight on the impact higher tariffs are having on upstream price pressures and consumer behaviour.
After the reversal sparked by Thursday’s hot PPI report, which revealed a pickup in services prices mirroring the detail found in the CPI report, upside surprises in these data prints may see the bullish move in USD/JPY extend further heading into the weekend.
The Trump–Putin summit in Alaska may muddy the price action, but with few expecting significant progress, its influence on hedging activity may be limited.
U.S. Economic Uncertainty Whipsaws USD/JPY
By usual standards, the price action in USD/JPY has been a tad erratic recently, likely reflecting uncertainty as to what exactly is going on in the U.S. economy. Employment growth has slowed sharply, but wages and services inflation remain firm, while there’s little evidence of job shedding. While the Fed is expected to cut rates for the first time this year in September, that could quickly change if it’s proven the July payrolls report was an anomaly rather than the start of a trend, as was the case 12 months earlier.
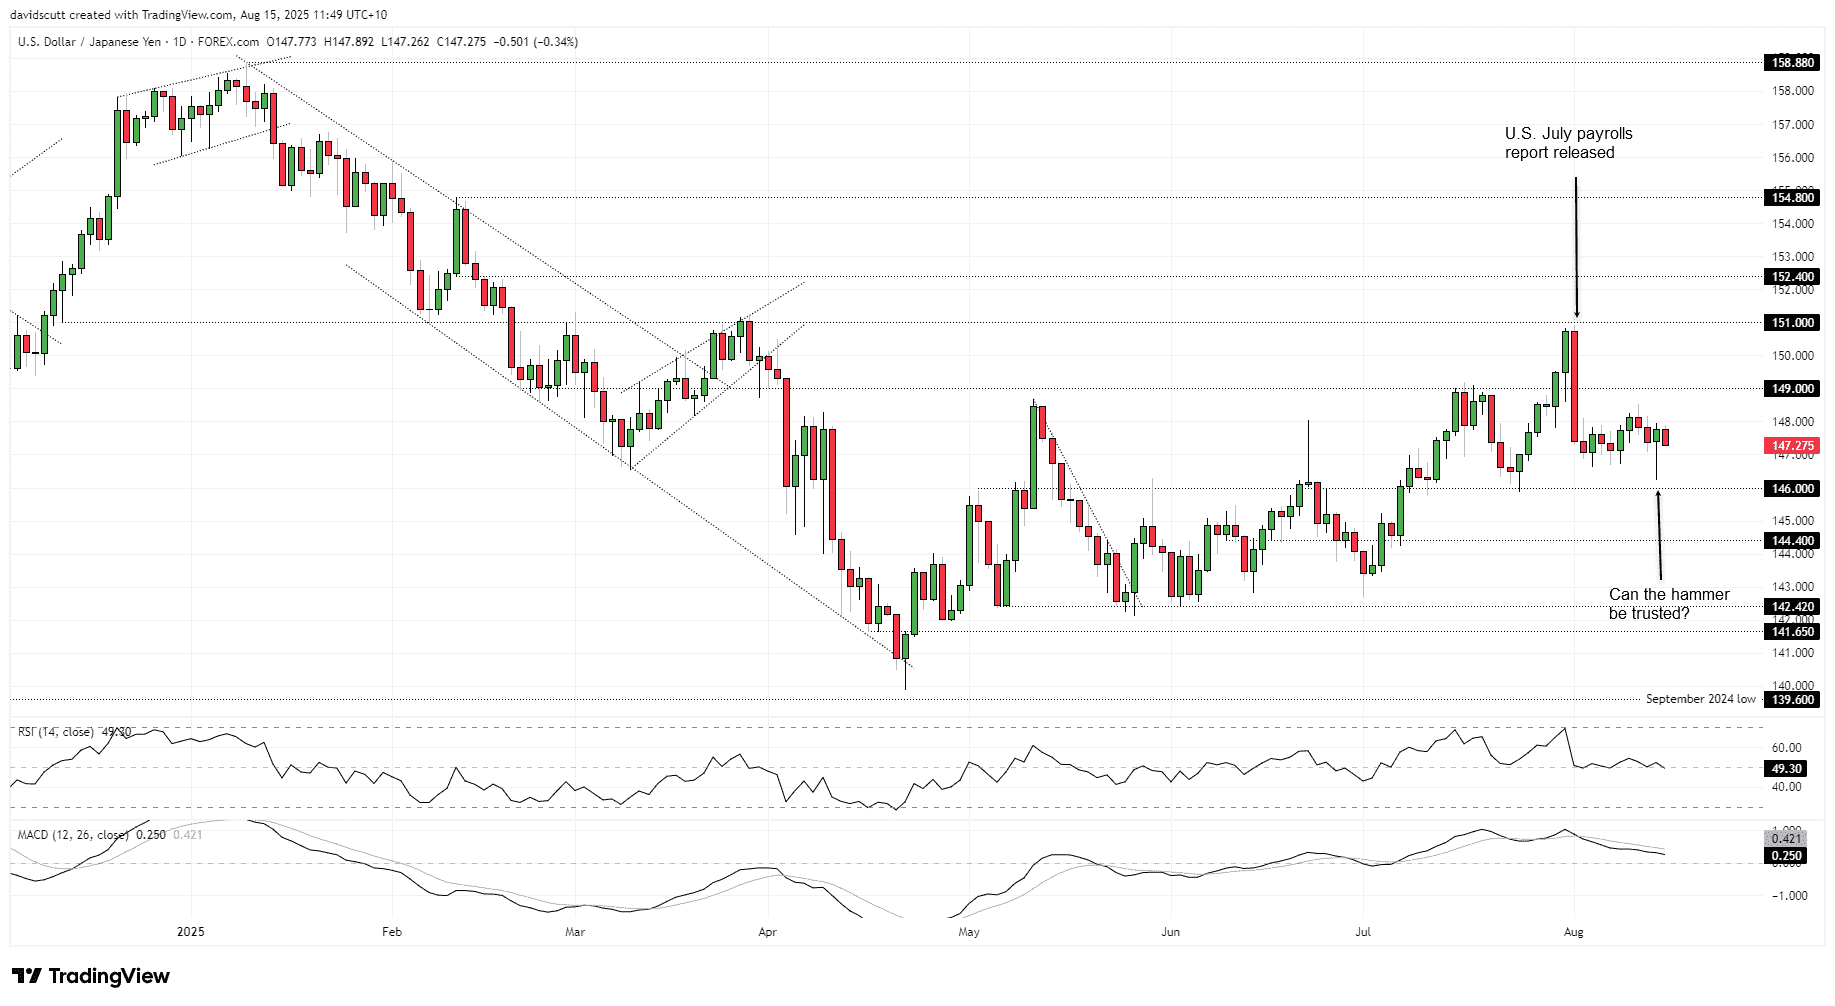
Source: TradingView
The result is that USD/JPY has been choppy within a narrow range since the payrolls report, attracting bids on dips beneath 147.00 with sellers parked above 148.00. Thursday’s hammer candle on the daily chart points to upside risk heading into Friday’s data, but it’s hard to put too much weight on it given recent chop. There’s also no clear signal from momentum indicators, with RSI (14) and MACD flattening out around neutral levels, meaning more emphasis should be put on price action.
Should the range be broken on the data, support is found at 146.00 and 144.40, with resistance located at 149.00 and 151.00.

The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

What Stretched 10-Year Yields Mean for Major Currency Pairs in Q4
U.S. 10-year Treasury yields are nearing a long-term resistance zone with overbought RSI readings, raising near-term pullback risk for the dollar.


USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.

USD/MXN Analysis: Is Super Peso Starting to Fade?
Over recent trading sessions, the Mexican peso has continued to show signs of weakness against the U.S. dollar. This can already be seen in USD/MXN, which has gained more than 1.7% over the last three sessions, highlighting sustained buying pressure in favor of the dollar in the short term.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.