




Vaccine Optimism Reopening Hopes Overshadow US Sino Tensions
. Optimism surrounding easing lockdown measures and a potential vaccine by Novavax provoked risk on trading in Asia which is spilling across into Europe for the open.
Share this:
Whilst escalating US – Sino tensions dominated trading at the end of last week, traders were keen for positive news as they roll back from long weekends in many countries. Optimism surrounding easing lockdown measures and a potential vaccine by Novavax provoked risk on trading in Asia which is spilling across into Europe for the open.
After Moderna’s encouraging vaccine news last week, Novavax, another American company has said it is progressing to human trials in Australia with results expected in July. Given that a vaccine is considered the only way to rapidly return to pre-coronavirus normality any positive vaccine news is well received by traders.
Over the long weekend, Americans were out in force enjoying their newfound freedom, Japan announced billions more in stimulus and indicated that remaining lockdowns in cities were drawing to an end. Singapore also bet expectations with GDP printing at -4.7%, significantly better than the -7.4% forecast.
Boris Johnson clarifies UK reopening path
Here in the UK clarity from Boris Johnson over the timetable for easing lockdown restrictions has boosted sentiment and lifted the Pound. Local street markets and car dealerships can open as from next week whilst all shops will be able to reopen from 15th June if they adhere to the governments social distancing rules.
Whilst the reopening of shops is a huge step forward, the sector still faces huge challenges. Highlighting the struggles of the sector CBI data will be released later today ad is expected to show another record decline to -65, down from -55.
Project Birch
Also propping up sentiment in the UK is Project Birch, a plan authorised by Rishi Sunak to bailout strategically important companies facing acute financial difficulties. This would see the UK government adopt the French and German route of major state investment in private businesses. Following Lufthansa’s bailout by the German government, big names and UK employers such as Jaguar Land Rover be quickly queuing up.
Also propping up sentiment in the UK is Project Birch, a plan authorised by Rishi Sunak to bailout strategically important companies facing acute financial difficulties. This would see the UK government adopt the French and German route of major state investment in private businesses. Following Lufthansa’s bailout by the German government, big names and UK employers such as Jaguar Land Rover be quickly queuing up.
Oil climbs on supply cuts & rising demand
Oil prices climbed in early trade on Tuesday as easing lockdown restrictions sees more cars back on the road boosting demand for fuel. Crucially, at the same time, expectations are firming that producers will stick to agreed production cuts. Russia reported that its production had nearly dropped to its target 8.5 million barrels per day. Quite simply increasing demand coupled with mounting evidence that the supply cuts are coming through is lifting the price of oil.
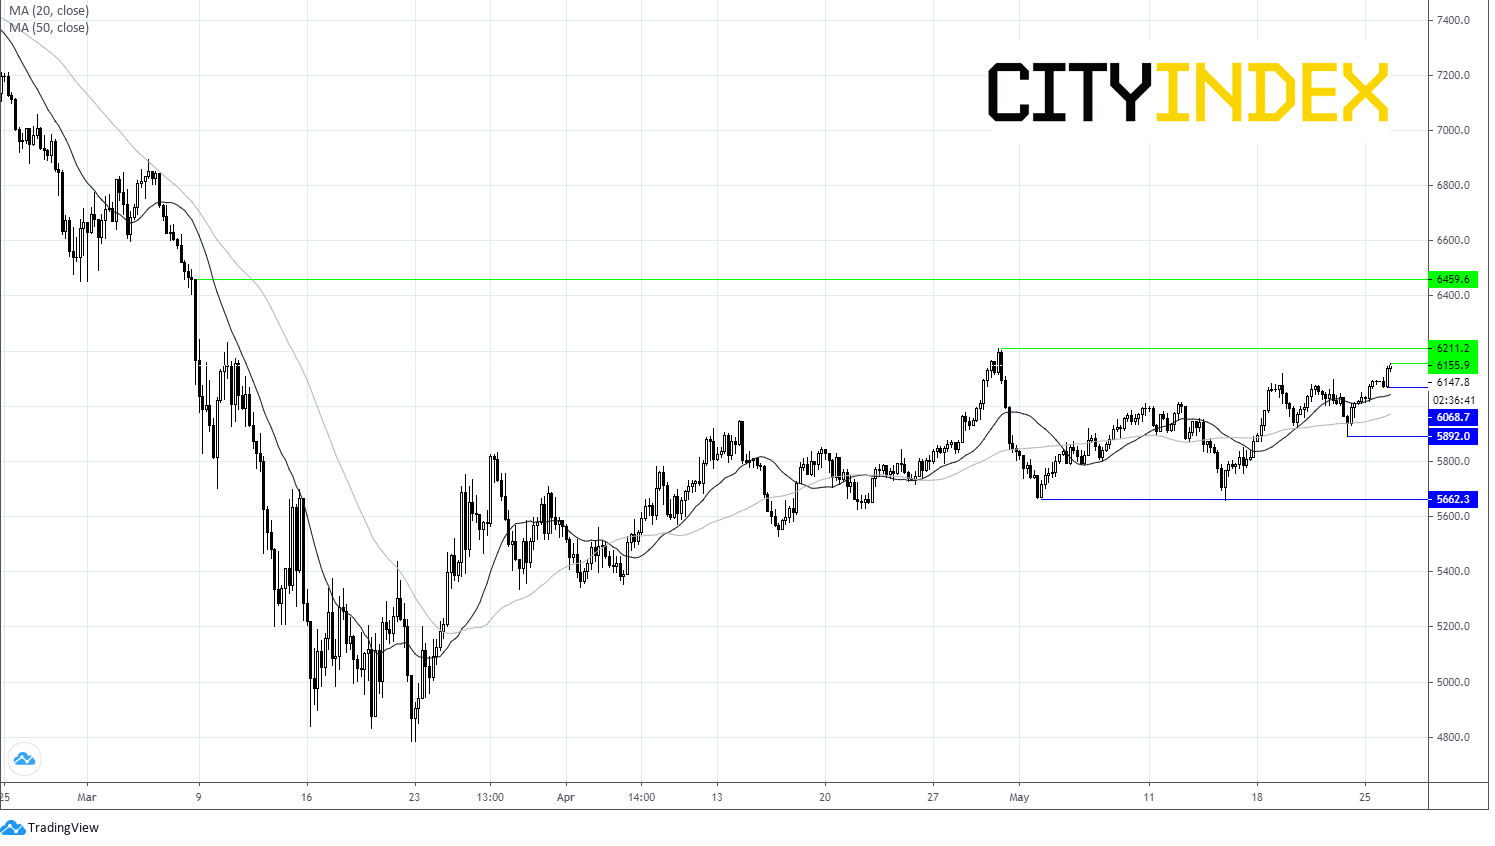
WTI is trading +3% as it looks to target $35. Oil majors on the FTSE could see a jump on the open.
Consumer confidence no strong rebound expected
Looking ahead US consumer confidence will be in focus. Given the US economies dependence on the consumer, morale can help gauge what the recovery will look like. The numbers are expected to be an improvement on April’s plunge to 86.9, however is still expected to make for grim reading. With initial jobless claims indicating that around 25% of the US workforce has signed up for unemployment benefits this is hardly a backdrop for a strong rebound in consumer confidence.
FTSE Chart




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Dow Jones forecast: Stock markets under pressure from multiple sources
When looking at the major tech-heavy US indices like the S&P 500 or the Nasdaq 100, you wouldn’t think that the stock market is particularly weak. Yet, beneath the surface, the market is far from healthy right now. Investors are evidently just piling into the big tech and AI names, and as a result, market breadth is deteriorating. Other indices like the small cap Russell 2000 and the Dow Jones are starting to reflect that weakness.


Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum

S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.