










Weekly COT Report Traders Ditch USD For A 4th Consecutive Week
A summary of the weekly Commitment of Traders Report (COT) from CFTC to show market positioning among large speculators.
Share this:

As of Tuesday 25th June:
- Traders reduced net-long exposure to USD for a 4th consecutive week, shedding -$1.1 billion of long positions to $19.6k billion (23.3k billion against G10 currencies)
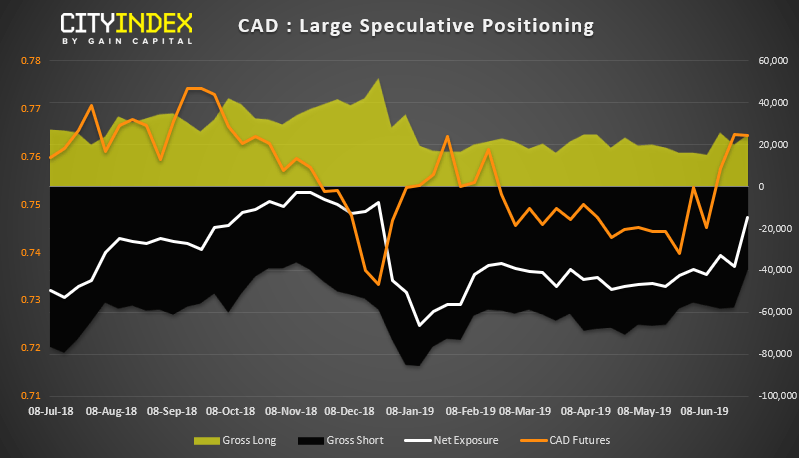
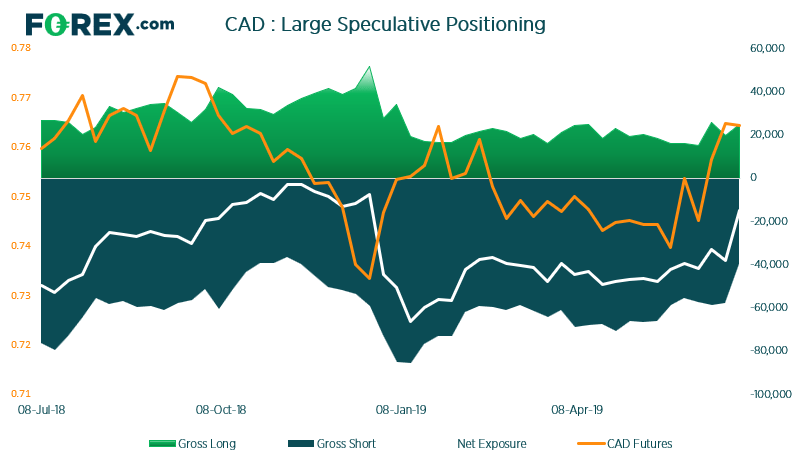
- The Canadian dollar saw the largest weekly change, where net-short exposure was reduced by -23.3k contracts
- Bearish exposure on Japanese yen futures is at its least bearish level since June 2018
- Bearish exposure on Canadian dollar futures is at its least bearish level since December 2018
CAD: With net-short exposure being reduced by -23.3k contracts, it’s the largest weekly change this year. However, whilst bears are clearly less confident in further CAD downside, bullish positions are yet to pick up, making the change in sentiment less bullish than otherwise it first appears. However, that hasn’t stopped CAD from being the best performing major this year so far.
JPY: Traders are now their least bearish on the Japanese yen since June 2018, as risk-off sentiment has seen bears close short contracts for 9 consecutive weeks. However, over that same period, only 3k long contracts have been added so, like CAD, doesn’t make for a compelling bullish argument from large speculators. This makes JPY a prime candidate for bears if/when geopolitical tensions subside.
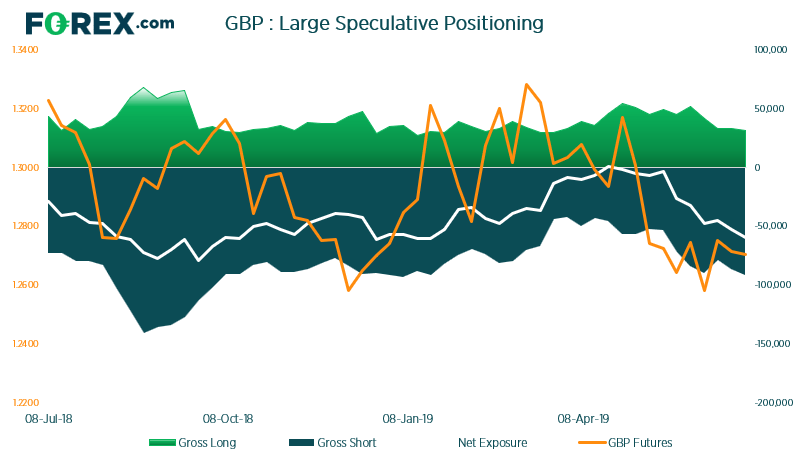
GBP: Large speculators are their most bearish on cable since mid-January. Moreover, open interest (volume) has increased notably since hitting multi-year lows in May, showing an appetite to be bearish on GBP as opposed to de-risking.
As of Tuesday 25th June:
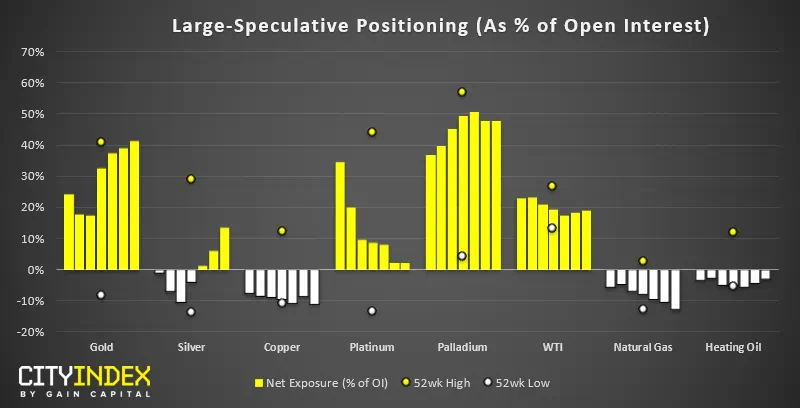
- 82.9% of large speculators are bullish on gold, making it the highest long to short ratio since September 2016
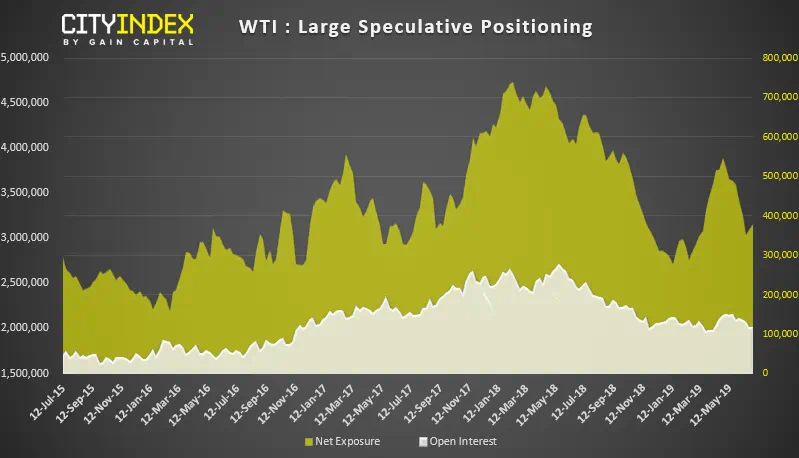
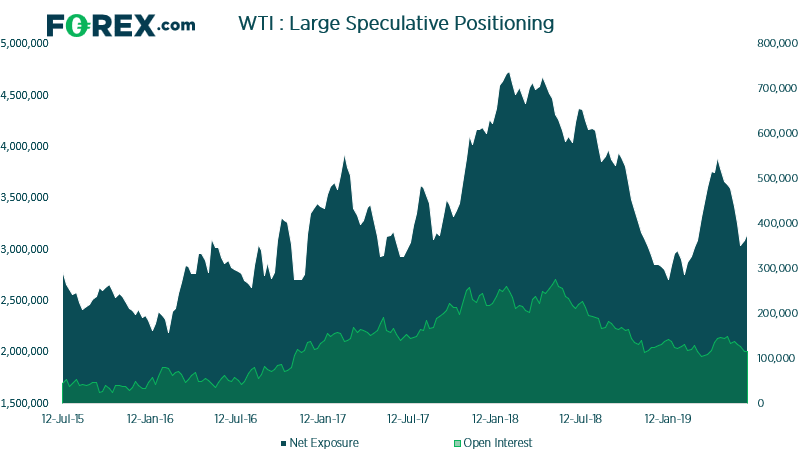
- WTI bulls reduced gross long positions for a 9th consecutive week, yet net-long exposure has increased as shorts were covered at a faster pace
- Traders are net-long on Silver for a 3rd consecutive week, and at their most bullish level since early March
Gold: Whichever way you look at it, gold has been overwhelmingly bullish. However, too much of anything isn’t always a good thing, so we’re cautious in the yellow metal whilst we wait for prices to pause for breath below $1,400. Still, the underlying dynamics are what we like to see for a strong move; bears are closing out and bulls are loading up. So we remain bullish on gold, but would prefer to see prices stabilise and form a new level of support first.
WTI: Volumes have mostly been in decline whilst prices have fallen, to show that traders have been de-risking on crude oil as opposed to becoming outright bearish. Net-long exposure has ticked higher for a 2nd consecutive week, although once again both longs and shorts have reduced exposure. Until we see a firm commitment for the bull or bear camp, it’s difficult to have confidence in a directional move. But, for now the message is clear, traders are wary on WTI.
As of Tuesday 25th June:
- Traders reduced net-long exposure to USD for a 4th consecutive week, shedding -$1.1 billion of long positions to $19.6k billion (23.3k billion against G10 currencies)
- The Canadian dollar saw the largest weekly change, where net-short exposure was reduced by -23.3k contracts
- Bearish exposure on Japanese yen futures is at its least bearish level since June 2018
- Bearish exposure on Canadian dollar futures is at its least bearish level since December 2018
CAD: With net-short exposure being reduced by -23.3k contracts, it’s the largest weekly change this year. However, whilst bears are clearly less confident in further CAD downside, bullish positions are yet to pick up, making the change in sentiment less bullish than otherwise it first appears. However, that hasn’t stopped CAD from being the best performing major this year so far.
JPY: Traders are now their least bearish on the Japanese yen since June 2018, as risk-off sentiment has seen bears close short contracts for 9 consecutive weeks. However, over that same period, only 3k long contracts have been added so, like CAD, doesn’t make for a compelling bullish argument from large speculators. This makes JPY a prime candidate for bears if/when geopolitical tensions subside.
GBP: Large speculators are their most bearish on cable since mid-January. Moreover, open interest (volume) has increased notably since hitting multi-year lows in May, showing an appetite to be bearish on GBP as opposed to de-risking.
As of Tuesday 25th June:
- 82.9% of large speculators are bullish on gold, making it the highest long to short ratio since September 2016
- WTI bulls reduced gross long positions for a 9th consecutive week, yet net-long exposure has increased as shorts were covered at a faster pace
- Traders are net-long on Silver for a 3rd consecutive week, and at their most bullish level since early March
Gold: Whichever way you look at it, gold has been overwhelmingly bullish. However, too much of anything isn’t always a good thing, so we’re cautious in the yellow metal whilst we wait for prices to pause for breath below $1,400. Still, the underlying dynamics are what we like to see for a strong move; bears are closing out and bulls are loading up. So we remain bullish on gold, but would prefer to see prices stabilise and form a new level of support first.
WTI: Volumes have mostly been in decline whilst prices have fallen, to show that traders have been de-risking on crude oil as opposed to becoming outright bearish. Net-long exposure has ticked higher for a 2nd consecutive week, although once again both longs and shorts have reduced exposure. Until we see a firm commitment for the bull or bear camp, it’s difficult to have confidence in a directional move. But, for now the message is clear, traders are wary on WTI.



The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

AUD/USD hammered by US yields and fading RBA hike bets
US yields, dollar strength and fading RBA hike bets have combined to drive AUD/USD to fresh multi-month lows. The macro and technical bias remains bearish, although history suggests parts of the move are now reaching unusually stretched levels.


Gold Price Outlook: XAU/USD Resistance at $4200 Sets Up for NFP
It was a strong sell-off to start the week in gold and despite a Tuesday bounce, sellers are continuing to push following a resistance hit at the $4200 level.


EUR/USD Forecast: Euro Struggles to Find Support Even After U.S. PCE Data
The euro continues to face a challenging environment in the short term. The currency has struggled to regain ground against a U.S. dollar that remains firmly supported, a dynamic reflected in EUR/USD, which has now recorded three consecutive losing sessions and a decline of roughly 0.6%.

StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.