



WTI falls as demand concerns intensify
Oil investors' focus is turning back to the demand side of things and in particular China...
Share this:

Crude oil prices are lower for the second consecutive week, with WTI around 2% lower and Brent some 1.5% worse off on the session. Tuesday’s spike higher in reaction to news of that explosion in eastern Poland, after a sharp 4% drop the day before, has been undone. In other words, the extra geopolitical premium that was built yesterday in oil prices have now been removed. The focus is turning back to the demand side of things and in particular China, where rising covid cases are starting to unnerve investors, and which was part of the reason why oil prices saw a big drop on Monday. But China is not alone. Soaring inflation in the UK and Eurozone and elsewhere around the world are also hurting demand.
With inflation rising across the world, and oil prices remaining elevated compared to levels we saw in 2020 and 2021, demand for oil is expected to remain weak. The International Energy Agency reckons demand growth will slow to 1.6 million barrels per day (bpd) in 2023 from 2.1 million bpd this year. Likewise, the OPEC cut its forecast for 2022 global oil demand growth for a fifth time since April. It now sees global oil demand growth at 2.5 million bpd in 2022 after slashing the fourth-quarter demand projections by nearly 400,000 bpd.
Economic challenges are mounting. So, for oil prices to find any meaningful support it will have to come from production cuts. As a reminder, the OPEC and non-OPEC allies decided in October to reduce production by 2 million barrels per day from November. This has yet to provide any meaningful support to prices. But had they not imposed such deep production cuts, oil prices will have likely been much lower.
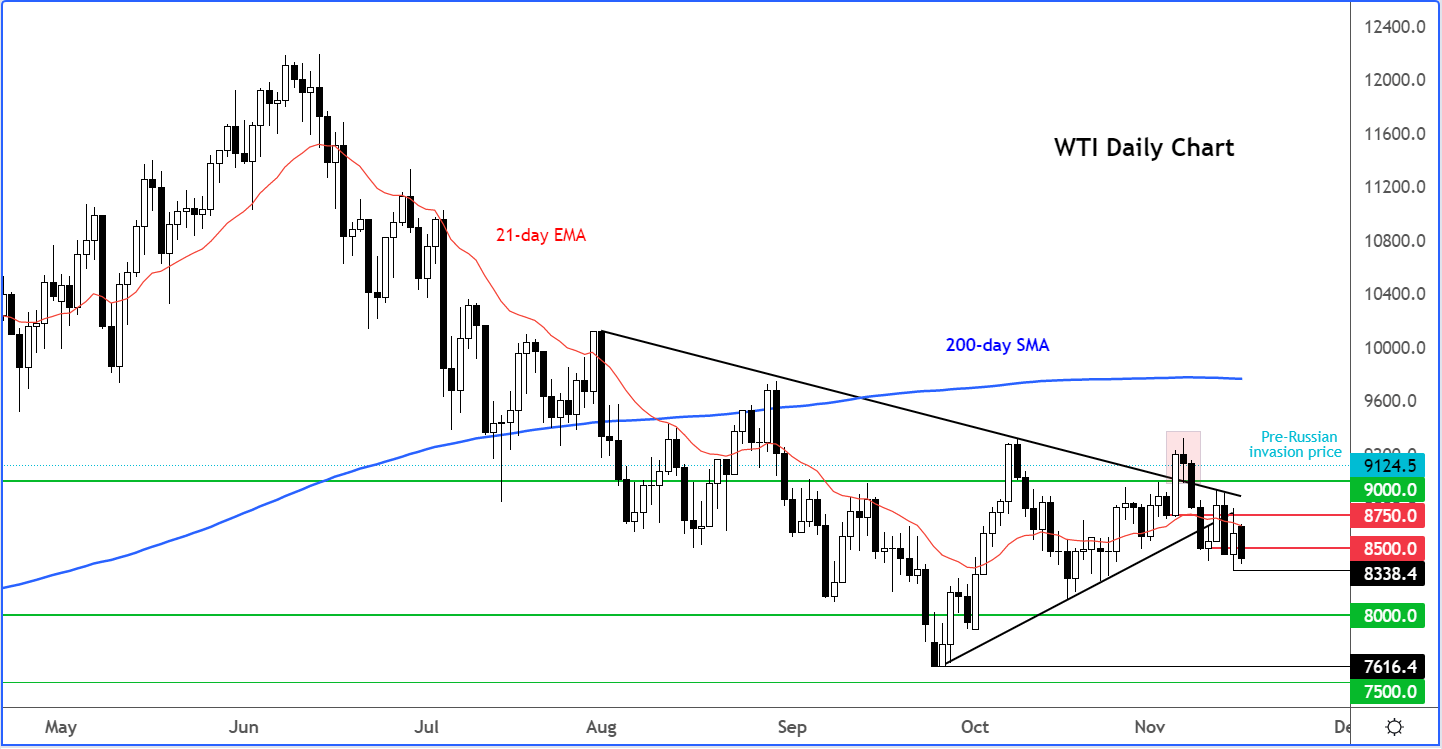
Still, if China imposes new covid restrictions and thereby hamper demand, prices will likely fall further in the coming weeks. WTI is at risk of falling to $80, especially now that it has broken out of its triangle pattern to the downside:
In terms of the immediate focus, attention will turn to the EIA stockpiles data expected at 15:30 GMT (10:30 ET). After last previous bigger-than-expected drawdown, expectations are that supplies fell last week by around 2 million barrels. But according to the American Petroleum Institute (API) figures, they fell by 5.8 million barrels. Not that this provided any support to prices today. Let’s see what the official data reveals.
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:
Latest market news




The complete CFD trading experience
Award-winning platforms, competitive spreads, low commissions and dedicated support.
We live and breathe the markets and are dedicated to helping traders realise their ambitions as we continue to set the industry bar.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.
Gold outlook: XAU/USD hammered, stretched and vulnerable to a sharp rebound
Gold is getting hammered for solid fundamental reasons, but history suggests extreme four-hourly oversold conditions can produce violent countertrend rallies.
EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention
StoneX Europe Ltd may make third party material available on this website which may contain information included but not limited to the conditions of financial markets. The material is for information purposes only and does not contain, and should not be construed as containing, investment advice and/or investment recommendation and/or an investment research and/or an offer of or solicitation for any transactions in financial instruments; any decision to enter into a specific transaction shall be made by the client following an assessment by him/her of their situation.
StoneX Europe Ltd makes no representation or warranty and assumes no liability as to the accuracy or completeness of the information provided, nor any loss arising from any investment based on a recommendation, forecast or other information supplied. You should always seek independent advice as to your suitability to speculate in any related markets and your ability to assume the associated risks, if you are at all unsure. We are not under any obligation to update any such material. Any opinion made may be personal to the author and may not reflect the opinion of StoneX Europe Ltd.