



Antipodean double header next test for AUDNZD
With the dust still settling on last night’s red-hot U.S inflation data, attention locally will turn to an Antipodean doubleheader tomorrow in the shape of Q2 NZ GDP and the Australian August labour force report.
Share this:
With the dust still settling on last night’s red-hot U.S inflation data, attention locally will turn to an Antipodean doubleheader tomorrow in the shape of Q2 NZ GDP and the Australian August labour force report.
While neither of the data points is likely to cause the magnitude of reaction seen today, both have a role to play in the narrative around the speed of policy tightening by the RBNZ and RBA.
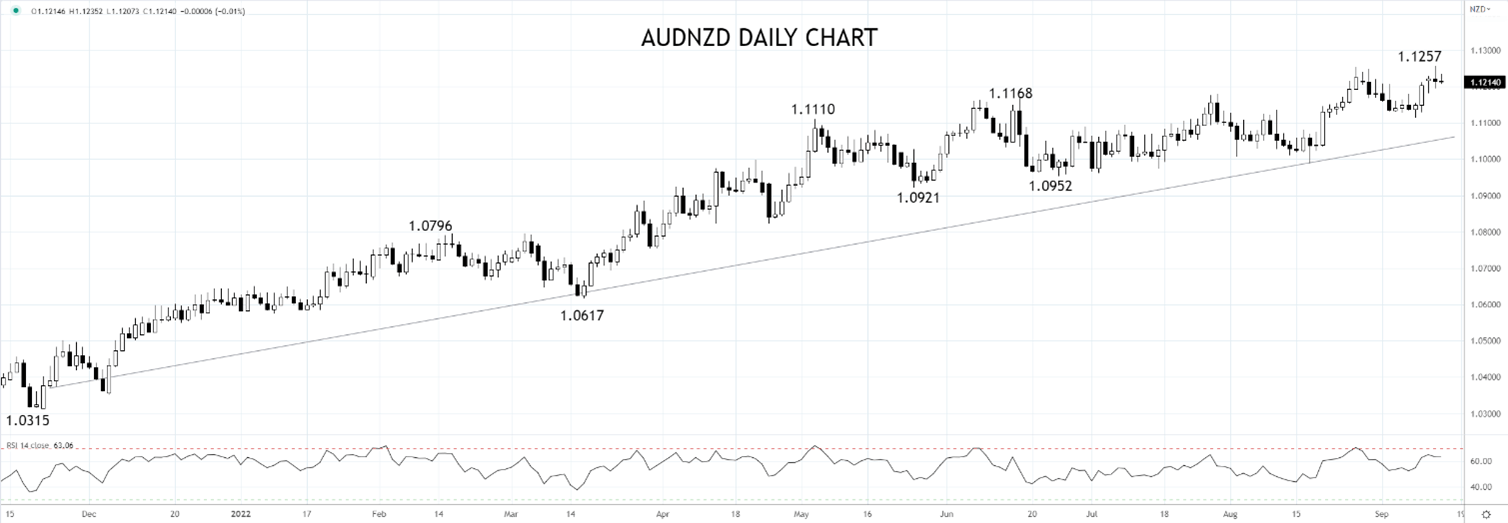
As well as having a say on whether AUDNZD currently trading at almost five-year highs can continue higher.
Q2 New Zealand GDP data is due to drop at 8.45 am Sydney time. Following a 0.2% contraction in Q1 as Omicron ripped through the country, the reopening of international borders that has seen the resumption of overseas tourists and students is expected to see a 1.6% rise in Q2.
Despite the rapid cooling in the housing market, high inflation is expected to see the RBNZ continue to hike rates from 3% to 3.75% by November.
The Australian labour force report for August, due at 11.30 am Sydney time tomorrow, is expected to see a 50k rise in employment and for the unemployment rate to hold at a record low of 3.4%, and the participation rate to rise to 66.7%.
The strong jobs market was likely behind a lift in consumer confidence yesterday and supported by lower petrol prices and the shock value of aggressive RBA rate hikes wearing off.
In this case, there is no reason for the RBA not to continue tightening further into the restrictive territory into yearend to tame spiralling inflation and to cool a tight labour market. The market sees the cash rate ending the year near 3.35%.
Turning to the cross rate, AUDNZD is currently eyeing the 1.1290 high of 2017, supported by buoyant energy and commodity prices, which have kept Australia’s Terms of Trade at record highs despite the slow down in China.
While the rally does look a little overbought in the short term, should AUDNZD see a sustained break of 1.1290, look for the rally to extend towards the August 2015 1.1472 high.
Source Tradingview. The figures stated are as of September 14th, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
With the dust still settling on last night’s red-hot U.S inflation data, attention locally will turn to an Antipodean doubleheader tomorrow in the shape of Q2 NZ GDP and the Australian August labour force report.
While neither of the data points is likely to cause the magnitude of reaction seen today, both have a role to play in the narrative around the speed of policy tightening by the RBNZ and RBA.
As well as having a say on whether AUDNZD currently trading at almost five-year highs can continue higher.
Q2 New Zealand GDP data is due to drop at 8.45 am Sydney time. Following a 0.2% contraction in Q1 as Omicron ripped through the country, the reopening of international borders that has seen the resumption of overseas tourists and students is expected to see a 1.6% rise in Q2.
Despite the rapid cooling in the housing market, high inflation is expected to see the RBNZ continue to hike rates from 3% to 3.75% by November.
The Australian labour force report for August, due at 11.30 am Sydney time tomorrow, is expected to see a 50k rise in employment and for the unemployment rate to hold at a record low of 3.4%, and the participation rate to rise to 66.7%.
The strong jobs market was likely behind a lift in consumer confidence yesterday and supported by lower petrol prices and the shock value of aggressive RBA rate hikes wearing off.
In this case, there is no reason for the RBA not to continue tightening further into the restrictive territory into yearend to tame spiralling inflation and to cool a tight labour market. The market sees the cash rate ending the year near 3.35%.
Turning to the cross rate, AUDNZD is currently eyeing the 1.1290 high of 2017, supported by buoyant energy and commodity prices, which have kept Australia’s Terms of Trade at record highs despite the slow down in China.
While the rally does look a little overbought in the short term, should AUDNZD see a sustained break of 1.1290, look for the rally to extend towards the August 2015 1.1472 high.
Related tags:

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Japanese Yen Forecast: USD/JPY 4% Rally Challenges Post-Intervention Downtrend 9 24 2026
USD/JPY momentum has shifted sharply higher, putting a major resistance confluence in focus as U.S. and Japanese event risk builds.

Oil Quietly Hands the Fed a Reason to Stay Hawkish
Oil prices and the U.S. dollar are both on the front foot as elevated energy costs feed Fed warnings that inflation may prove sticky.


S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.