



Asia Morning US Stocks Lower on Downbeat Data
On Thursday U.S. stocks pared a part of gains made in the prior session. Market sentiment was dampened by a series of downbeat economic data...
Share this:

On Thursday U.S. stocks pared a part of gains made in the prior session. Market sentiment was dampened by a series of downbeat economic data.
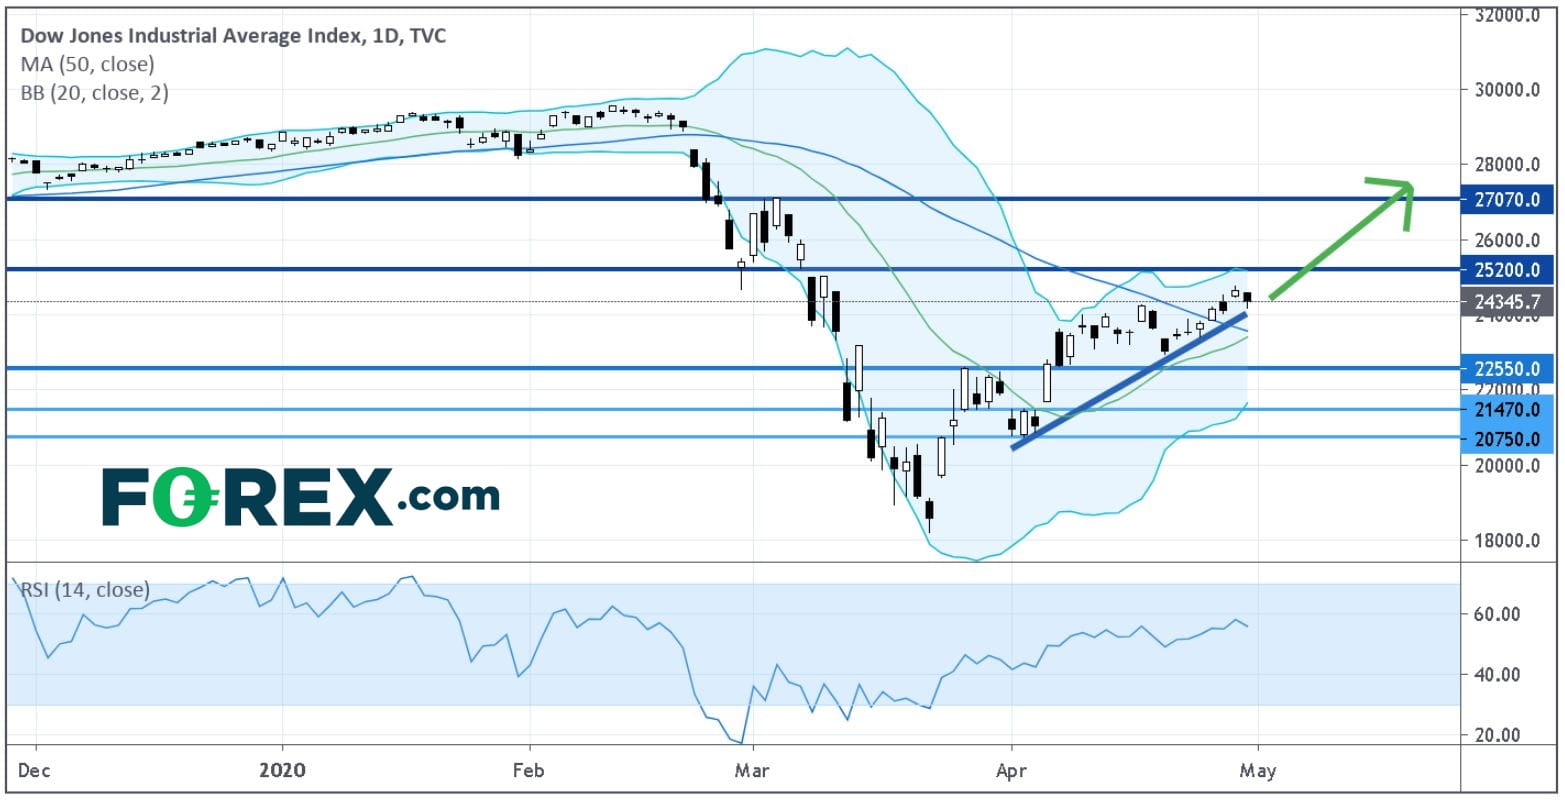
The Dow Jones Industrial Average fell 288 points (-1.2%) to 24,345, and the S&P 500 lost 27 points (-0.9%) to 2,912, while the Nasdaq 100 edged up 17 points (+0.2%) to 9,000.

Automobiles & Components (-4.7%), Banks (-3.19%) and Semiconductors & Semiconductor Equipment (-3.1%) sectors lost the most.
Tapestry (TPR -12.4%), Textron (TXT -12.2%), Molson Coors Brewing (TAP -11.2%), Harley-Davidson (HOG -10.4%) and Gap (GPS -10.3%) lost the most.
On the other hand, Abiomed (ABMD +13.1%), Facebook (FB +5.4%), Marathon Oil (MRO +4.6%) and Amazon.com (AMZN +4.3%) were top gainers.
In after-market hours, Amazon.com (AMZN) traded 5% lower. Apple (AAPL) , United Airlines (UAL), Gilead Sciences (GILD) and Amgen (AMGN) also dropped.
On the technical side, about 31.0% (25.2% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 90.9% (93.3% in the prior session) were above their 20-day moving average.
The U.S. Labor Department report that Initial Jobless Claims for the week ended April 25 amounted to 3.839 million (3.500 million expected).
Personal Income fell 2.0% on month in March (-1.5% expected), the biggest fall since 2013. Personal Spending dropped 7.5% (-5.0% expected), the largest decline on record.
The Market News International Chicago Business Barometer slipped to 35.4 in April (37.7 expected), the lowest level since 2009.
Later today, latest data on the Markit U.S. Manufacturing Purchasing Managers' Index (36.7 expected), the Institute for Supply Management (ISM) Manufacturing PMI (36.0 expected), and Construction Spending (-3.5% on month expected) will be reported.
Meanwhile, the U.S. federal government's coronavirus social distancing guidelines expired on Thursday, and President Donald Trump said those guidelines will not be extended.
European stocks turned to the downside, with the Stoxx Europe 600 Index falling 2.0%. Germany's DAX lost 2.2%, France's CAC slipped 2.1%, and the U.K.'s FTSE 100 slumped 3.5%.
U.S. Treasury prices stabilized, as the benchmark 10-year U.S. Treasury yield eased to 0.619% from 0.622% Wednesday.
Spot gold tumbled 25 dollars or 1.5% to $1,686 an ounce.
Oil prices advanced further, as U.S. WTI crude oil futures (June) jumped 25.0% to $18.84 a barrel, and Brent crude oil futures gained 11.0% to $25.27 a barrel.
The Dow Jones Industrial Average fell 288 points (-1.2%) to 24,345, and the S&P 500 lost 27 points (-0.9%) to 2,912, while the Nasdaq 100 edged up 17 points (+0.2%) to 9,000.
Source: GAIN Capital, TradingView
Automobiles & Components (-4.7%), Banks (-3.19%) and Semiconductors & Semiconductor Equipment (-3.1%) sectors lost the most.
Tapestry (TPR -12.4%), Textron (TXT -12.2%), Molson Coors Brewing (TAP -11.2%), Harley-Davidson (HOG -10.4%) and Gap (GPS -10.3%) lost the most.
On the other hand, Abiomed (ABMD +13.1%), Facebook (FB +5.4%), Marathon Oil (MRO +4.6%) and Amazon.com (AMZN +4.3%) were top gainers.
In after-market hours, Amazon.com (AMZN) traded 5% lower. Apple (AAPL) , United Airlines (UAL), Gilead Sciences (GILD) and Amgen (AMGN) also dropped.
On the technical side, about 31.0% (25.2% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 90.9% (93.3% in the prior session) were above their 20-day moving average.
The U.S. Labor Department report that Initial Jobless Claims for the week ended April 25 amounted to 3.839 million (3.500 million expected).
Personal Income fell 2.0% on month in March (-1.5% expected), the biggest fall since 2013. Personal Spending dropped 7.5% (-5.0% expected), the largest decline on record.
The Market News International Chicago Business Barometer slipped to 35.4 in April (37.7 expected), the lowest level since 2009.
Later today, latest data on the Markit U.S. Manufacturing Purchasing Managers' Index (36.7 expected), the Institute for Supply Management (ISM) Manufacturing PMI (36.0 expected), and Construction Spending (-3.5% on month expected) will be reported.
Meanwhile, the U.S. federal government's coronavirus social distancing guidelines expired on Thursday, and President Donald Trump said those guidelines will not be extended.
European stocks turned to the downside, with the Stoxx Europe 600 Index falling 2.0%. Germany's DAX lost 2.2%, France's CAC slipped 2.1%, and the U.K.'s FTSE 100 slumped 3.5%.
U.S. Treasury prices stabilized, as the benchmark 10-year U.S. Treasury yield eased to 0.619% from 0.622% Wednesday.
Spot gold tumbled 25 dollars or 1.5% to $1,686 an ounce.
Oil prices advanced further, as U.S. WTI crude oil futures (June) jumped 25.0% to $18.84 a barrel, and Brent crude oil futures gained 11.0% to $25.27 a barrel.
On Thursday U.S. stocks pared a part of gains made in the prior session. Market sentiment was dampened by a series of downbeat economic data.
The Dow Jones Industrial Average fell 288 points (-1.2%) to 24,345, and the S&P 500 lost 27 points (-0.9%) to 2,912, while the Nasdaq 100 edged up 17 points (+0.2%) to 9,000.
Automobiles & Components (-4.7%), Banks (-3.19%) and Semiconductors & Semiconductor Equipment (-3.1%) sectors lost the most.
Tapestry (TPR -12.4%), Textron (TXT -12.2%), Molson Coors Brewing (TAP -11.2%), Harley-Davidson (HOG -10.4%) and Gap (GPS -10.3%) lost the most.
On the other hand, Abiomed (ABMD +13.1%), Facebook (FB +5.4%), Marathon Oil (MRO +4.6%) and Amazon.com (AMZN +4.3%) were top gainers.
In after-market hours, Amazon.com (AMZN) traded 5% lower. Apple (AAPL) , United Airlines (UAL), Gilead Sciences (GILD) and Amgen (AMGN) also dropped.
On the technical side, about 31.0% (25.2% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 90.9% (93.3% in the prior session) were above their 20-day moving average.
The U.S. Labor Department report that Initial Jobless Claims for the week ended April 25 amounted to 3.839 million (3.500 million expected).
Personal Income fell 2.0% on month in March (-1.5% expected), the biggest fall since 2013. Personal Spending dropped 7.5% (-5.0% expected), the largest decline on record.
The Market News International Chicago Business Barometer slipped to 35.4 in April (37.7 expected), the lowest level since 2009.
Later today, latest data on the Markit U.S. Manufacturing Purchasing Managers' Index (36.7 expected), the Institute for Supply Management (ISM) Manufacturing PMI (36.0 expected), and Construction Spending (-3.5% on month expected) will be reported.
Meanwhile, the U.S. federal government's coronavirus social distancing guidelines expired on Thursday, and President Donald Trump said those guidelines will not be extended.
European stocks turned to the downside, with the Stoxx Europe 600 Index falling 2.0%. Germany's DAX lost 2.2%, France's CAC slipped 2.1%, and the U.K.'s FTSE 100 slumped 3.5%.
U.S. Treasury prices stabilized, as the benchmark 10-year U.S. Treasury yield eased to 0.619% from 0.622% Wednesday.
Spot gold tumbled 25 dollars or 1.5% to $1,686 an ounce.
Oil prices advanced further, as U.S. WTI crude oil futures (June) jumped 25.0% to $18.84 a barrel, and Brent crude oil futures gained 11.0% to $25.27 a barrel.
The Dow Jones Industrial Average fell 288 points (-1.2%) to 24,345, and the S&P 500 lost 27 points (-0.9%) to 2,912, while the Nasdaq 100 edged up 17 points (+0.2%) to 9,000.
Source: GAIN Capital, TradingView
Automobiles & Components (-4.7%), Banks (-3.19%) and Semiconductors & Semiconductor Equipment (-3.1%) sectors lost the most.
Tapestry (TPR -12.4%), Textron (TXT -12.2%), Molson Coors Brewing (TAP -11.2%), Harley-Davidson (HOG -10.4%) and Gap (GPS -10.3%) lost the most.
On the other hand, Abiomed (ABMD +13.1%), Facebook (FB +5.4%), Marathon Oil (MRO +4.6%) and Amazon.com (AMZN +4.3%) were top gainers.
In after-market hours, Amazon.com (AMZN) traded 5% lower. Apple (AAPL) , United Airlines (UAL), Gilead Sciences (GILD) and Amgen (AMGN) also dropped.
On the technical side, about 31.0% (25.2% in the prior session) of stocks in the S&P 500 Index were trading above their 200-day moving average, and 90.9% (93.3% in the prior session) were above their 20-day moving average.
The U.S. Labor Department report that Initial Jobless Claims for the week ended April 25 amounted to 3.839 million (3.500 million expected).
Personal Income fell 2.0% on month in March (-1.5% expected), the biggest fall since 2013. Personal Spending dropped 7.5% (-5.0% expected), the largest decline on record.
The Market News International Chicago Business Barometer slipped to 35.4 in April (37.7 expected), the lowest level since 2009.
Later today, latest data on the Markit U.S. Manufacturing Purchasing Managers' Index (36.7 expected), the Institute for Supply Management (ISM) Manufacturing PMI (36.0 expected), and Construction Spending (-3.5% on month expected) will be reported.
Meanwhile, the U.S. federal government's coronavirus social distancing guidelines expired on Thursday, and President Donald Trump said those guidelines will not be extended.
European stocks turned to the downside, with the Stoxx Europe 600 Index falling 2.0%. Germany's DAX lost 2.2%, France's CAC slipped 2.1%, and the U.K.'s FTSE 100 slumped 3.5%.
U.S. Treasury prices stabilized, as the benchmark 10-year U.S. Treasury yield eased to 0.619% from 0.622% Wednesday.
Spot gold tumbled 25 dollars or 1.5% to $1,686 an ounce.
Oil prices advanced further, as U.S. WTI crude oil futures (June) jumped 25.0% to $18.84 a barrel, and Brent crude oil futures gained 11.0% to $25.27 a barrel.
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Dow Jones forecast: Stock markets under pressure from multiple sources
When looking at the major tech-heavy US indices like the S&P 500 or the Nasdaq 100, you wouldn’t think that the stock market is particularly weak. Yet, beneath the surface, the market is far from healthy right now. Investors are evidently just piling into the big tech and AI names, and as a result, market breadth is deteriorating. Other indices like the small cap Russell 2000 and the Dow Jones are starting to reflect that weakness.


Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum


S&P 500 Forecast: SPX Continues to Drift Away from Record Highs
Recent trading sessions have done little to restore confidence in the equity market. Over the last four sessions, the S&P 500 has declined by nearly 1.00%, a move that highlights growing short-term weakness and keeps the index moving further away from its record-high territory.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.