




AUD/USD Weekly Outlook: CPI, RBNZ, PCE - Key Data Ahead
AUD/USD eyes key support and resistance as Australian CPI, RBNZ, and US PCE inflation data loom. Trump’s fiscal policies and weak bond auctions fuel market uncertainty.
Share this:

- Australian monthly CPI is the major domestic risk event; softer inflation could increase the probability of another RBA rate cut in July.
- Governor Bullock confirmed a 50bp cut was discussed, reinforcing the RBA’s dovish stance as inflation returns to the target band.
- Retail sales data will also be watched, with sluggish consumer spending further supporting the RBA's easing bias.
- President Trump’s fiscal policies and a weak bond auction drove US bond yields higher, capping AUD/USD upside despite the dovish RBA.
- US core and ‘super core’ PCE inflation prints could determine the Fed’s next move and heavily influence USD direction.
Australian Economic Data: Monthly CPI Data on Wednesday
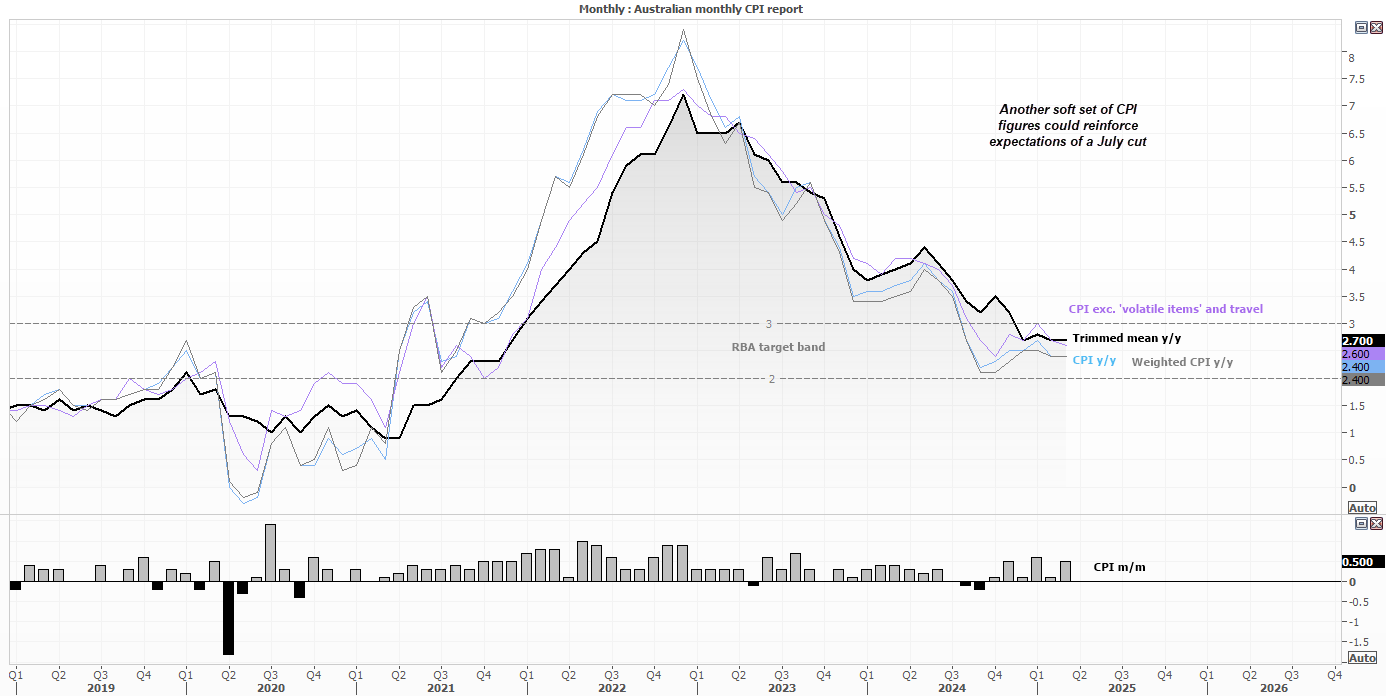
The Reserve Bank of Australia (RBA) delivered a dovish 25 basis point rate cut last week, and a softer monthly CPI inflation report this week could further strengthen expectations of another cut in July. The Board acknowledged that “inflation has fallen substantially” from its peak and is now comfortably within the 2–3% target band. Crucially, the RBA also noted that upside risks to inflation have diminished.
The fact that Governor Michele Bullock confirmed a 50bp cut was discussed sends a clear signal that the RBA is open to front-loading its easing cycle if incoming data supports such a move.
RBA cash rate futures currently imply around a 70% chance of a July cut, with 50bp of cuts fully priced in by November. These odds might be even higher had the RBA not flagged a tight labour market — an assessment that was validated by another strong employment report. Still, expectations for a July rate cut could be bolstered if trimmed mean CPI inflation softens further this week.
Also worth watching is the retail sales data. While not a direct catalyst for rate decisions, retail spending continues to contribute very little to economic growth. Given the RBA’s repeated references to soft household demand, another weak retail report would likely bolster the case for continued monetary easing.
View related analysis:
- USD/JPY and GBP/JPY Snap Losing Streaks, US Dollar Selling Eases
- WTI Crude Oil Outlook: Bearish Risks Build as Traders Trim Longs
- Japanese Yen and VIX Rise as Wall Street Slips on Weak Bond Auction
- Gold Rally Stalls Below Monthly High: Is a Deeper Pullback Brewing?
View related analysis:
- USD/JPY and GBP/JPY Snap Losing Streaks, US Dollar Selling Eases
- WTI Crude Oil Outlook: Bearish Risks Build as Traders Trim Longs
- Japanese Yen and VIX Rise as Wall Street Slips on Weak Bond Auction
- Gold Rally Stalls Below Monthly High: Is a Deeper Pullback Brewing?
US Economic Data: Consumer Sentiment, GDP, PCE Inflation – and Trump
President Donald Trump remains a key influence on global markets through his policy announcements and fiscal plans. Bond yields surged last week following a weak 20-year bond auction, as investors showed concern over the higher fiscal deficit his agenda is expected to bring. This has weighed on the US dollar and kept AUD/USD rangebound — despite the RBA’s dovish bias.
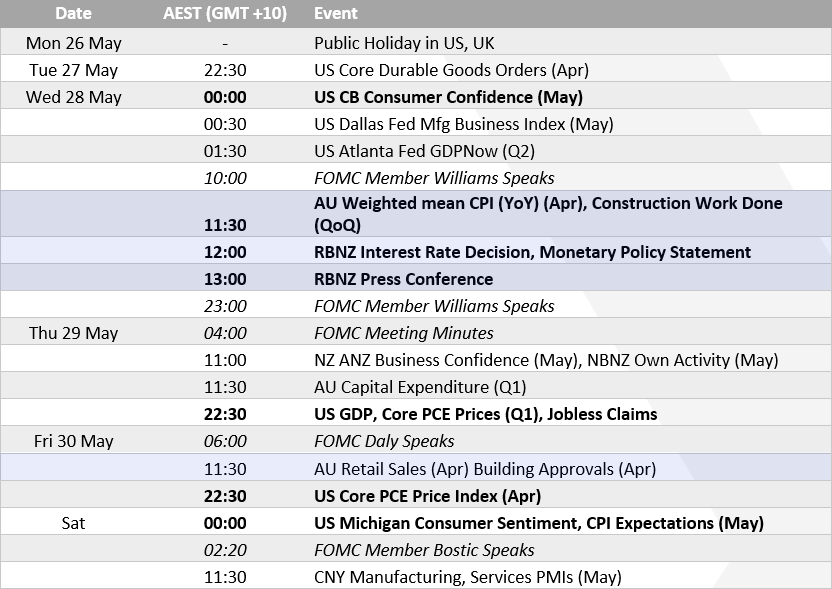
This week, traders will assess whether US consumer sentiment has picked up in the Conference Board and University of Michigan surveys — particularly in light of an improved tone around tariffs. That said, any meaningful rise in sentiment seems unlikely. Softer inflation expectations would be welcomed, especially given the one-year outlook recently surged to 6.5%.
Q1 GDP data will be released but is considered stale, while Federal Reserve commentary is unlikely to shift materially until trade and inflation risks become clearer.
Keep A Close Eye On ‘Super Core’ PCE Inflation
The most important release from the US will be the PCE price index — the Fed’s preferred inflation gauge. While headline CPI and year-on-year core PCE figures have eased, the month-over-month readings — particularly the ‘super core’ PCE, which excludes food, energy, and housing — are causing concern.
In April, super core PCE rose by 0.6% — its highest monthly gain since January 2024. If this metric remains elevated or accelerates, it could delay potential Fed rate cuts and revive fears of stagflation. That scenario could strengthen the US dollar and weigh on AUD/USD, especially if Australian data underwhelms.
Reserve Bank of New Zealand (RBNZ): 25bp Cut expected
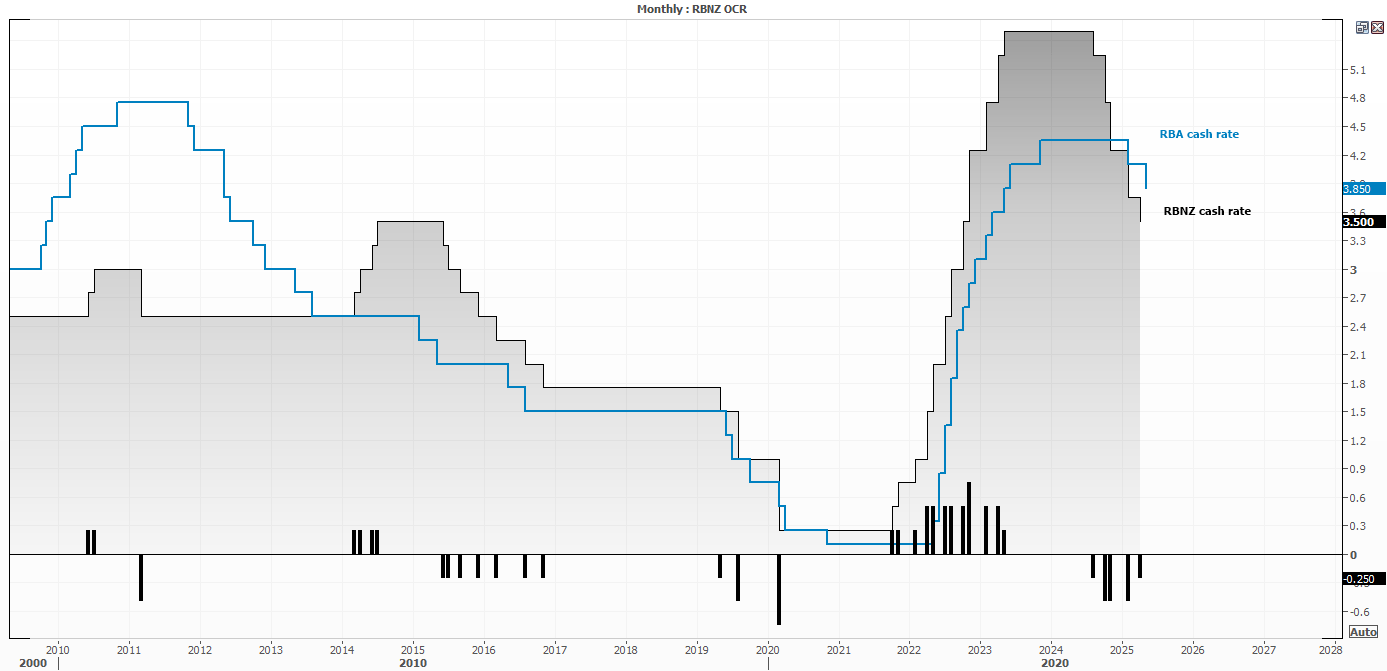
It is widely expected that the RBNZ will cut their overnight cash rate (OCR) by 25bp to 3.25% on Wednesday. It would mark their sixth cut of the easing cycle, and widen the RBA-RBNZ cash rate spread to 60bp.
CPI y/y is at 2.2% (within the 1–3% target band), and although two-year inflation expectations have ticked up to 2.29%, they remain anchored and not high enough to derail the easing bias. Job growth has slowed and underemployment has crept higher, suggesting spare capacity remains in the economy.
The focus is therefore on whether they will signal any further cuts. If they do, AUD/NZD should weaken as it suggests that the RBNZ cash rate will end beneath the RBA’s at the end of the year.
AUD/USD correlations
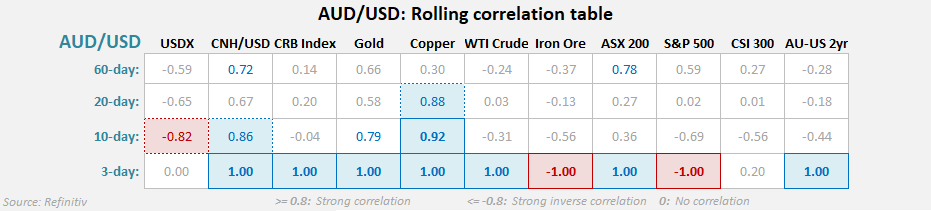
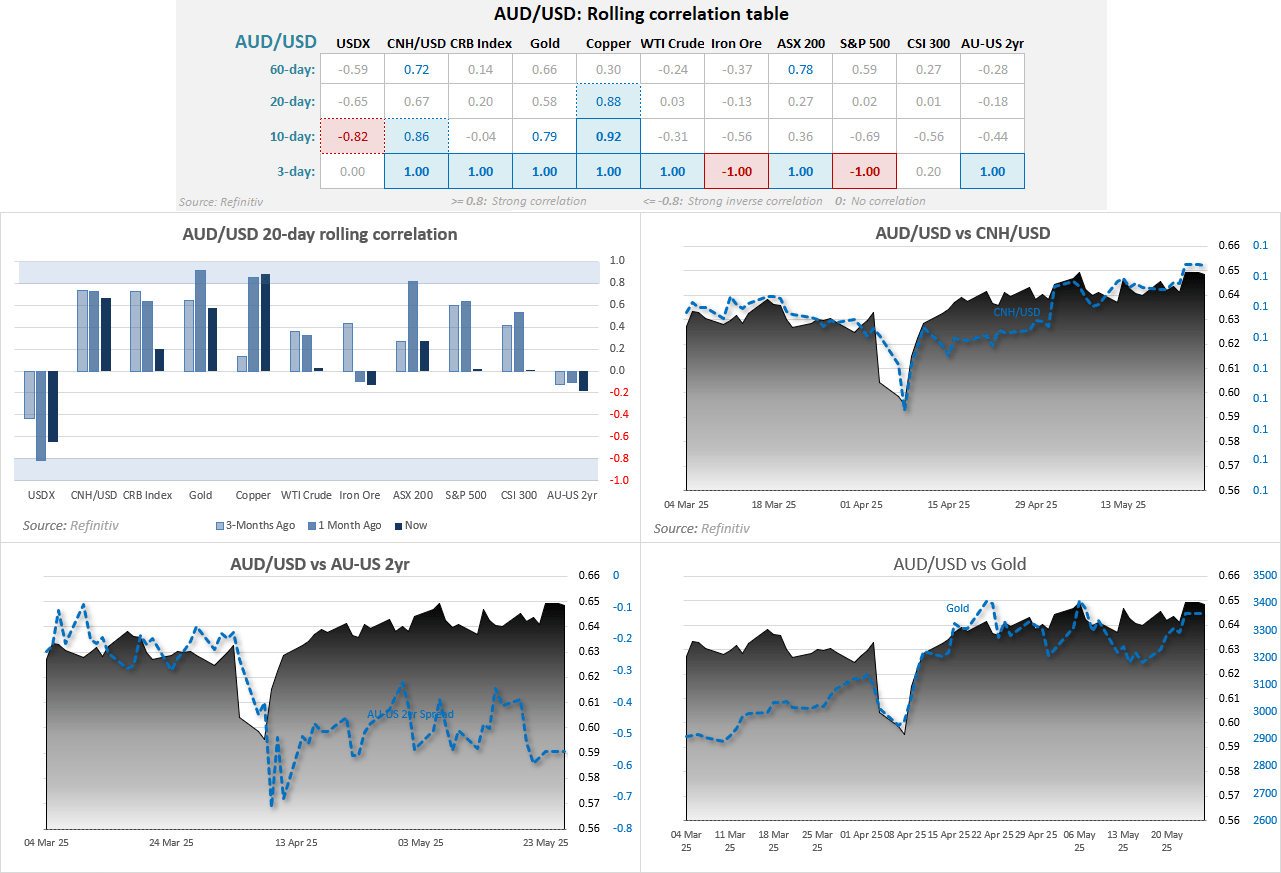
The Australian dollar retains a strong correlation with the Chinese yuan over the 3- and 10-day timeframes, although this link weakens slightly over the 20- and 60-day periods.
Additionally, copper and gold prices maintain a positive correlation with AUD/USD over the shorter 3- and 10-day horizons, reinforcing the Aussie’s commodity-linked nature.
AUD/USD Futures: COT Report
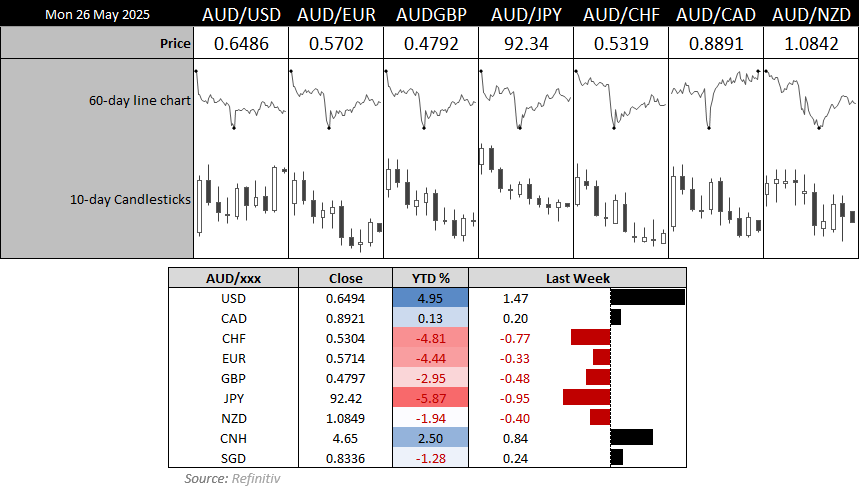
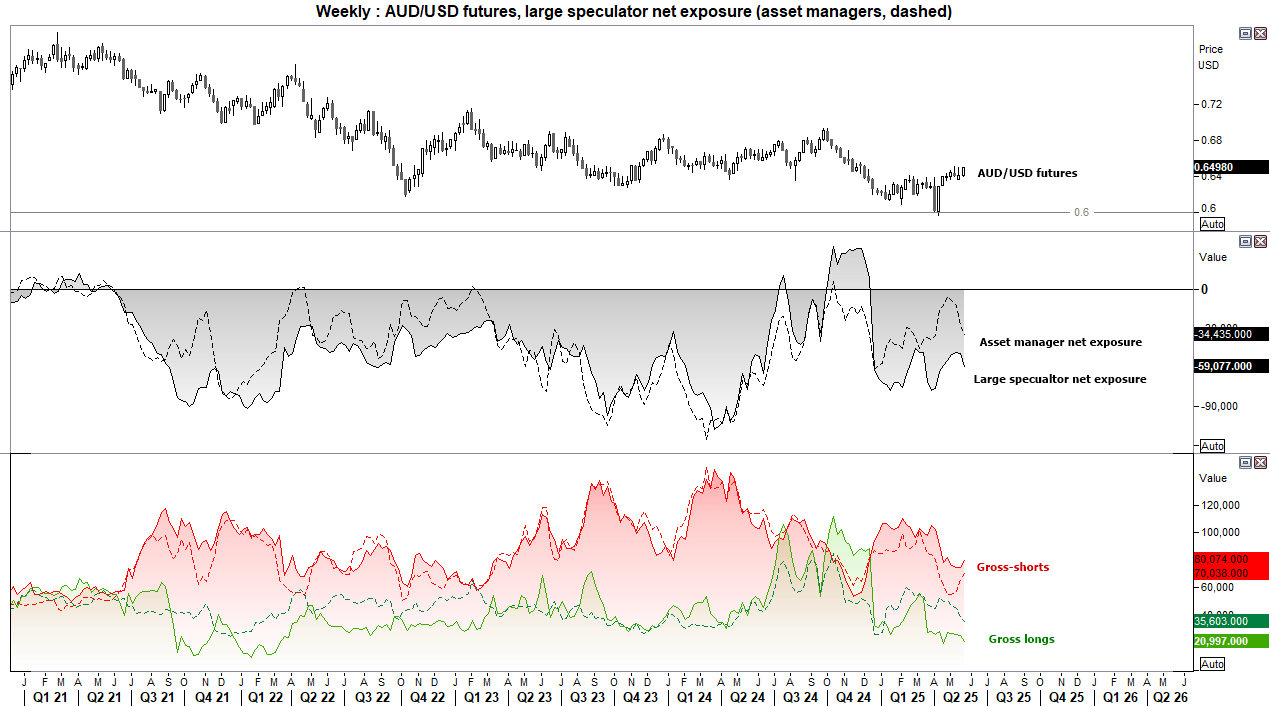
Traders increased their net-short exposure to AUD/USD futures last week, yet Aussie bulls scored a 1.5% weekly gain, marking the best performance in eight weeks.
The US dollar remains under heavy selling pressure, driven by worries over US fiscal stability following the sovereign credit downgrade and President Trump’s tariff threats on the European Union.
AUD/USD Technical Analysis: Australian Dollar vs US Dollar
The US Dollar Index snapped a four-week winning streak with its most bearish week in six, opening near the high and closing at the low — fuelling an Aussie dollar rally.
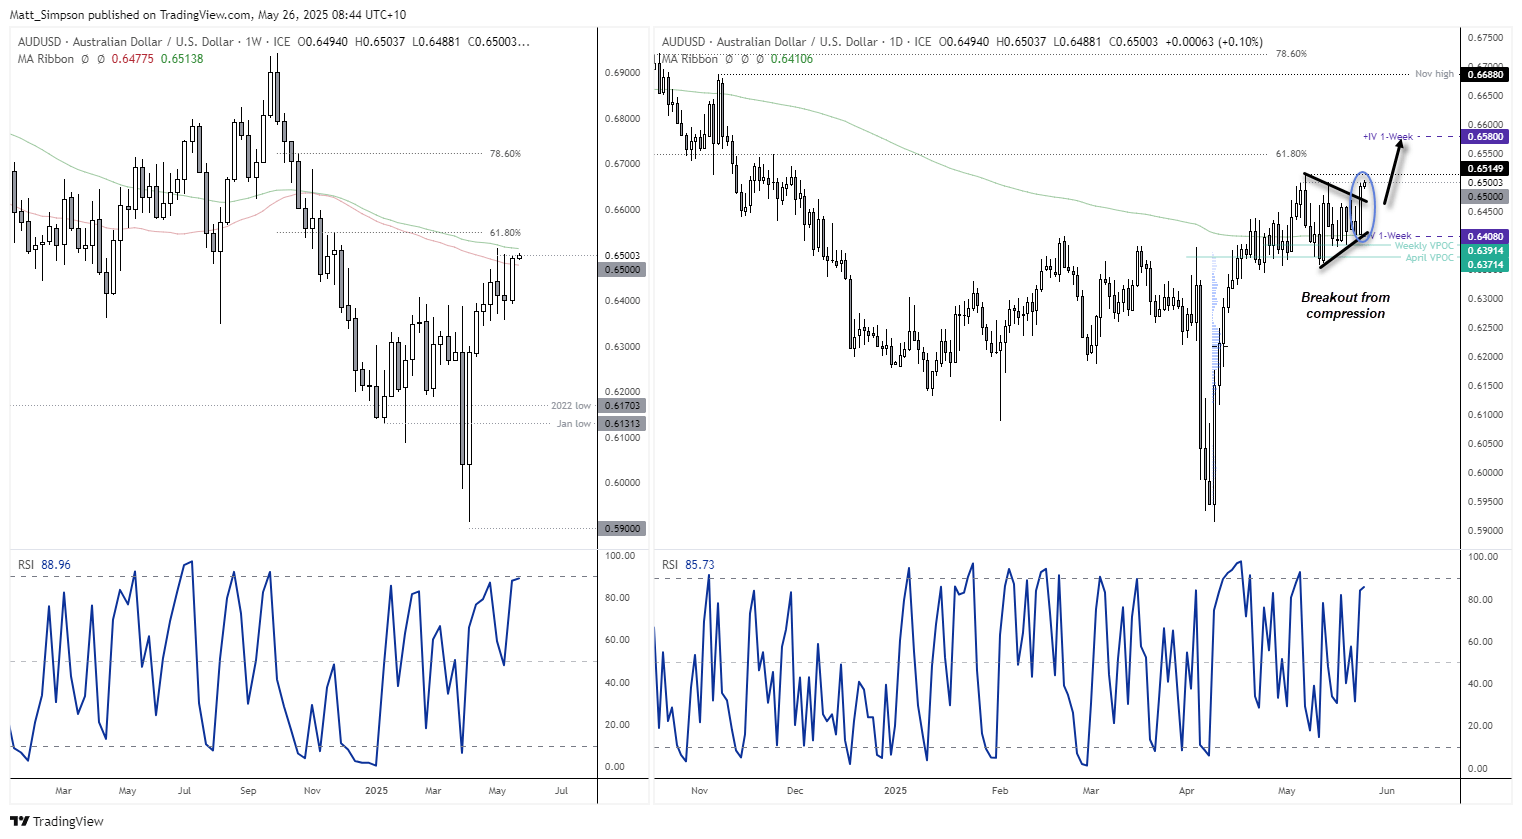
On Friday, AUD/USD printed a bullish engulfing candle and is now flirting with a breakout above the 65-cent handle. However, a confirmed breakout would require a move above the 200-week SMA and May high at 0.6515.
The 61.8% Fibonacci level at 0.6550 marks the next resistance target, with the 66-cent handle and November high near 0.67 in play if USD weakness accelerates.
One-week implied volatility bands suggest a potential range between 0.6408 and 0.6580. A 66c test is possible this week if Aussie CPI surprises and the greenback remains under pressure.
The bias stays bullish while AUD/USD trades above 0.64.
-- Written by Matt Simpson
Follow Matt on Twitter @cLeverEdge
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the market you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Australian Dollar Outlook: AUD/USD Screams Sentiment Extreme Into Fed, CPI
AUD/USD rebounds despite record bearish futures positioning, with Australian Q3 CPI and the Fed meeting threatening to trigger another short squeeze.
EUR/USD weekly outlook: FOMC and ECB to set the tone
The current backdrop is modestly bearish. On Friday, the EUR/USD closed modestly lower, down for the third consecutive day. The pair also posted a weekly decline after staging a modest recovery attempt in the previous week. Out of the past 8 weeks, the EUR/USD has fallen on 6 occasions. There is not much supporting factors for the single currency right now. So, the upside remains capped.

USD/JPY Forecast: Is Rising Japanese Inflation Supporting the Yen?
As the trading week comes to an end, one of the most relevant developments in the FX market has been the renewed strength of the Japanese yen. This can be seen in the recent performance of USD/JPY, which has fallen nearly 1.0% over the last two trading sessions, highlighting a meaningful recovery in the Japanese currency against the U.S. dollar.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.