
FOMC Fallout: 5 Signs Chairman Warsh’s Honeymoon at the Fed is Over
The bear steepening in the Treasury markets, decision outsourcing to the bond market, three hawkish dissents, dollar weakness, and simultaneous drop in stocks and bonds are warning signs for new FOMC Chairman Warsh - volatility ahead?
Share this:
FOMC, Fed Key Takeaways
- There are at least five signs that the market is starting to lose confidence in FOMC Chairman Warsh’s inflation fighting bona fides.
- The bear steepening in the Treasury markets, decision outsourcing to the bond market, three hawkish dissents, dollar weakness, and simultaneous drop in stocks and bonds are warning signs.
- Upcoming NFP and CPI reports, as well as Chairman Warsh’s Jackson Hole speech, will likely drive more market volatility than usual given the uncertainty around the Fed’s framework.
Traders were treated to a full slate of US economic data this morning with the first reading of Q2 GDP coming in at 1.5%, well below the 2.1% print expected by economists, Core PCE near expectations at 3.3% y/y, and initial jobless claims below 200K for the second straight week.
Despite these updates on the US economy, the far more important takeaways come from FOMC Chairman Warsh’s press conference yesterday and the market’s reaction to it. Reading between the lines, there are at least five signs that the market is starting to lose confidence in Warsh’s inflation-fighting bona fides:
1. Long-Term Yields Surged While Short-Term Yields Fell
The clearest warning comes from the Treasury market.
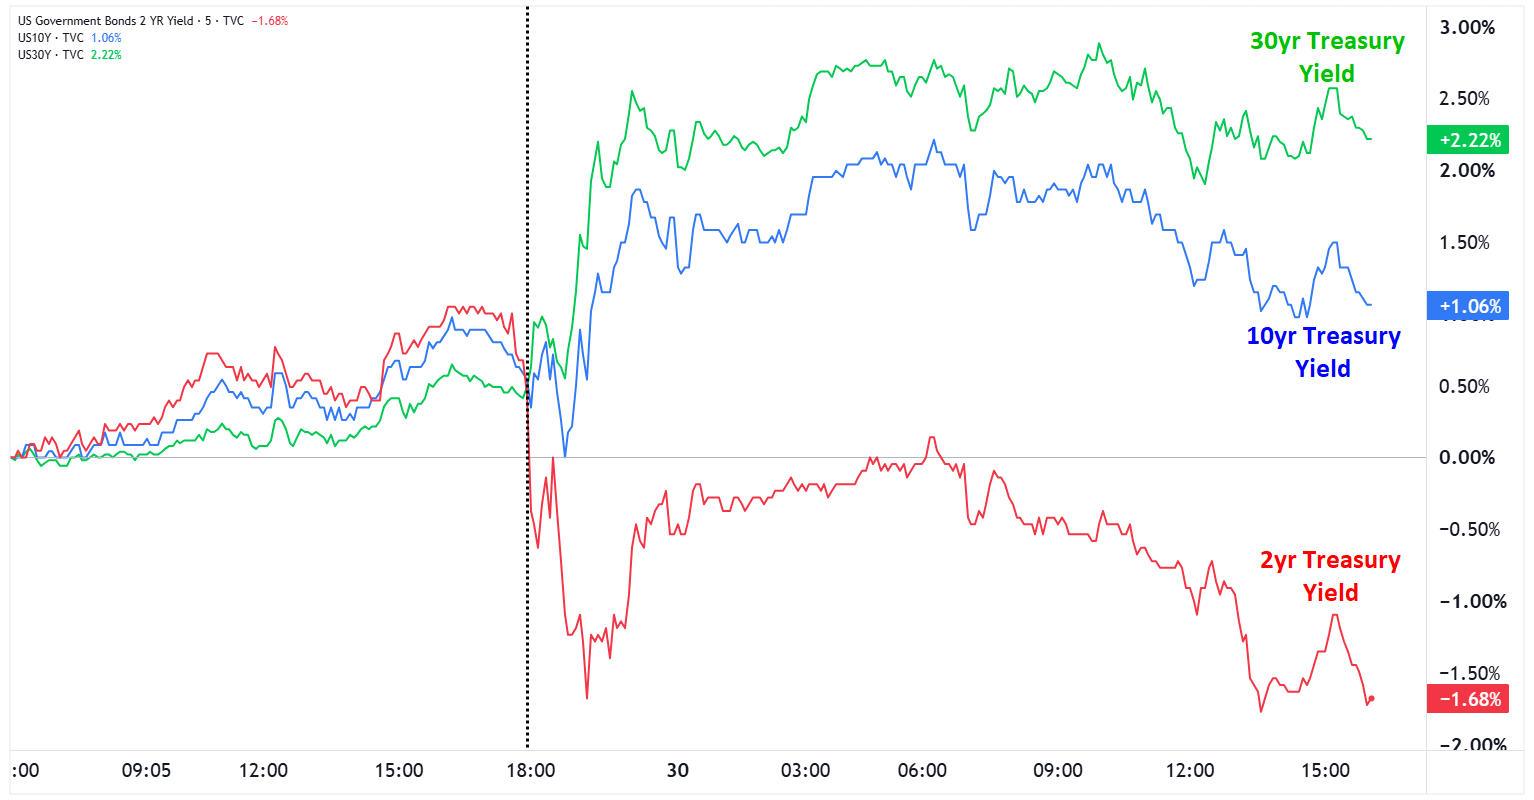
The two-year yield, which is highly sensitive to near-term Fed policy, declined after the meeting, signaling that traders are pushing back expectations for an imminent interest rate increase from the FOMC. Meanwhile, the 10-year yield rose sharply and the 30-year yield posted an even larger increase.
Source: Tradingview, StoneX
To put it plainly, this is not the typical reaction to a dovish Fed surprise. If traders believed the Fed had correctly concluded that less tightening was necessary, yields would likely have declined across the curve, or at least remained relatively stable at the long end.
Instead, the bond market move suggests investors became less confident in an imminent rate hike while demanding more compensation to hold longer-term bonds. In other words, markets may believe the Fed will remain patient now, but that inflation will consequently stay higher for longer.
2. Warsh Appeared to Rely on the Bond Market to Tighten Policy
Showing unusual deference to the bond market, Warsh repeatedly pointed to the rise in market interest rates as a reason the Fed could afford to wait. His argument was that higher Treasury yields had already tightened financial conditions, reducing the immediate need for another rate increase.
There are two problems with this view. First, Warsh’s explanation risks appearing outcome-dependent. At Sintra earlier this month, he suggested falling bond yields showed that markets understood inflation would decline. This week, he argued that rising yields were tightening financial conditions enough to reduce the need for immediate Fed action. Treating both falling and rising yields as validation of the Fed’s stance makes his reaction function difficult for traders to understand.
The other issue is that yields may be rising precisely because investors are worried about inflation and Fed credibility, creating a potentially risky feedback loop. Inflation concerns push long-term yields higher, the Fed cites those higher yields as a reason not to act, and investors become even more concerned that policymakers are falling behind the curve.
3. Three Policymakers Dissented in Favor of a Rate Increase
The decision to hold rates steady passed by a 9–3 vote, with three officials preferring an immediate 25-basis-point increase. Dissents are not necessarily rare, and Warsh has encouraged more open debate within the committee.
According to the St. Louis Fed’s database, at least three members have dissented at only 56 meetings since comparable records begin in March 1936, roughly 6.5% of all meetings. Even more notable, all three July dissenters favored the same alternative: an immediate 25-basis-point hike.
The dissents make the decision to wait look less like a strong consensus and more like a judgment call by the chairman and the majority.
4. The Dollar Fell Despite Higher Treasury Yields
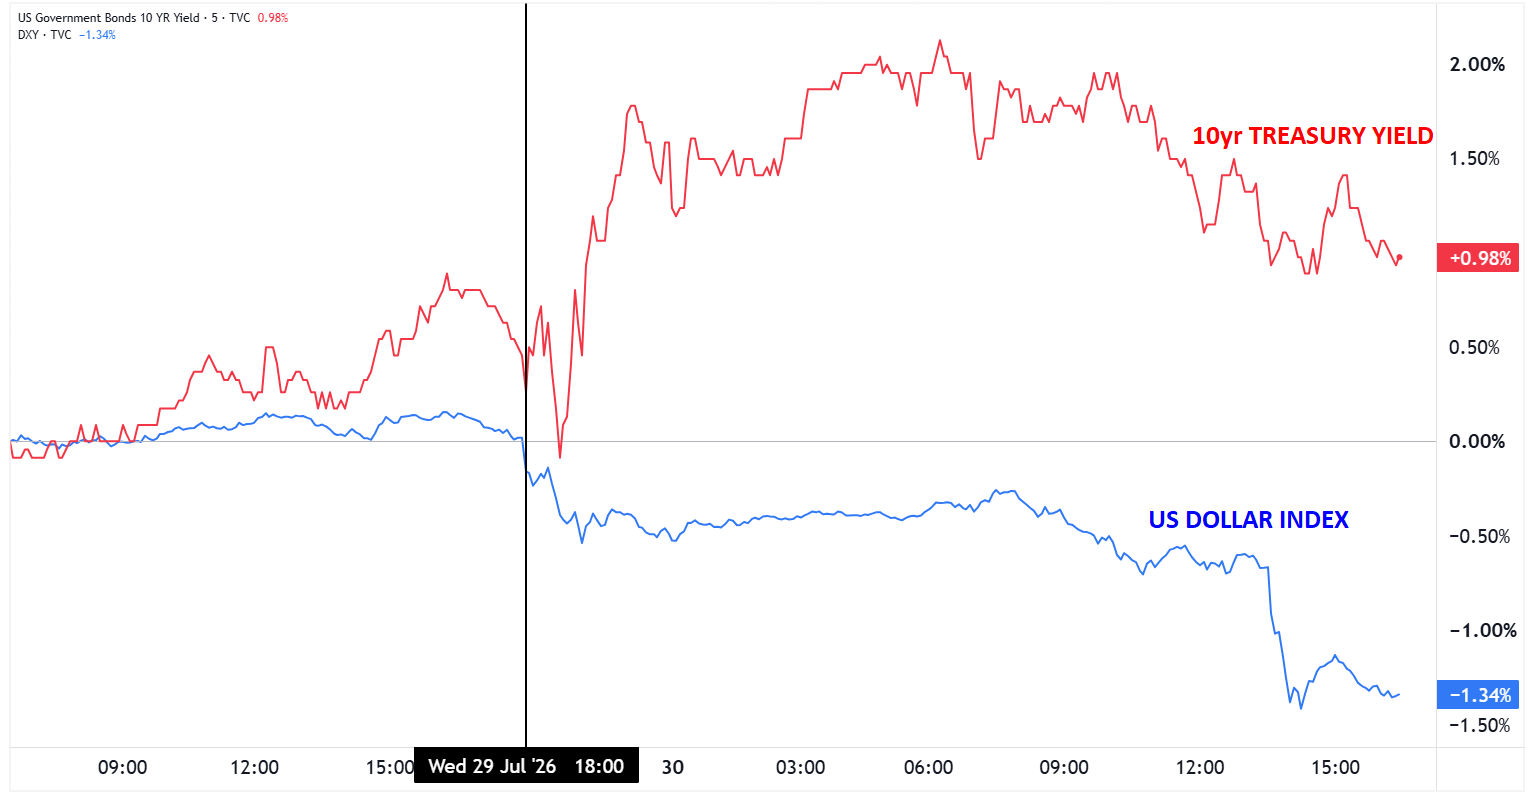
Rising Treasury yields usually provide some support for the US dollar by making dollar-denominated assets more attractive. In the wake of yesterday’s FOMC meeting, the dollar weakened even as longer-term yields climbed:
Source: Tradingview, StoneX
The move suggests currency traders don’t necessarily see the rise in yields as a positive reflection of stronger growth or credible monetary tightening. Instead, the move could be interpreted as compensation for inflation risk, fiscal uncertainty or less predictable Fed policy.
5. Stocks and Long-Term Bonds Sold Off Together
Source: Tradingview, StoneX
The simultaneous decline in equities and long-duration Treasuries is another notable warning. Typically, when investors fear recession, stocks often fall while long-term bonds rally. When yields rise because growth expectations are improving, stocks can sometimes absorb the increase; this yin and yang is the basis of using a classic 60% stocks / 40% bonds investment portfolio to diversify risk.
The post-Fed move fits neither of these patterns.
The combination of falling stocks and bonds is more consistent with an increase in inflation uncertainty, term premium or policy risk. In other words, investors are demanding a higher return for holding both risky assets and long-term government debt.
Why The Fed Has Not Lost Control (Yet), Despite These Warning Signs
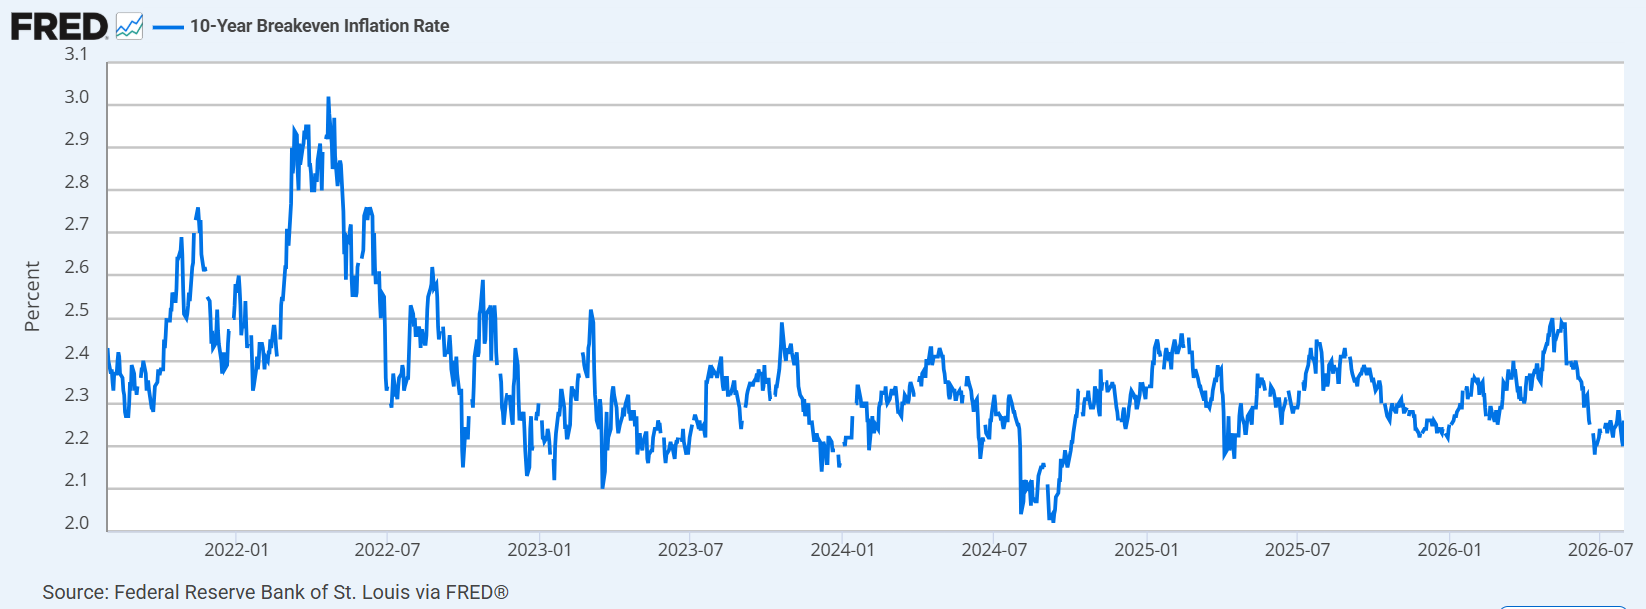
Despite this week’s setback, it’s still too early to conclude that Warsh has lost the market’s confidence. Factors like higher oil prices, further escalation in the US-Iran conflict, fiscal deficits, and heavy Treasury issuance are also contributing to the rise in long-term yields. Indeed, longer-run inflation expectations remain far below levels that would indicate a full-scale credibility crisis:
Source: FRED
Still, the market reaction to the FOMC meeting suggests that traders are beginning to question whether the Fed’s ostensibly hawkish rhetoric will be matched by action.
The next test will be whether inflation continues to run well above target while the Fed remains on hold. If long-term yields and inflation expectations keep rising without a corresponding increase in expected policy rates, concerns that the central bank is falling behind the curve are likely to become much harder to ignore.
The pressure cooker of managing the world’s largest and most important central bank will only rachet up from here. Traders should pay particular attention to the next two employment reports on August 7 and September 4, the CPI releases on August 12 and September 11, and Warsh’s Jackson Hole address on August 27–29. Together, those events will shape expectations ahead of the highly anticipated September 16 FOMC decision and could generate greater-than-usual market volatility.
-- Written by Matt Weller, Global Head of Research
Check out Matt’s Daily Market Update videos on YouTube and be sure to follow Matt on Twitter: @MWellerFX
Latest market news
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US Dollar Price Action Setups: EUR/USD, USD/JPY, GBP/USD, USD/CAD
The Dollar is working on its second consecutive red week and while sellers didn’t exactly pounce on fresh lows, there’s an opening door for bears to make a move.
Nasdaq 100 Forecast: NDX Falls as the tech rout continues and oil prices soar
U.S. stocks are pointing to a modestly lower open after a sharp AI sell-off yesterday, as telecom stocks slide. Brent rises towards $115 adding to inflation pressures ahead of the FOMC rate decision.

Nasdaq, Treasury yields and dollar face a major AI sentiment test
From crude to AI, the forces driving US markets have changed dramatically. Thursday's Nasdaq rout triggered an extraordinary Treasury rally, but the dollar barely moved. What happens next could depend on Nasdaq support.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.