


GBP/USD forecast: Currency Pair of the Week | May 18, 2026
It has been a much calmer start to the new week for risk assets, allowing sterling to stage a decent recovery from near 1.3300 to around 1.3380. European stock markets and US index futures were firmer, after initially extending Friday’s drop at the Asian open overnight. But the calm is unlikely to last for long. We expect further pressure on the bond markets, and this should limit risk appetite.
Share this:
It has been a much calmer start to the new week for risk assets, allowing sterling to stage a decent recovery from near 1.3300 to around 1.3380. European stock markets and US index futures were firmer, after initially extending Friday’s drop at the Asian open overnight. But whether the calm will last remains to be seen. A lot depends on oil now. Should oil go back up, we’d then expect further pressure on the bond markets, and this should limit risk appetite. In short, the near-term GBP/USD forecast still leans to the downside, but a lot now depend on energy prices, global bond yields and investor sentiment generally.
Dollar eases as oil falls back
While concerns surrounding the UK economy are also becoming more visible, the key driver remains the aggressive repricing in global fixed income markets. This morning, though, the pound and other risk assets managed to bounce off their lows. As well as profit-taking, a report by Tasnim that the US had proposed a temporary waiver on Iran oil sanctions during the negotiation period caused oil to ease back from its earlier highs. Will this lead to a big drop in oil as investors price in a potential end to the war? Iran insists that lifting all sanctions on Iran should be part of the US's commitments, but this is good first step, if confirmed. Oil fell around $5 from its earlier highs and this weighed on the US dollar across the board.
Keep an eye on bond yields
Whether the easing of oil will translate into lower yields remains to be seen. On Friday, a renewed surge in US Treasury yields after hotter-than-expected inflation data last week reinforced expectations that the Fed may need to maintain a hawkish tone for longer. Elevated crude prices amid the US-Iran stalemate are creating inflationary shock for global markets. For currencies such as sterling, which are sensitive to growth expectations and external risks, the environment is becoming increasingly challenging.
This week, the US dollar has started the lower. But this comes on the back of a noticeable rally last week after another sharp rise in Treasury yields. The benchmark 10-year yield has meanwhile climbed to its highest level since the opening months of 2025, extending the move higher that followed last week’s inflation figures.
As well as a hotter CPI, PPI inflation in the US surprised significantly to the upside, fuelling concern that inflationary pressures are proving far more persistent than policymakers had hoped. Markets are increasingly questioning whether the Federal Reserve has room to continue discussing eventual easing while price pressures remain elevated.
The result has been a broad repricing across bond markets. Investors are demanding higher yields to compensate for inflation risks, and that shift is supporting the dollar against most major currencies.
Attention this week will turn towards commentary from Federal Reserve officials and the release of the latest FOMC meeting minutes. Fed Governor Christopher Waller is scheduled to speak on Tuesday, while Wednesday’s minutes may provide further clues about how seriously policymakers are taking the recent inflation rebound.
For now, the combination of rising yields and weakening risk appetite continues to favour the dollar.
Political uncertainty clouds GBP/USD forecast
Sterling has also been under pressure in recent times because of political uncertainty in the UK. Following last week’s steep decline, the GBP/USD has bounced back along with most other risk assets. But the upside looks limited form here with 1.3400 likely to offer some resistance as Keir Starmer continues to face criticism following disappointing local election results, creating renewed uncertainty around the UK’s fiscal and economic direction. Markets are becoming increasingly sensitive to political instability at a time when the UK economy is already vulnerable to higher energy costs.
That risk is particularly acute given Britain’s reliance on imported energy. Elevated crude prices and continued disruption around the Strait of Hormuz threaten to deepen inflationary pressures while simultaneously weakening consumer demand and business confidence. Against this backdrop, the sellers could come back on any meaningful rebounds like the one we have seen today.
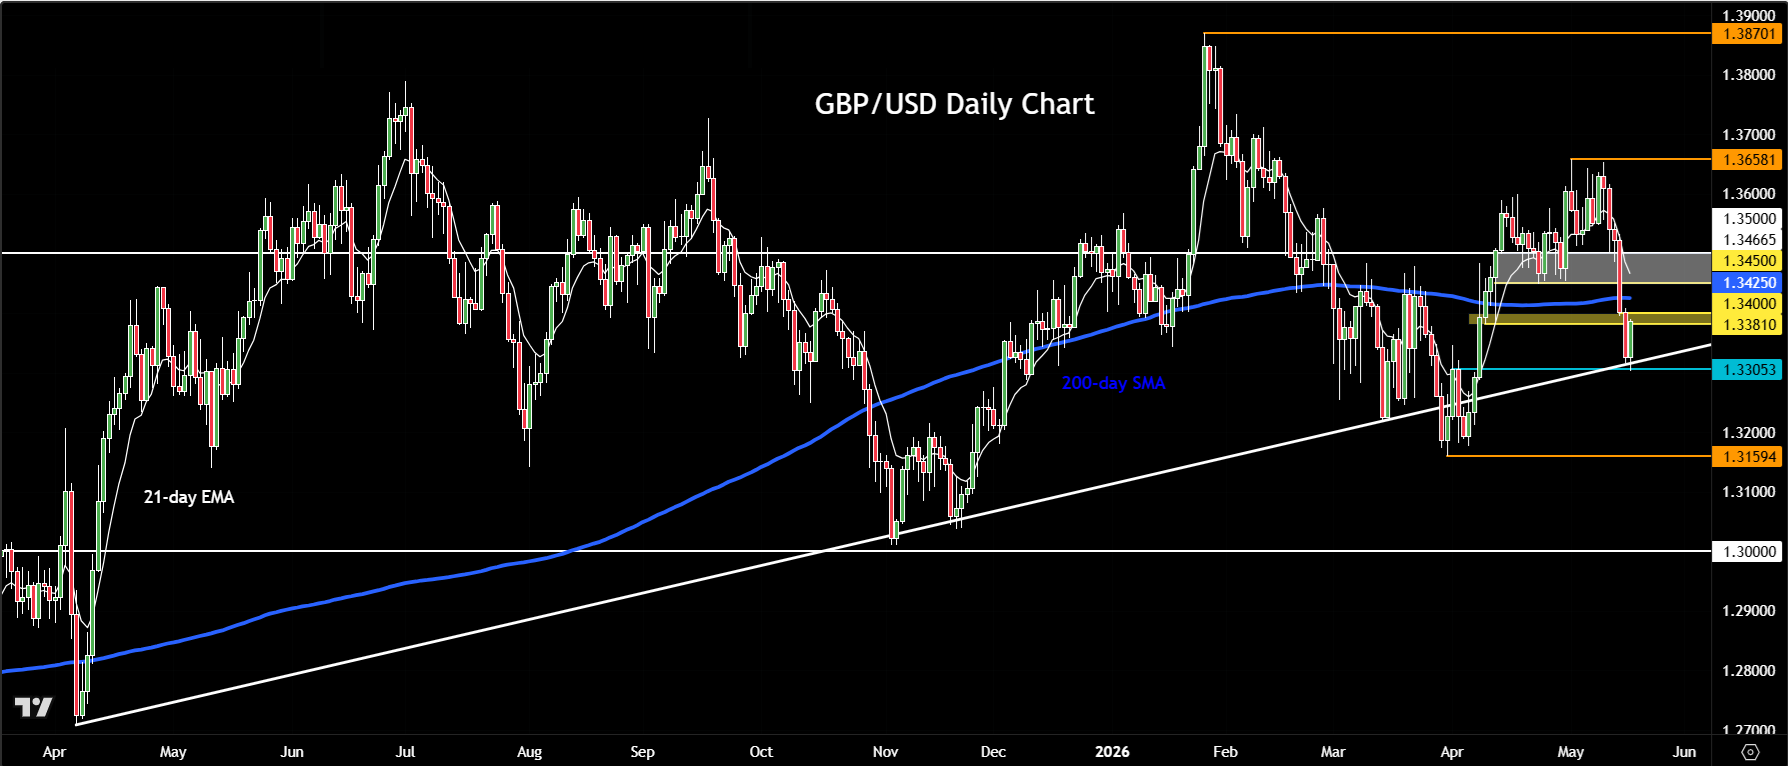
Above 1.3400, the next key resistance is at 1.3450 and then 1.3500. Potential support is seen at 1.3300, 1.3250 and then 1.3140.
So far, the UK has weathered the storm
There have nevertheless been some encouraging economic signals. The International Monetary Fund upgraded its UK growth forecast for 2026 to 1%, up from 0.8% previously. However, the IMF also warned that the UK remains particularly exposed to the economic fallout from Middle East tensions and ongoing domestic uncertainty.
Last week’s release of UK GDP figures offered a degree of resilience. The UK economy expanded by 0.6% quarter-on-quarter in the first quarter, accelerating from 0.2% previously and matching expectations. March GDP also surprised positively with a 0.3% monthly increase despite concerns over rising energy costs and inflation pressures.
Importantly, growth was relatively broad-based. Services, manufacturing and construction all contributed positively, suggesting the expansion was not solely driven by temporary factors or consumer spending distortions.
Focus turns to UK inflation and global PMIs
Markets will now shift attention towards Wednesday’s UK inflation figures. The release could prove particularly important given the recent jump in oil prices and the sharp rise in global bond yields.
UK gilt yields have moved aggressively higher in recent sessions, reflecting both political concerns and broader inflation fears stemming from energy markets. If UK CPI data also surprises to the upside, investors may begin pricing in a more prolonged period of restrictive monetary policy from the Bank of England.
That scenario could generate fresh volatility across sterling, gilts and UK equities.
Later in the week, flash PMI data from the UK, eurozone and the US will offer a broader snapshot of global economic momentum heading into the summer months. Investors will be watching closely for signs that manufacturing activity is being weighed down by oil. and whether the services sector can continue cushioning the slowdown in global growth.
For the GBP/USD forecast, the near-term picture remains difficult. Rising oil prices, stubborn inflation and higher bond yields continue to favour the dollar, while sterling faces the additional burden of domestic political uncertainty and growing concerns over the UK’s exposure to external shocks.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.

USD/CAD shooting star puts September surge on notice
USD/CAD has printed a clear bearish reversal pattern after an extraordinary September surge, but confirmation may depend heavily on how US Treasury yields react to Friday’s payrolls report.


USD/CHF Reverses as Swiss Franc Surges amid Bond Carnage
USD/CHF reverses from channel resistance as bond volatility surges and broad Swiss franc strength points to a possible carry-trade unwind.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.