



Gold Outlook Q4 2025
Gold outlook for Q4 2025 remains bullish, with $4,000 an ounce in bulls' radars. XAU/USD prices supported by central bank demand, a weak US dollar, and expectations of looser monetary policy. But are prices overheating?
Share this:
- Gold outlook for Q4 2025 remains bullish, with $4,000 an ounce in radar
- Prices supported by central bank demand, a weak US dollar, and expectations of looser monetary policy
- Technical analysis: Strong momentum vs. overheating prices
Gold has enjoyed a remarkable run so far in 2025, up 45% as of 29th September. In Q3 alone, it was around 15% higher. About two-thirds of those quarterly gains came in September, when the Fed resumed easing its policy again, triggering bond market rally, even if the dollar managed to hold its ground. The precious metal has repeatedly pushed to new record highs, confirming its position as one of the most talked-about assets of the year. Adjusted for inflation, prices finally exceeded the levels reached more than four decades ago, marking a symbolic milestone. Many analysts are now suggesting that the rally could carry through to year-end with prices topping $4,000 per ounce. The trajectory of gold in the final quarter of 2025 will depend on a familiar but potent mix: the actions of central banks, the fortunes of the US dollar, and the direction of interest rates. Together, these forces have created the ideal setting for bullion to shine, even as equities themselves continue to scale fresh peaks. We maintain a bullish gold outlook for Q4, but overheated prices mean there is increased risk of profit-taking that could introduce some volatility in the market.
Many factors benefitting gold likely to persist in Q4
The strength of gold so far this year is not simply the product of speculation; it is driven by several overlapping trends that have proved resilient throughout the year. Many of these factors may well remain relevant in Q4, keeping the gold outlook positive.
On major source of support for gold has been central bank demand. According to the World Gold Council’s latest survey, an overwhelming majority of central banks plan to expand reserves, with none expecting to reduce holdings despite record prices. This is not just portfolio tinkering. With conflicts persisting in Europe and the Middle East, and with US–China relations still strained, many central banks probably view gold as an essential hedge against geopolitical risk. Nearly three-quarters of respondents also anticipate a decline in the dollar’s share of reserves, a shift that leaves gold as the natural beneficiary.
There is little doubt that gold’s gains have been accelerated because of a weaker US dollar. The greenback has endured one of its poorest years since the early 2000s. By the end of September, the Dollar Index (DXY) was down around 10%. If it finishes the year around these levels, it would mark its weakest performance against major peers since 2003 when the DXY slipped nearly 15%. Much of this year’s weakness is linked to tariffs induced fears of stagflation and a broader sense that America’s economic dominance is being challenged. The trend of de-dollarisation, whereby foreign investors diversify away from US assets, has also gathered pace. For gold, which is priced in dollars, the slide has been an undeniable tailwind, making the metal more attractive for buyers across other currencies.
Another primary driver behind gold’s big gains has been the Federal Reserve cutting interest rates this year. After a lengthy pause, it resumed trimming rates in September as labour market weakness outweighed concerns over inflation, with the central bank indicating that there may be two more cuts to come in Q4. As a result, bond yields fell. Lower yields make non-interest-bearing assets such as gold relatively more appealing.
Can gold and equities continue rising in tandem in Q4?
This is nothing new, of course. Gold and the S&P 500 have had positive correlation for several years now. But in the last couple of years, the correction has been quite strong with both stocks and gold surging to record levels. Historically, gold thrived only when risk appetite faltered, while stocks rallied when growth prospects appear strong. But this negative correlation seems to have been broken down almost entirely. Some of the explanation lies in lower interest rates and the dollar and US bonds losing some of their appeal, while haven demand for gold is always there. Whatever the reason, the important point here is that if gold or stocks begin to top out, this could be a major warning signal for the other asset. It is therefore worth watch both markets closely. Still, history tells us that such co-movement does not last indefinitely. Eventually, one of the two assets will break away, depending on whether economic growth proves sustainable, or risks reassert themselves.
Gold outlook remains positive in Q4
As we enter the business end of the year, investors will be watching closely to see whether gold can sustain its momentum and whether it will reach and move beyond $4,000 per ounce. Much will depend on the trajectory of US monetary policy and whether the Fed delivers further rate cuts. A faster pace of easing could accelerate the rally, while a firmer stance could take some of the shine off. We think that two more rate cuts are on the way, and this should keep the gold outlook positive in Q4, keeping the downside limited.
The political backdrop also remains important. With trade tensions and tariffs shaping the global landscape, and with geopolitical hotspots showing little sign of resolution, the environment remains supportive for safe-haven demand. Central banks are unlikely to step back from their buying programmes, particularly given the long-term diversification strategies now in place.
For investors, gold remains both a defensive hedge and, increasingly, a growth story in its own right. While the simultaneous rise of equities and bullion may not continue indefinitely, the drivers supporting gold look durable enough to keep sentiment positive into the final quarter.
Q4 Gold Outlook: Technical analysis and trade ideas
Gold heads into the final quarter of the year on a strong footing. Prices were up around 15% in Q3, marking the third straight quarterly gain. In fact, gold has now posted gains in seven of the past eight quarters – the only exception being Q4 2024, which ended more or less flat. This means that there is strong momentum behind gold, making it unsuitable for bearish strategies until the charts tell us otherwise. For that reason, we continue to prefer dip-buying in Q4.
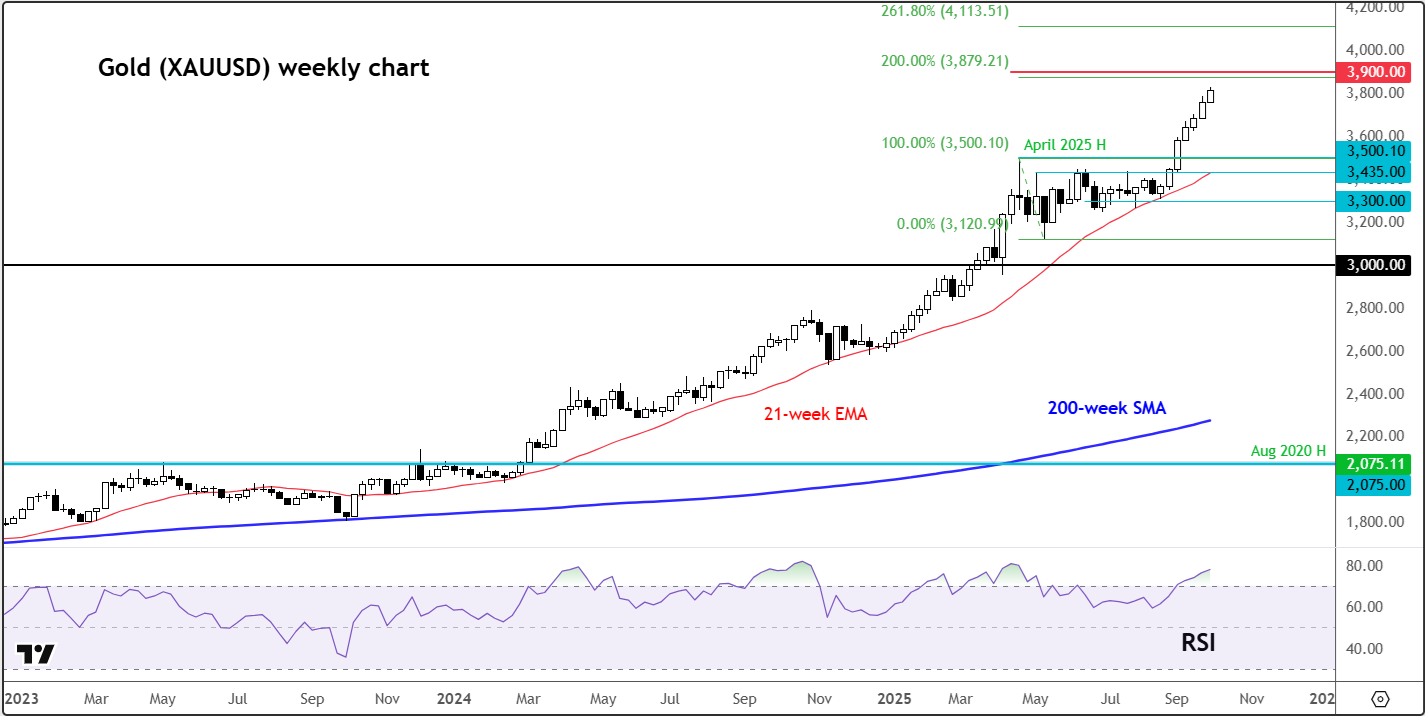
On the weekly chart, the metal had strung together six consecutive weekly advances at the time of writing. Unsurprisingly, momentum gauges are running hot. The RSI on the weekly timeframe was sitting deep in overbought territory, around 76, while the monthly reading was even more striking – above 90.0 following September’s breakout from a three-month consolidation.
Source: TradingView.com
Now, that kind of momentum can’t be ignored, but it does come with caveats. Overbought signals are flashing, yet the price action itself remains resolutely bullish. Without clear signs of reversal on the charts, it’s fair to treat these indicators as confirmation of what we already know: the trend has been very strong indeed.
What seems more likely is a modest pullback or even a period of consolidation at elevated levels – allowing momentum indicators to cool off over time rather than through a sharp correction. That would echo what we saw between April and September 2025, when months of sideways action ultimately set the stage for another leg higher.
From a levels perspective, key support to watch as we move through Q4 sits first at the old record peak near $3,500, reached back in April 2025. But there are a couple of more short-term term levels around $3,600 and $3,700, marking the now broken round handles. Below these levels, $3,435 is another interesting one to watch, marking the base of the Q3 breakout. A slip under that zone would make things more interesting, with the key line in the sand down at $3,300 – the last major swing low before the latest bull leg took off.
Meanwhile, resistance is thin on the ground with gold at record territory. The obvious round handles of $3,900 and the big one at $4,000 – where profit-taking could creep in – are now in focus. And we’re not all that far away.
So, the big question for Q4: can gold push on to that $4K milestone? Until we see a definitive reversal pattern, the playbook hasn’t changed despite extremely overbought technical levels. Dips continue to be bought in what remains a very strong and healthy bull market. Only a meaningful shift in fundamentals – say, a change in haven demand – would alter that stance. A weaker dollar, strong central bank buying, and dovish monetary policy have created a near-perfect environment for gold to thrive.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

US Dollar Technical Outlook: DXY Bulls Meet Resistance at Yearly Highs 10 1 2026
The U.S. Dollar has held firm despite fading Fed hike bets, but Friday’s payrolls could test the rally’s staying power.


Dow Jones forecast: Stock markets under pressure from multiple sources
When looking at the major tech-heavy US indices like the S&P 500 or the Nasdaq 100, you wouldn’t think that the stock market is particularly weak. Yet, beneath the surface, the market is far from healthy right now. Investors are evidently just piling into the big tech and AI names, and as a result, market breadth is deteriorating. Other indices like the small cap Russell 2000 and the Dow Jones are starting to reflect that weakness.

Nikkei breakout accelerates as yen weakness returns
Nikkei has started October with a powerful breakout, helped by renewed yen weakness and strong upside momentum

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.