

Indices weekly outlook: Can the DAX rebound turn into a reversal?
Global indices managed to bounce back towards the end of the week as risk mood improved following Thursday’s drop in bond yields and a slight decline in oil prices. But by late Friday afternoon, oil prices had made back most of Thursday’s drop and the bond markets remained under some pressure as European bourses closed for trading.
Share this:
Global indices managed to bounce back towards the end of the week as risk mood improved following Thursday’s drop in bond yields and a slight decline in oil prices. But by late Friday afternoon, oil prices had made back most of Thursday’s drop and the bond markets remained under some pressure as European bourses closed for trading. Earlier in the day on Friday, the German DAX index had bounced sharply after the turbulence of recent sessions. That rebound had improved the technical backdrop a bit ahead of the new trading week, but it is too early to conclude that the recent pressure has disappeared entirely. Much of the improvement still reflects a reduction in immediate risks rather than a fundamental change in the underlying backdrop. We maintain a cautious DAX outlook heading into the new week.
French fiscal risk premium and oil remain key risk factors
Some of the existing risks associated with European markets were still evident in the FX markets. The euro, for one, failed to stage a recovery on Friday against most major currencies, including the US dollar and Swiss franc, suggesting FX markets were still reluctant to scale back the French fiscal risk premium. That could become an increasingly important headwind for European equities next week if the situation deteriorates further.
Marine Le Pen’s pledge for significant fiscal tightening is unlikely, in our view, to be enough to turn the tide for French government bonds. Unless there are clearer signs of improvement in France’s fiscal position, European markets could remain vulnerable to renewed pressure from the French debt situation.
Energy prices are another risk factor for Europe. US President Donald Trump has said the US will not attack Iran before the 3 November midterms, but the oil market has been reluctant to fully unwind the geopolitical risk premium, with crude still trading above $100 a barrel despite an apparent improvement in Gulf supply.
That is hardly a favourable backdrop for the eurozone, where all of the major economies remain heavily reliant on energy imports. If oil prices stay elevated or move higher again, the resulting inflationary pressure could further complicate the outlook for both European growth and monetary policy.
Iranian Foreign Minister Araghchi said Tehran was reviewing Washington’s response and expected to reply within the next few days, so this remains an important risk for markets. Anything positive should boost stocks.
Week ahead: US inflation takes centre stage
The big event for markets next week will be US inflation.
September CPI is due on Wednesday, followed by PPI, retail sales, jobless claims and several regional manufacturing indicators on Thursday. CPI has been easing in recent months, standing at 2.4% year-on-year in August, and investors will be watching closely for any sign that the disinflationary trend is losing momentum.
A softer-than-expected inflation reading would probably reinforce the recent decline in yields and support risk assets, potentially giving the DAX another leg higher.
A hotter number, on the other hand, could quickly revive concerns about interest rates and put renewed pressure on bonds and equities.
The data will also be important for the dollar. Following the recent softer patch in US economic data, the greenback has lost some momentum, and another benign inflation report could reinforce that trend.
Central bank speakers will also be in focus. BoE Governor Bailey, ECB President Lagarde and BoC Governor Macklem are due to speak on Wednesday at the IMF and World Bank meetings in Bangkok, followed by SNB Chairman Schlegel on Thursday and Fed Governor Warsh on Friday.
Technical DAX outlook: potential double bottom?
The technical picture has improved, but the index still has something to prove.
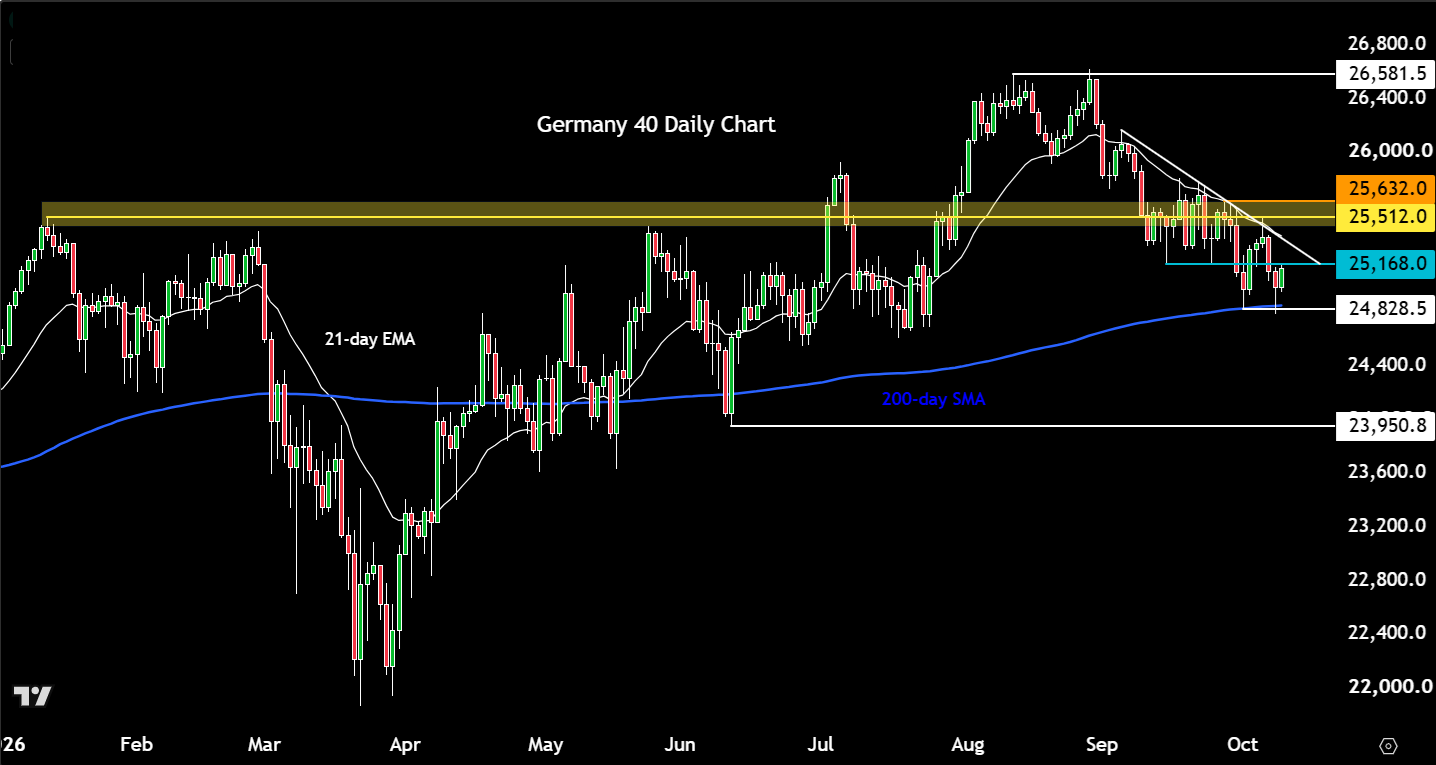
The DAX has formed what could become a double-bottom reversal pattern around its 200-day moving average, near the 24,800 area. This is an important technical zone, so the fact that buyers have managed to defend it is encouraging.
That said, the reversal is not confirmed yet.
The index still needs to break above the bearish trend line that has been defining the recent correction. A sustained move above that resistance would provide a much stronger signal that the sellers are losing control and potentially open the door to a broader recovery.
Conversely, failure to clear the trend line would leave the DAX vulnerable to another test of the 24,800 area. A decisive break below the 200-day average would invalidate the double-bottom setup and put the bears back in charge.
So, for now, the message from the chart is cautiously constructive rather than outright bullish.
Latest market news
Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Indices weekly outlook: Can the DAX rebound turn into a reversal?
Global indices managed to bounce back towards the end of the week as risk mood improved following Thursday’s drop in bond yields and a slight decline in oil prices. But by late Friday afternoon, oil prices had made back most of Thursday’s drop and the bond markets remained under some pressure as European bourses closed for trading.
Australian Dollar Short-term Outlook: AUD/USD Rebound Challenges September Downtrend 10 9 2026
Aussie is pressing a key trend barrier after rebounding from support, with next week’s CPI report poised to test the recovery.
DAX, Gold and Bitcoin forecast: Dollar falls, yields retreat as risk appetite returns
Markets went from risk off to risk on yesterday afternoon and we have since kicked on with some follow-up buying of stocks, gold and silver, while the dollar has also shown signs of weakness. Risk appetite turned positive after bond yields and oil prices both retreated yesterday.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.