



Japanese Yen Weakness is More than a Short-Term Currency Theme
USD/JPY has set a fresh 40-year high and that story isn’t over yet, as even another rate hike from the BoJ might not be enough to turn the trend. EUR/JPY and GBP/JPY are both setting up on their own merits.
Share this:
Japanese Yen Talking Points:
- USD/JPY has set a fresh 40-year high and traded above the 163.00 level.
- As looked at last Monday, pullbacks are opportunity in a strong bullish trend and so far, buyers have responded clearly to the below-target CPI and PPI releases of last week.
Its political intrigue stacked on top of economic consequence in USD/JPY, and there’s a storied history with interventions in the currency pair that takes on new meaning as yet another chapter is about to be written.
Fundamentals are not a perfect push point for price. They will influence supply and demand, to be sure, but really it’s only buying and selling that have a direct influence on price moves and while fundamentals will often have an impact on those flows, it’s not always perfect. Sometimes, exogenous factors come into play, particularly when an elongated trend that’s stretched with an imbalance of buyers suddenly gets a shock factor, leading to a quick rush of supply as bulls stampede for the exits.
This is what’s happened on intervention runs in USD/JPY and that story really goes back for about the past four years. But the backing fundamentals in the pair, they’ve remained bullish pretty much throughout, and for the Bank of Japan it seems that there’s little choice.
This can really be boiled back to a sociological issue. In Japan a dwindling and aging population brings the vexing issue of how to maintain economic growth with a smaller and smaller workforce. The ‘lost decades’ of Japan simply exacerbated the issue, with even lower birth rates, and lower growth rates, to the point where looking thirty or forty years in the future Japan could legitimately lose 30% of their population or more.
Assuming a loss of 33% of the citizenship, real GDP-per-capita would need to increase by 50% simply to keep the economy at its current size. And of course, there’s the topic of entitlements, as an aging population sees fewer and fewer taxpayers and more and more entitlement payments.
It’s a vexing problem, without a doubt, and this probably why there’s been so much political tumult in Japan over the past 20 years. Shinzo Abe gave a bit of hope, with a strategy buttressed by economic growth as produced by currency weakness. If Japan could effectively weaken the Yen, they could import economic growth by becoming more competitive with exports. This explains the more than 50% bump in USD/JPY between 2011 and 2015.
More recently, this also explains why the Bank of Japan has been so reticent to hike rates more aggressively, as choking off growth that’s taken so long to produce, and carries so much connotation, could present a real mess to encounter down-the-road.

There are consequences on either side of the matter. If inflation runs higher and continues to grow then that economic growth is offset by higher prices and, in-turn, a lower standard of living for Japan. There’s also the market response, such as we’ve seen, as higher levels of inflation eat into real returns and we’ll often see bond markets respond by selling debt, leading to higher yields and borrowing costs for the government.
But the other downside is already very well known, as lacking growth with a dwindling population produces political risk for Sanae Takaichi and, likely, a shorter tenure in the PM position. Of course, Takaichi doesn’t control interest rates, that’s the part of the Bank of Japan led by Kazuo Ueda, but the two aren’t entirely independent of each other, either.
The decision set seems clear, as far as I’m concerned, which is to err towards economic growth until absolutely forced to change. In the interim, about the best that can be done is the threat of an intervention to keep markets from turning a bullish rally in USD/JPY into a hockey stick.
But even interventions aren’t a clear-cut approach as it requires burning finite FX reserves to essentially buy down a trade that your very own monetary policy is encouraging. And this is why I’ve continued to look at intervention-fueled pullbacks as opportunities for trend continuation, and that’s now been the case for much of the past four years and increasingly so in 2026 trade.
USD/JPY Weekly Price Chart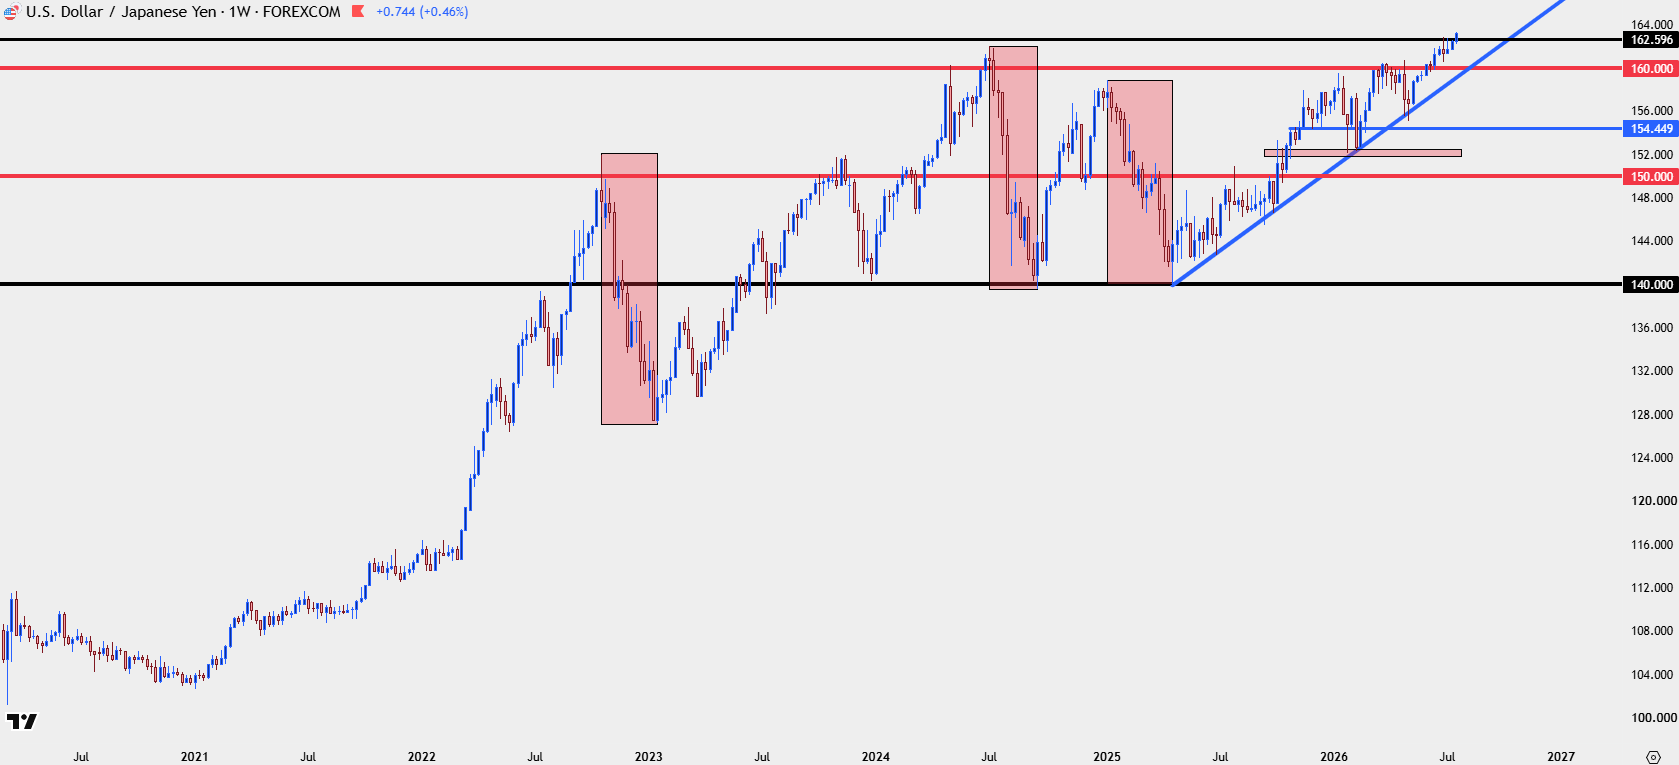
Chart prepared by James Stanley; data derived from Tradingview
USD/JPY Big Picture
It was the Plaza Accord from 1985 that really reset the scales. Before that, the US was dealing with the after-effects of stagflation and the high interest rates that were used to bring down inflation also kept USD/JPY spot rates high. And with a Yen so weak, companies like Honda or Toyota could feast on trade, which then made American products from Ford and GM a less competitive option.
USD/JPY went tumbling from a high of 262.80 in February of 1985 to a low of 79.75 ten years later, and a move of that magnitude can have massive consequences on an economy, and a population.
Economic growth slows, as do birth rates. Economic malaise sets in, which leads to political unrest. Just picture it from the perspective of an individual product, let’s say a car that costs $30,000 USD. In 1985 at a spot rate of even 250.00, an auto manufacturer in Japan can bring back 7.5 million Yen for selling a $30,000 car in the US. But at a spot rate of 80? Now they’re only bringing back 2.4 million Yen – a massive reduction of more than 60% for the same exact car sold ten years later. That auto manufacturer has been paying Japanese workers in Japanese Yen all along, and now they’re getting back 60% less on the same exact product for no fault of their own.
What are they going to do? Their options aren’t great, they have to raise prices while cutting costs, and even then, they likely aren’t going to remain margin positive. That missing capital then makes research and development or investing in economic growth an even more distant prospect because now they’re focused entirely on survival.
This is why Shinzo Abe took the country by storm 15 years ago, as he brought an idea to get that trend turning in the other direction. And once it did, USD/JPY jumped by 50% into the 120’s and along with it came something that the country of Japan hadn’t seen for almost twenty years at the time: hope.
USD/JPY Monthly Chart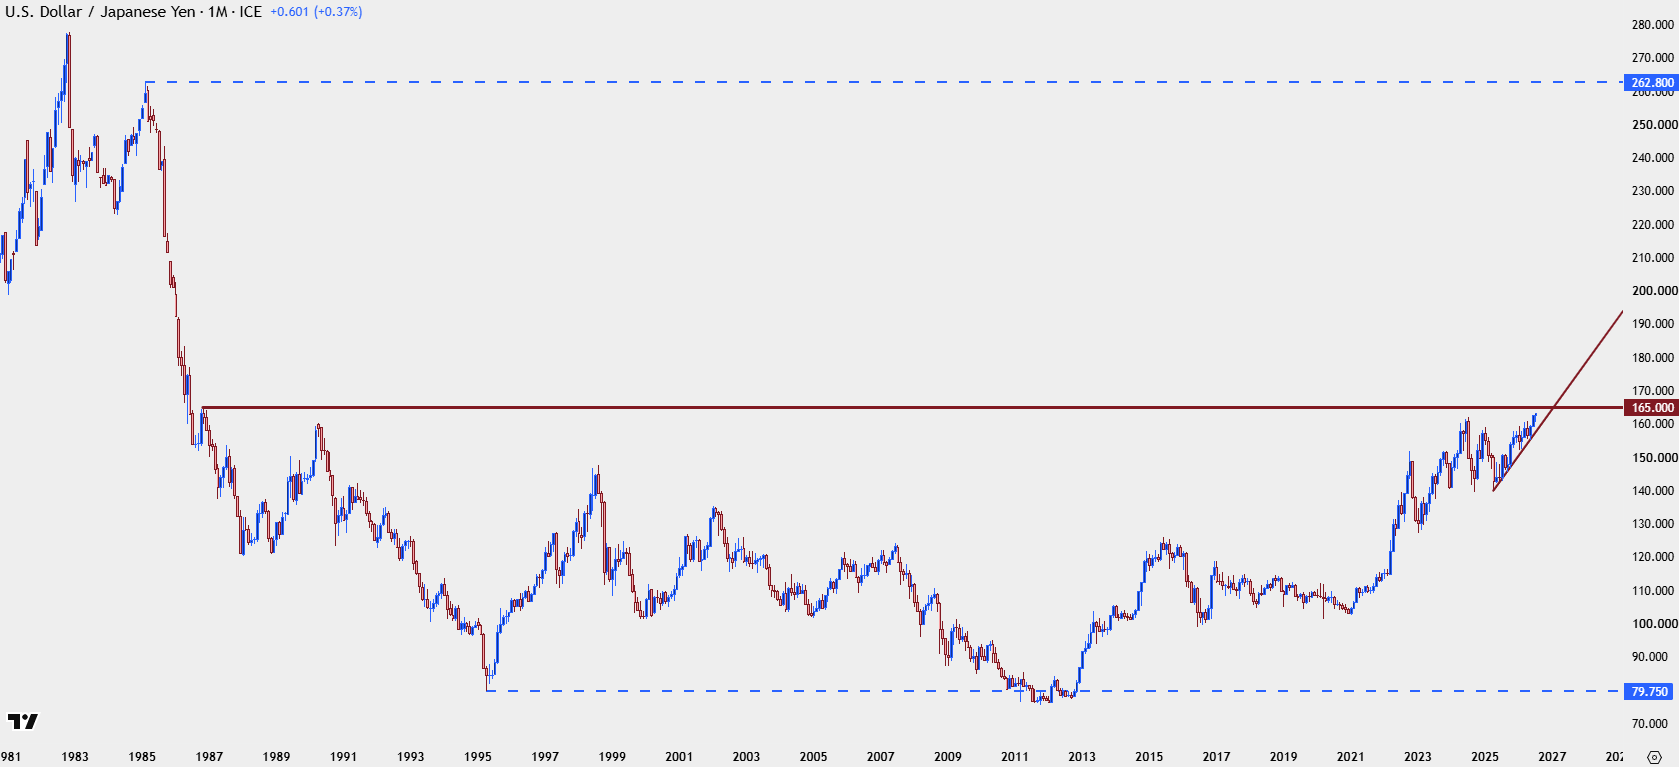
Chart prepared by James Stanley; data derived from Tradingview
USD/JPY The Drive Forward
At this point I think there’s little reason to question the trend and as explained above, I think there’s valid reason for both Japanese policymakers and the Bank of Japan to bias towards growth initiatives.
But – this does not mean that I want to just chase trends wildly, as I noted above fundamentals aren’t a perfect push point for price, even if they do help to set the prevailing trade winds.
I looked at this last Monday in an attempt to pre-empt the breakout, looking for counter-trend data to allow for a pullback, and this is what we saw on that Tuesday with the CPI print. I talked about that in-depth in the webinar that day, even sharing what I was looking for from a price action perspective to work with that move.
But now that we have the fresh breakout and the 40-year highs, another urge of caution should be set, and, instead, looking for veiled or even direct threats of intervention to lead to a pullback that could bring higher-low supports into play. As looked at in yesterday’s webinar, 162.84 was a prior high and was now setting up as support potential. That’s already helped to elicit a bounce, but it’s the level just below it as prior resistance around the 162.50 area that perhaps sets up even more attractively.
If we do get a legitimate push of USD-weakness, 161.95 and 161.65 are the levels of note below that, but in that instance, there may be more amenable pastures elsewhere to look for Japanese Yen weakness, such as EUR/JPY or GBP/JPY.
USD/JPY Four-Hour Chart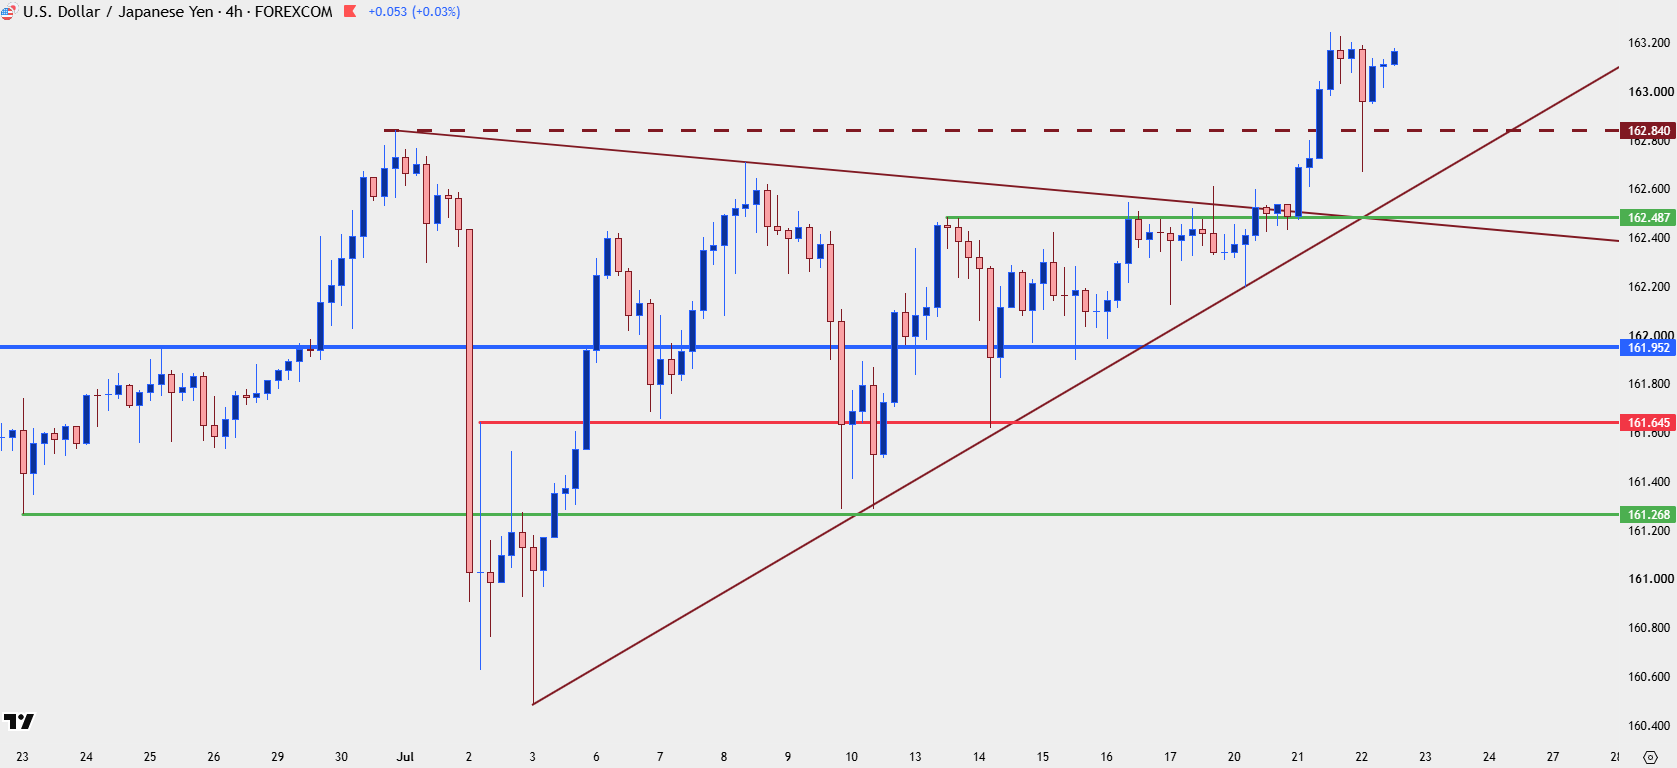
Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Market Analyst, Global Macro
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Canadian Dollar Technical Outlook: USD/CAD Seven-Day Rally Tests Major Resistance 9 29 2026
USD/CAD is pressing into a major technical barrier after an extended advance, raising the risk for price inflection as momentum stretches.

RBA delivers 25bp hike, Bullock now the main event
The RBA delivered the expected 25bp hike, but Bullock’s press conference now looms as the bigger volatility risk for AUD/USD and the ASX 200.


EUR/USD, USD/JPY Outlook: Oil, yields and an FX identity crisis
Crude oil is setting the tone across rates and FX, leaving EUR/USD vulnerable and USD/JPY caught between higher Treasury yields and the growing threat of intervention
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.