


Market Brief Tariff cheer eclipses Italy Hong Kong for now
What a difference a tariff delay announcement can make
Share this:
Stock market snapshot as of [13/8/2019 7:24 PM]
- What a difference an unexpected announcement of a delayed imposition of tariffs can make (even though there’s no guarantee the postponement will become a suspension)
- Nevertheless, relief and cheer are holding, hours after the U.S. Office of the Trade Representative (USTR) said that the additional import duty on certain Chinese imports announced by President Donald Trump last month, would now be delayed till 15th December from an initial date of 1st September
- There’s little detail from Washington so far on what motivated the change, though China’s equivalent of the USTR said that it will hold talks with U.S. counterparts over the next two weeks. With a cocktail of pressures remaining on risk-seeking, including Hong Kong, which still simmers, and the real possibility of another reversal in Washington-Beijing relations, Tuesday’s stock market rebound will probably require solid further impetus to extend beyond the next 24 hours
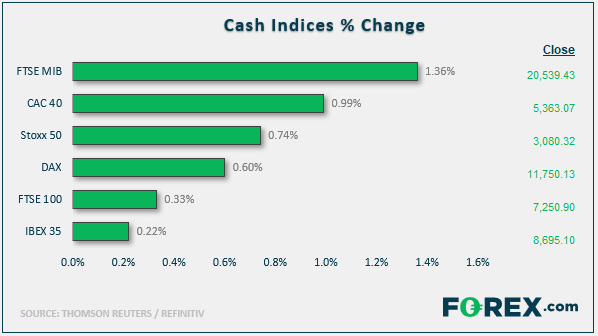
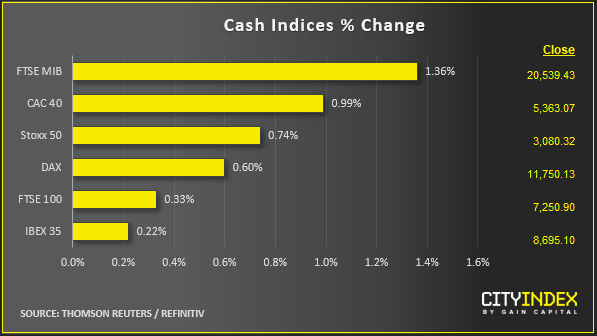
- Italy’s political turmoil, is another case in point, though the main stock gauge there rose more than 1% as banks swung higher. The Rome parliament’s failure to set a date to debate an early election, as expected, after Deputy Prime Minister Matteo Salvini’s demand, offers the country’s volatile bond markets some temporary respite
- For U.S. investors, rising core CPI, suggests a quicker return to the Fed’s 2% target than expected, which a negative for further rate cuts. As such, current euphoria may face a wake-up call on the policy easing front too as the most up to date U.S. readings continue to roll in. July Retail Sales are due on Thursday
Stocks/sectors on the move
- A broad-based rally leaves few U.S. sectors without strong gains at last look, 10 of the S&P 500’s 12 major demarcations are posting gains of at least 1%. Technology shines the most with a 2.4% jump, led by Hardware which surges almost 4% on the back of a 4.6% advance by Apple. The defensive Real Estate and Utilities sectors also rose, though sharply underperformed with fractional gains only.
- With oil prices also reviving, on trade hopes, oil majors also contribute a solid chunk to Wall Street’s upside
FX snapshot as of [13/8/2019 7:24 PM]
FX markets
- FX trading has also been upended by the latest U.S. change of heart, with ‘risk-on’ currencies quickly taking back the initiative from ‘safe-haven’ ones like the yen and franc, whilst keeping the toppy dollar on the backfoot
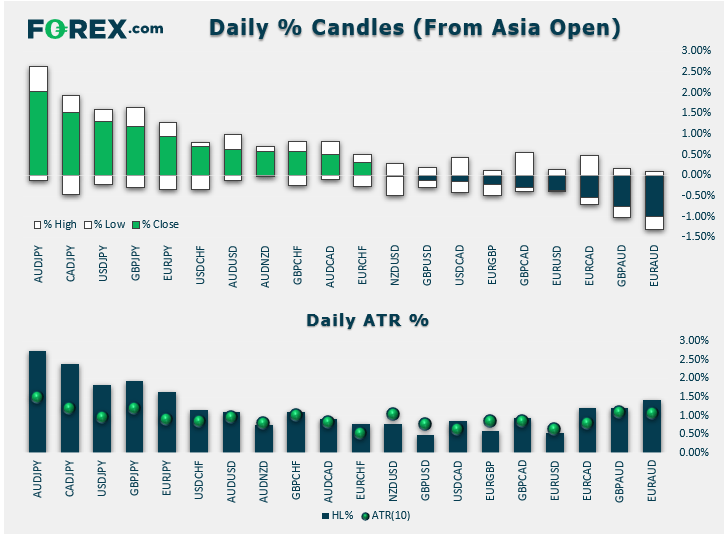
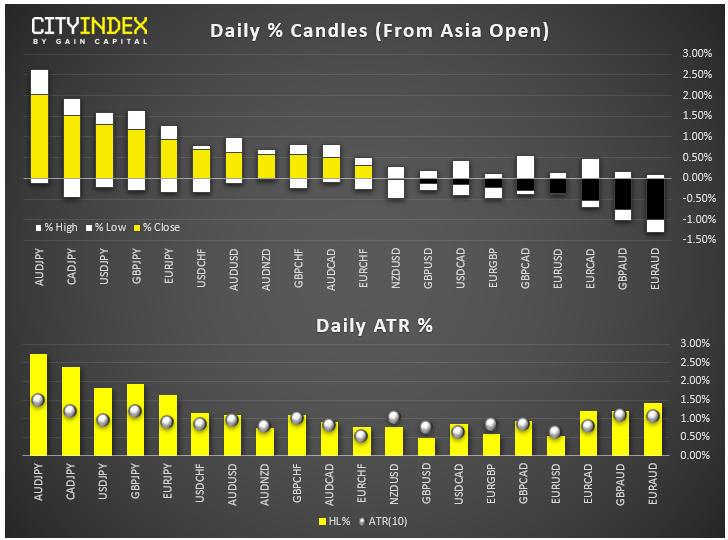
- The euro and the Aussie shone at last check with AUD/JPY holding a 2% gain measured since the Asia open. Sterling also showed signs of retaining gains from a bounce from multi-year lows, as it also rises against the yen with help from better than expected wage data
- Despite Tuesday's risk-off bounce across markets, underlying risk aversion means traders may be still be underestimating possible further downside for the Hong Kong Dollar and Sterling, even after recent sharp volatility
- The Aussie also drove the euro sharply lower, whilst the single currency also relinquished earlier gains against the dollar
Upcoming corporate highlights

AMC: after market close
Upcoming economic highlights
Stock market snapshot as of [13/8/2019 7:24 PM]
- What a difference an unexpected announcement of a delayed imposition of tariffs can make (even though there’s no guarantee the postponement will become a suspension)
- Nevertheless, relief and cheer are holding, hours after the U.S. Office of the Trade Representative (USTR) said that the additional import duty on certain Chinese imports announced by President Donald Trump last month, would now be delayed till 15th December from an initial date of 1st September
- There’s little detail from Washington so far on what motivated the change, though China’s equivalent of the USTR said that it will hold talks with U.S. counterparts over the next two weeks. With a cocktail of pressures remaining on risk-seeking, including Hong Kong, which still simmers, and the real possibility of another reversal in Washington-Beijing relations, Tuesday’s stock market rebound will probably require solid further impetus to extend beyond the next 24 hours
- Italy’s political turmoil, is another case in point, though the main stock gauge there rose more than 1% as banks swung higher. The Rome parliament’s failure to set a date to debate an early election, as expected, after Deputy Prime Minister Matteo Salvini’s demand, offers the country’s volatile bond markets some temporary respite
- For U.S. investors, rising core CPI, suggests a quicker return to the Fed’s 2% target than expected, which a negative for further rate cuts. As such, current euphoria may face a wake-up call on the policy easing front too as the most up to date U.S. readings continue to roll in. July Retail Sales are due on Thursday
Stocks/sectors on the move
- A broad-based rally leaves few U.S. sectors without strong gains at last look, 10 of the S&P 500’s 12 major demarcations are posting gains of at least 1%. Technology shines the most with a 2.4% jump, led by Hardware which surges almost 4% on the back of a 4.6% advance by Apple. The defensive Real Estate and Utilities sectors also rose, though sharply underperformed with fractional gains only.
- With oil prices also reviving, on trade hopes, oil majors also contribute a solid chunk to Wall Street’s upside
FX snapshot as of [13/8/2019 7:24 PM]
FX markets
- FX trading has also been upended by the latest U.S. change of heart, with ‘risk-on’ currencies quickly taking back the initiative from ‘safe-haven’ ones like the yen and franc, whilst keeping the toppy dollar on the backfoot
- The euro and the Aussie shone at last check with AUD/JPY holding a 2% gain measured since the Asia open. Sterling also showed signs of retaining gains from a bounce from multi-year lows, as it also rises against the yen with help from better than expected wage data
- Despite Tuesday's risk-off bounce across markets, underlying risk aversion means traders may be still be underestimating possible further downside for the Hong Kong Dollar and Sterling, even after recent sharp volatility
- The Aussie also drove the euro sharply lower, whilst the single currency also relinquished earlier gains against the dollar
Upcoming corporate highlights
AMC: after market close
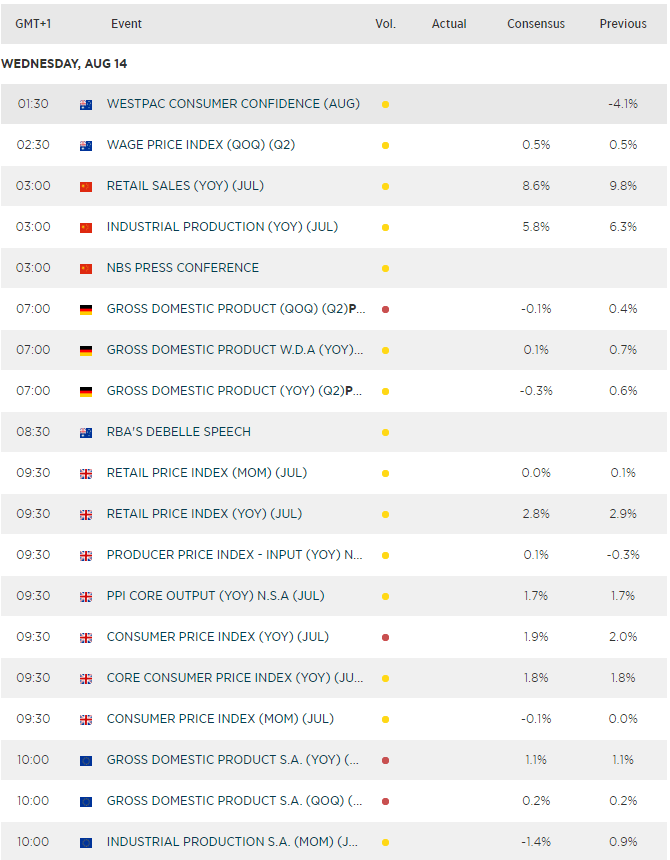
Upcoming economic highlights
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Crude Oil, DXY Outlook: Geopolitical Risks Halt Sell-Offs in the Dollar and Oil
The U.S. Dollar Index, Brent and WTI are rebounding from key support levels and oversold conditions after steep sell-offs. U.S.–Iran tensions, inflation risks and rate expectations remain in focus.


Silver's bullish breakout case builds as bond yields retreat
The Democratic blue wave has sent crude and Treasury yields sharply lower, improving the outlook for precious metals. With gold already breaking higher, could silver be next?
Crude Oil Prices Fall, What the U.S. Midterms Mean for Brent
Crude oil prices have pulled back more than 11% from October highs, in line with U.S.-Iran negotiation hopes and shifting U.S. midterm expectations.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.