



Market Brief Treading Water Ahead Of ISM Services PMI
A summary of news and snapshot of moves from today’s Asia session.
Share this:

FX Brief:
- Ahead of trade talks, White House advisor Peter Navarro has listed “seven deadly sins” from China; Cyber attacking, IP theft, forced technology transfer, goods trade balance, China state-owned subsidies, FX manipulation and fentanyl shipped to “kill countless Americans”.
The US are to hit Europe with a 10% tariff on European-made Airbus plan and 25% on French wine, Scotch and Irish Whiskey and continental cheese. - Fed Williams see’s monetary policy as “in the right place”, although the outlook for the economy is mixed. On tariffs he sees risks to the economy as relatively modest.
- Australian exports fell -3% in September and weighed on their surplus. Yet it still touched a marginal 2-day high following yesterday’s bullish doji at multi-year lows.
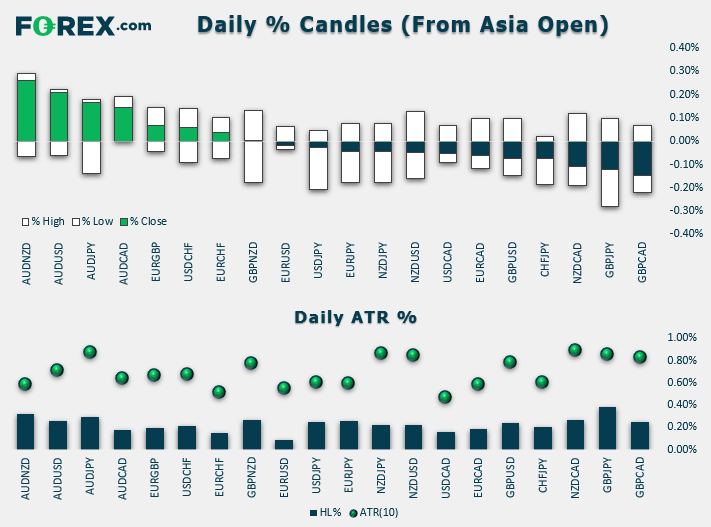
- Minor ranges overall, AUD is the strongest major, elsewhere majors remain in low-ranging holding patterns.
Equity Brief:
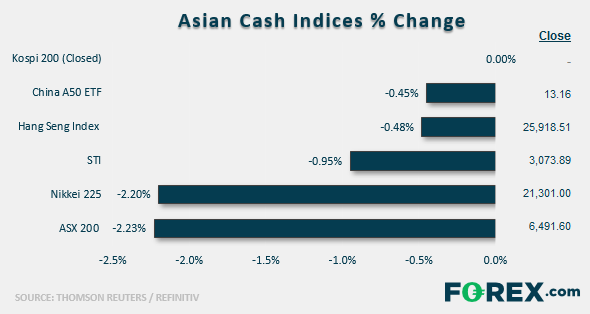
- Asian stock markets have continued to see further downside, taking the cue from another bloodbath seen overnight in the U.S. stock markets. In additional, the U.S. benchmark stock index, S&P 500 has seen its first back to back drop of more than 1% in 2019. South Korea’s Kospi 200 has managed to “escape” the bleeding as its stock exchange is closed today for a public holiday.
- One of the worst performers as at today’s Asian mid-session is Japan’s Nikkei 225. It shed 2.20% in line with a stronger JPY where the USD/JPY hit a 3-day low of 107.00. Also, latest data on Japan’s services sector for Sep has indicated a slow-down in growth over Aug where the Jibun Bank Japan Services PMI dropped to 52.8 from 53.3 seen in August.
- The slowdown in growth seen in Japan’s services sector, the main driving force so far in order to maintain a positive economic growth to offset the negative impact from a 9-month export slump is a concern to market participants. The government has just imposed an increase in sales tax to 10% from 8% that came into effect on 01 Oct which can lead to a slowdown in future domestic consumption where the services sector is dependent on.
- Australia’s ASX 200 also sees further downside as it tumbled by -2.23% to print a 4-week low of 6475 led by technology and energy stocks that has declined by -2.50% and -3.02% respectively.
- Adding salt to the on-going negative sentiment, the U.S. administration has decided to hike tariffs on European produces; 10% tariffs on European aircrafts and 25% duties on other goods such wines and cheese as punishment for illegal EU aircraft subsides.
- After a 2-day decline of 3.5% in the S&P 500 to print a low of 2875 seen yesterday, the S&P 500 E-Mini futures has traded sideways in a tight range of 9 points so far in today’s Asian session.
Up Next
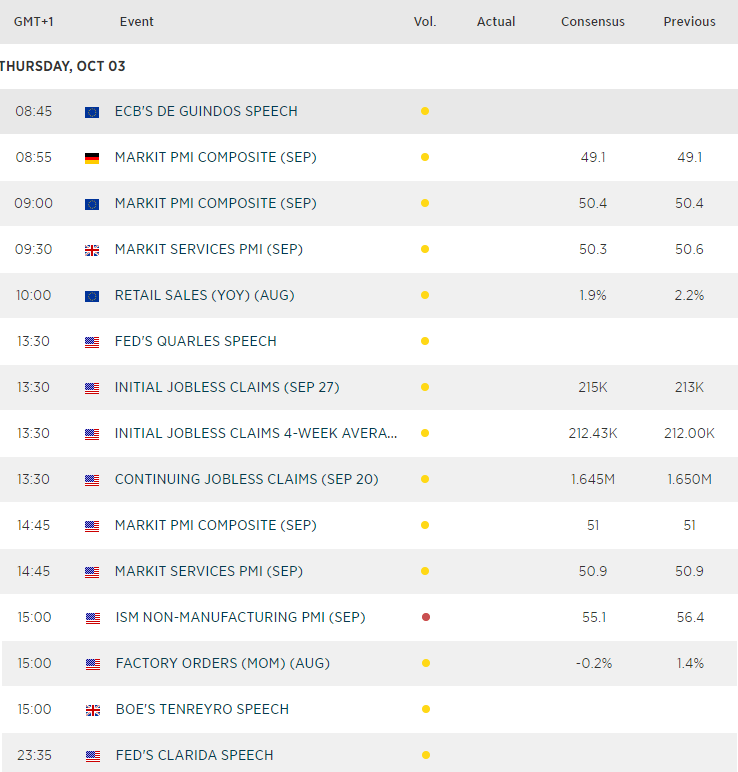
- Final PMI reads for France, Germany and the Eurozone are released early in the European session. Major revisions aren’t expected but if they are lowered, it simply feeds into the negative sentiment regarding global growth, Keep Euro crosses and DAX on your radar.
- However, the highlight could be ISM’s non-manufacturing PMI for the US. Given we saw ISM manufacturing tank to a 10-year low this week, Non-manufacturing (NM PMI) could receive extra scrutiny. Although NM PMI has remained expansive since the GFC, a slower rate of expansion points towards a broader slowdown and could exacerbate risk-ff sentiment if it slows enough later today. Therefor a weak print could weigh on USD and US indices.
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.
FX Brief:
- Ahead of trade talks, White House advisor Peter Navarro has listed “seven deadly sins” from China; Cyber attacking, IP theft, forced technology transfer, goods trade balance, China state-owned subsidies, FX manipulation and fentanyl shipped to “kill countless Americans”.
The US are to hit Europe with a 10% tariff on European-made Airbus plan and 25% on French wine, Scotch and Irish Whiskey and continental cheese. - Fed Williams see’s monetary policy as “in the right place”, although the outlook for the economy is mixed. On tariffs he sees risks to the economy as relatively modest.
- Australian exports fell -3% in September and weighed on their surplus. Yet it still touched a marginal 2-day high following yesterday’s bullish doji at multi-year lows.
- Minor ranges overall, AUD is the strongest major, elsewhere majors remain in low-ranging holding patterns.
Equity Brief:
- Asian stock markets have continued to see further downside, taking the cue from another bloodbath seen overnight in the U.S. stock markets. In additional, the U.S. benchmark stock index, S&P 500 has seen its first back to back drop of more than 1% in 2019. South Korea’s Kospi 200 has managed to “escape” the bleeding as its stock exchange is closed today for a public holiday.
- One of the worst performers as at today’s Asian mid-session is Japan’s Nikkei 225. It shed 2.20% in line with a stronger JPY where the USD/JPY hit a 3-day low of 107.00. Also, latest data on Japan’s services sector for Sep has indicated a slow-down in growth over Aug where the Jibun Bank Japan Services PMI dropped to 52.8 from 53.3 seen in August.
- The slowdown in growth seen in Japan’s services sector, the main driving force so far in order to maintain a positive economic growth to offset the negative impact from a 9-month export slump is a concern to market participants. The government has just imposed an increase in sales tax to 10% from 8% that came into effect on 01 Oct which can lead to a slowdown in future domestic consumption where the services sector is dependent on.
- Australia’s ASX 200 also sees further downside as it tumbled by -2.23% to print a 4-week low of 6475 led by technology and energy stocks that has declined by -2.50% and -3.02% respectively.
- Adding salt to the on-going negative sentiment, the U.S. administration has decided to hike tariffs on European produces; 10% tariffs on European aircrafts and 25% duties on other goods such wines and cheese as punishment for illegal EU aircraft subsides.
- After a 2-day decline of 3.5% in the S&P 500 to print a low of 2875 seen yesterday, the S&P 500 E-Mini futures has traded sideways in a tight range of 9 points so far in today’s Asian session.
Up Next
- Final PMI reads for France, Germany and the Eurozone are released early in the European session. Major revisions aren’t expected but if they are lowered, it simply feeds into the negative sentiment regarding global growth, Keep Euro crosses and DAX on your radar.
- However, the highlight could be ISM’s non-manufacturing PMI for the US. Given we saw ISM manufacturing tank to a 10-year low this week, Non-manufacturing (NM PMI) could receive extra scrutiny. Although NM PMI has remained expansive since the GFC, a slower rate of expansion points towards a broader slowdown and could exacerbate risk-ff sentiment if it slows enough later today. Therefor a weak print could weigh on USD and US indices.
Matt Simpson and Kelvin Wong both contributed to this article
Data from Refinitiv. Index names may not reflect tradable instruments and not all markets are available in all regions.

Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.