


Markets Rally as Apple Soars, Gold Hits New High
Apple's best week since 2020 helped lift US equities, while gold surged past $3,500 amid new tariffs on semi-processed bars. Nvidia and AMD struck a unique deal to preserve China sales, boosting chip optimism. Markets now look to today's CPI and German ZEW data for direction. Bitcoin nears $122K, and central bank policy remains in focus ahead of the Trump-Putin summit on August 15.
Share this:

1. US Equities & Markets
- Nasdaq
- Closed at a record high for the second day in a row on Friday.
- Driven by tech strength and rate cut optimism.
- All three major US indexes posted solid weekly gains.
- Apple
- Shares rose 4.2% Friday, 13.3% weekly — best week since 2020.
- Boosted by Trump’s announcement of $100B additional investment, total US commitment now $600B over four years.
- Sector Performance
- Tech and Communications led; both closed at record highs.
- Gilead Sciences jumped 8.3% on raised full-year outlook.
- Real Estate, Utilities, Industrials lagged.
- Rate Cut Expectations
- Softer economic data reinforces dovish outlook.
- Markets now price in a 90% chance of a September Fed rate cut.
- Trump named CEA Chair Miran as interim Fed governor (replacing Kugler).
2. Global Equity Markets
- Japan
- Nikkei futures hit 42,380, nearing all-time high (42,426) despite a holiday.
- Nikkei PE ratio at 19, vs 22 for S&P 500 and 33 for Nasdaq (premium driven by AI exposure).
3. AI Chip Export Policy
- NVIDIA & AMD
- Both agreed to give the US government 15% of China AI chip revenue in exchange for export licenses.
- US licensed NVIDIA after CEO Huang met Trump.
- Could dampen market sentiment and impact margins.
- China's Position
- Wants US export restrictions relaxed as part of trade talks.
4. Commodities
- Gold
- Hit record high of $3,534/oz (Dec contract) on COMEX.
- Triggered by US Customs decision to impose tariffs on semi-processed gold bars.
- Switzerland most affected — major source of re-melted bars.
- US signaled tariffs may not be enforced, calming market concerns.
- Crude Oil
- Futures remained subdued after prior declines.
- Market awaiting outcome of Trump-Putin meeting on Friday.
- Copper
- Traded indecisively amid mixed inflation data from China.
5. Crypto
- Bitcoin
- Climbed to just below $122K, before paring gains.
- Part of a broader crypto rally.
- Ethereum broke through quadruple top and gaining momentum.
6. Central Bank & Economic Policy
- Fed’s Bowman
- Core PCE inflation may be closer to 2% target than data shows.
- Three rate cuts still forecasted for 2025.
- Warns of delayed action leading to labour market damage.
- Fed Chair Search
- Trump team expands shortlist: includes James Bullard and Marc Sumerlin (ex-Bush adviser).
- E.J. Antoni under consideration to lead Bureau of Labor Statistics.
7. Geopolitics & Trade
- Trump-Putin Meeting
- Confirmed for August 15th.
- Follow-up to envoy Witkoff’s prior diplomatic success.
- Trump on China Soybeans
- Called on China to quadruple soybean orders.
- Claims US farmers offer the “most robust soybeans”.
- Trump on Marijuana
- Administration considering reclassifying marijuana as less dangerous, potentially opening marijuana companies to banking system and amplifying margin of entry.
- DC Security
- National Guard activation expected; final role/number pending.
8. Russia-Ukraine Conflict
- US Diplomacy
- VP Vance: US coordinating Zelensky-Putin meeting timing.
- Trump considering tariffs on China for buying Russian oil.
- Putin’s Demands
- Ukraine must cede Donetsk, Luhansk, Crimea for ceasefire.
- Requests full Ukrainian withdrawal from eastern Donetsk.
9. Middle East
- Israel-Gaza Conflict
- Netanyahu says Israel will “complete the job” against Hamas.
- Gaza offensive focuses on two final Hamas strongholds.
- Netanyahu discussed plan with President Trump.
- Qatar Mediation
- US envoy Witkoff met with Qatar’s PM to discuss hostage release and conflict resolution.
- Australia & Palestine
- Australia to recognize Palestine at UN in Sept, conditional on PA commitments.
- PM Albanese criticizes Israel’s actions and hints at further regional recognition.
- New Zealand also considering formal recognition.
- Iran & Syria
- IAEA official to visit Iran to plan nuclear cooperation framework.
- Jordan to host trilateral meeting (Jordan-Syria-US) on Syria’s rebuilding.
10. Key Data Releases – August 12, 2025 (CET)
|
Time |
Country |
Indicator |
Prior |
Forecast |
|
06:30 |
AUD |
RBA Interest Rate Decision (Aug) |
3.60% |
3.85% |
|
11:00 |
EUR |
German ZEW Current Conditions (Aug) |
-63.0 |
-59.5 |
|
11:00 |
EUR |
German ZEW Economic Sentiment (Aug) |
39.7 |
52.7 |
|
14:30 |
USD |
CPI (MoM) (July) |
0.2% |
0.3% |
|
14:30 |
USD |
CPI (YoY) (July) |
2.8% |
2.7% |
11. DAX Technical Analysis – 4 hour chart
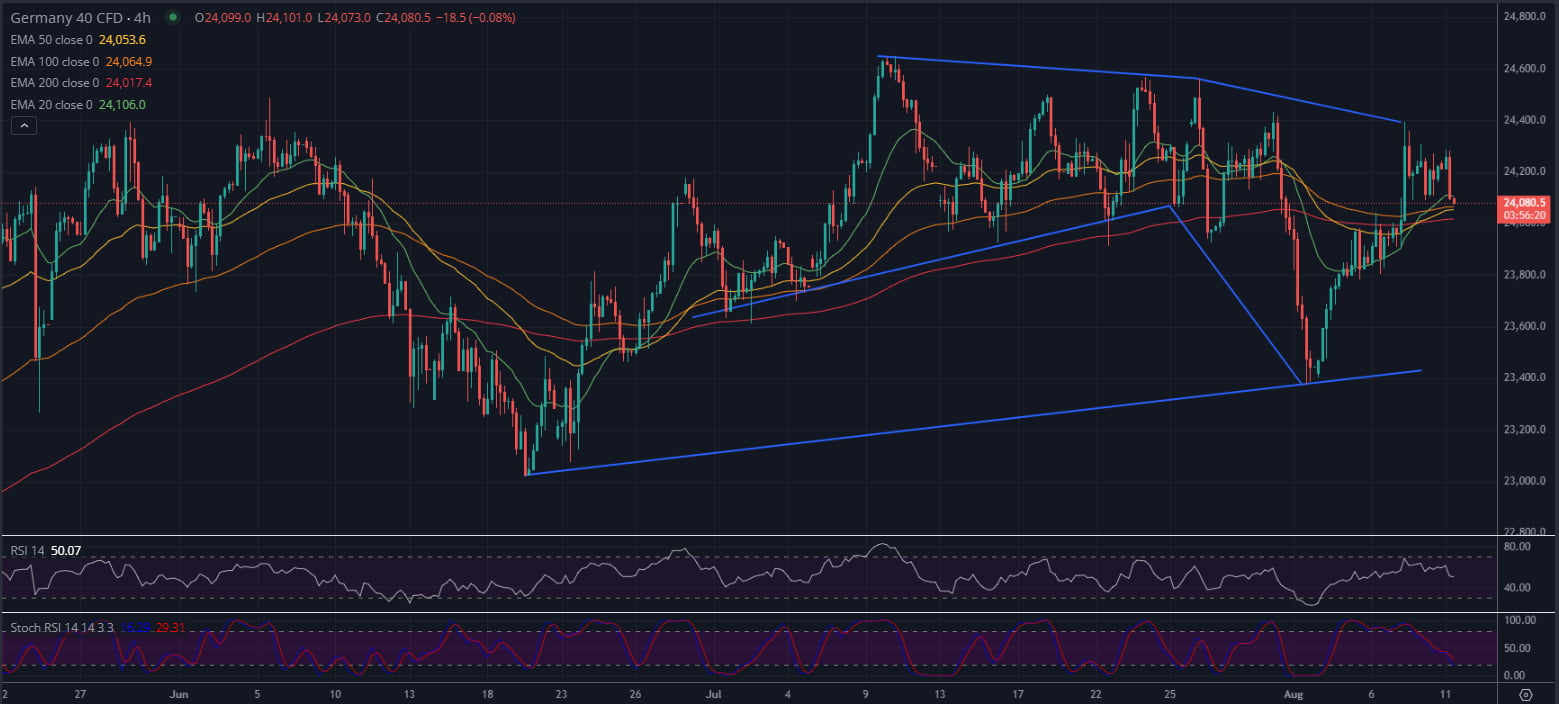
The Germany 40 (DAX) is showing renewed bullish momentum following a sharp rebound from its recent lows near 23,300. The index had previously broken down from a rising wedge pattern, triggering a deep selloff, but has since regained its footing with a strong series of green candles. This rally is now pushing price back above key EMAs (20/50/100/200), with all of them converging around 24,000–24,050, reinforcing the importance of this zone as a support-turning-resistance. The RSI is trending upward toward 60, while the Stoch RSI is nearing overbought levels, suggesting momentum remains on the side of the bulls in the short term.
However, there are signs of caution to consider. Price is still within a broader descending triangle, capped by a descending resistance trendline connecting the July and early August highs. Until the DAX breaks cleanly above 24,400–24,500, the overall structure remains vulnerable to another swing lower. That said, given the strength of the bounce and the reclaiming of moving averages, the bias leans slightly bullish, with a potential upside retest of the upper range likely — especially if macro sentiment remains supportive. A failure to hold 24,000 could invalidate this recovery and put pressure back on the 23,600–23,700 area.
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P 500 forecast: Stocks extend drop as correction risks grow
US and global equity markets have extended Wednesday’s sell-off, with Wall Street opening lower after a weak handover from Asia and Europe. The deterioration in risk appetite has been spreading across global markets. The dollar was firmer, Treasury yields were holding onto yesterday’s gains, while gold, silver and bitcoin were all under pressure alongside equities and major currencies.

GBP/USD, DAX Forecast Two trades to watch 220926
GBP/USD struggles as UK government borrowing exceeds forecasts, putting pressure on Healey ahead of the Budget. DAX eases back after yesterday's gains as oil prices and political headwinds rise.

ASX 200 Rebound Stalls Despite Wall Street Surge
The ASX 200 rebound is struggling for traction despite a powerful Wall Street rally, leaving 8800 resistance and downside risks in focus.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.