




Pre-FOMC USD Price Action Setups: EUR/USD, USD/JPY
Tomorrow brings a vitally important Federal Reserve rate decision and the driver will probably be the bank’s dot plot matrix as the Fed updates their projections for the rest of the year.
Share this:
USD, EUR/USD, USD/JPY Talking Points:
- Tomorrow brings a quarterly rate decision from the Federal Reserve at which the FOMC will provide updated guidance and projections.
- The big question is whether the Fed is still expecting to cut rates 50 basis points this year as they had last said in their projections in March. Since then, inflation has fallen more than they had expected but labor markets have remained stronger, thereby removing some of the possible motivation to cut. The tariff topic continues to loom large as multiple members of the bank fear of a supply shock, which could lead to higher inflation.
- This is an archived webinar and you’re welcome to join the next live event. Click here to register.
Markets continue to expect the Fed to cut by 50 basis points or more into the end of the year and this pretty much aligns with the bank’s forecasts from the March meeting when they last issued updated projections. With the ECB sounding finished with rate cuts, this has helped to push additional USD weakness as the Dollar has broken down to fresh three-year-lows.
As shown in the video, USD is testing some pretty big support on a bigger picture basis, and the potential for a turn still remains – but for that to come to fruition we’re likely going to need to hear the Fed push rate cut expectations towards 2026 or 2027.
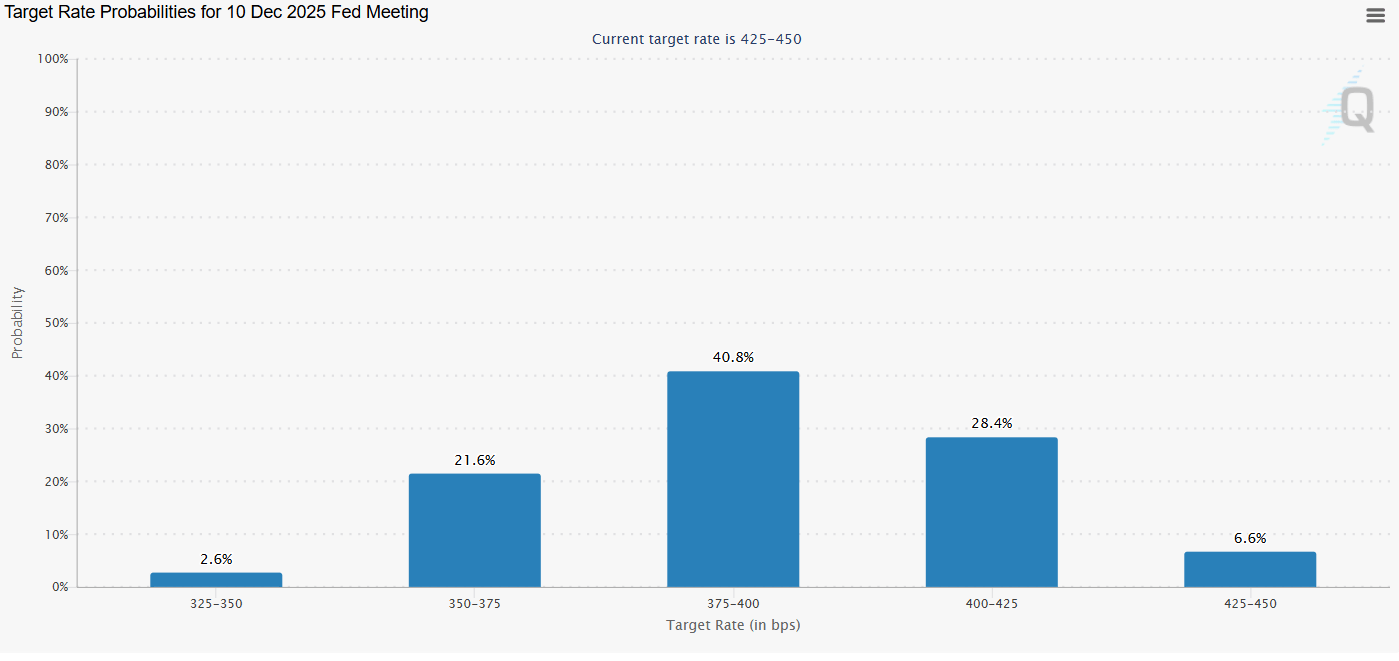
As of this writing, markets are expecting the FOMC to cut rates by 50 basis points by the end of the year to a 65% probability.
Rate Probabilities into End of 2025
 Data derived from CME Fedwatch
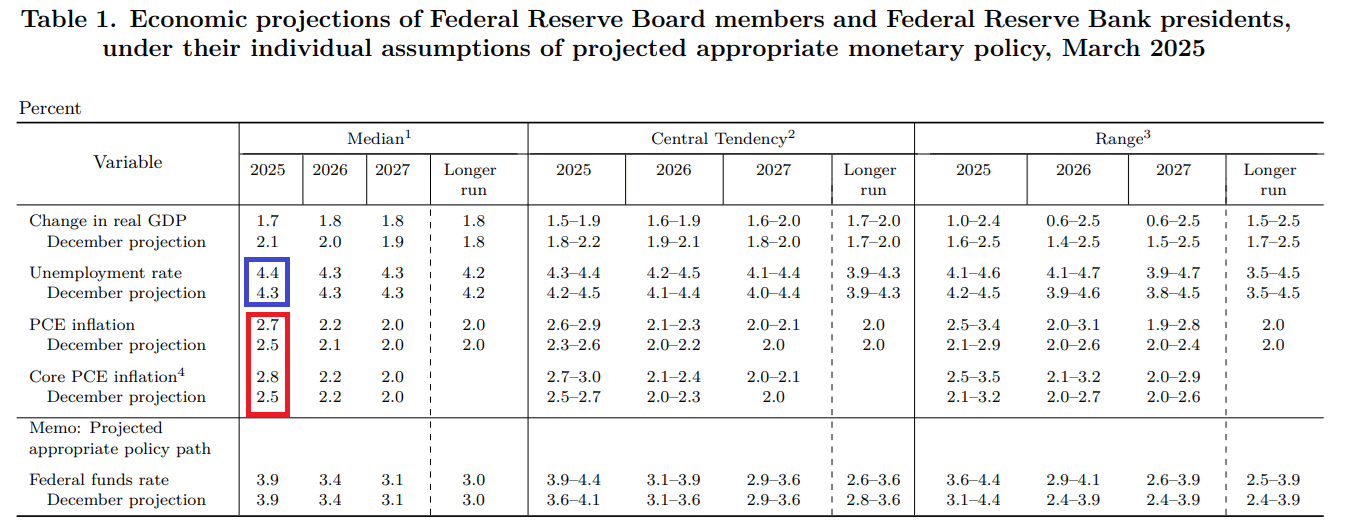
Supporting the argument for FOMC cuts is the fact that inflation is well-below what the Fed was last projecting. In the March update, the FOMC said that they were looking for PCE at 2.7% this year, with Core PCE at 2.8%.
At the last update of that data point the numbers were far below that, with PCE at 2.1% and Core PCE at 2.5%. So, from that perspective, the Fed has an open door to cut rates as inflation isn’t as problematic as they were expecting.
On the other side of the argument, however, the labor market has held up a bit better than they were expecting, with the unemployment rate most recently printing at 4.2% and the Fed was looking for that to go up to 4.4% this year. So, the perceived need for rate cuts isn’t as high as the labor market has held up a bit better.
The outside addition to the argument and something we’ve heard multiple Fed members opine on recently is the impact of tariffs. This has seemed to be an overriding concern around the FOMC as the tariff topic remains a very big part of President Trump’s administration, and while some progress has been made on some fronts, it continues to add a healthy amount of uncertainty to the equation.
So the big question here is whether the Fed forges ahead with their 50 bp expectation for rate cuts this year despite the labor market not looking especially bad, and with the risk of additional inflation as produced by tariffs.
FOMC Data Projections from the March Meeting
 Data derived from The Federal Reserve; data derived from Tradingview
USD
The US Dollar is grasping on to some long-term supports and chasing the Dollar lower could be a challenge here. I think for bearish outcomes the Fed would need to lean pretty heavily in setting the stage for rate cuts in September when they next provide updated guidance.
The tariff risk could complicate that but with inflation coming in relatively low and recent dimming of data points like retail sales, this has to be entertained a possibility.
There’s also the USD/JPY element, from which the long-term carry trade continues to drive flows around the USD and I’ll look at that a little lower in this article.
Also of note is the RSI divergence showing on the weekly, where last week’s lower-low on price matches with a higher-low via RSI.
U.S. Dollar Weekly Price Chart
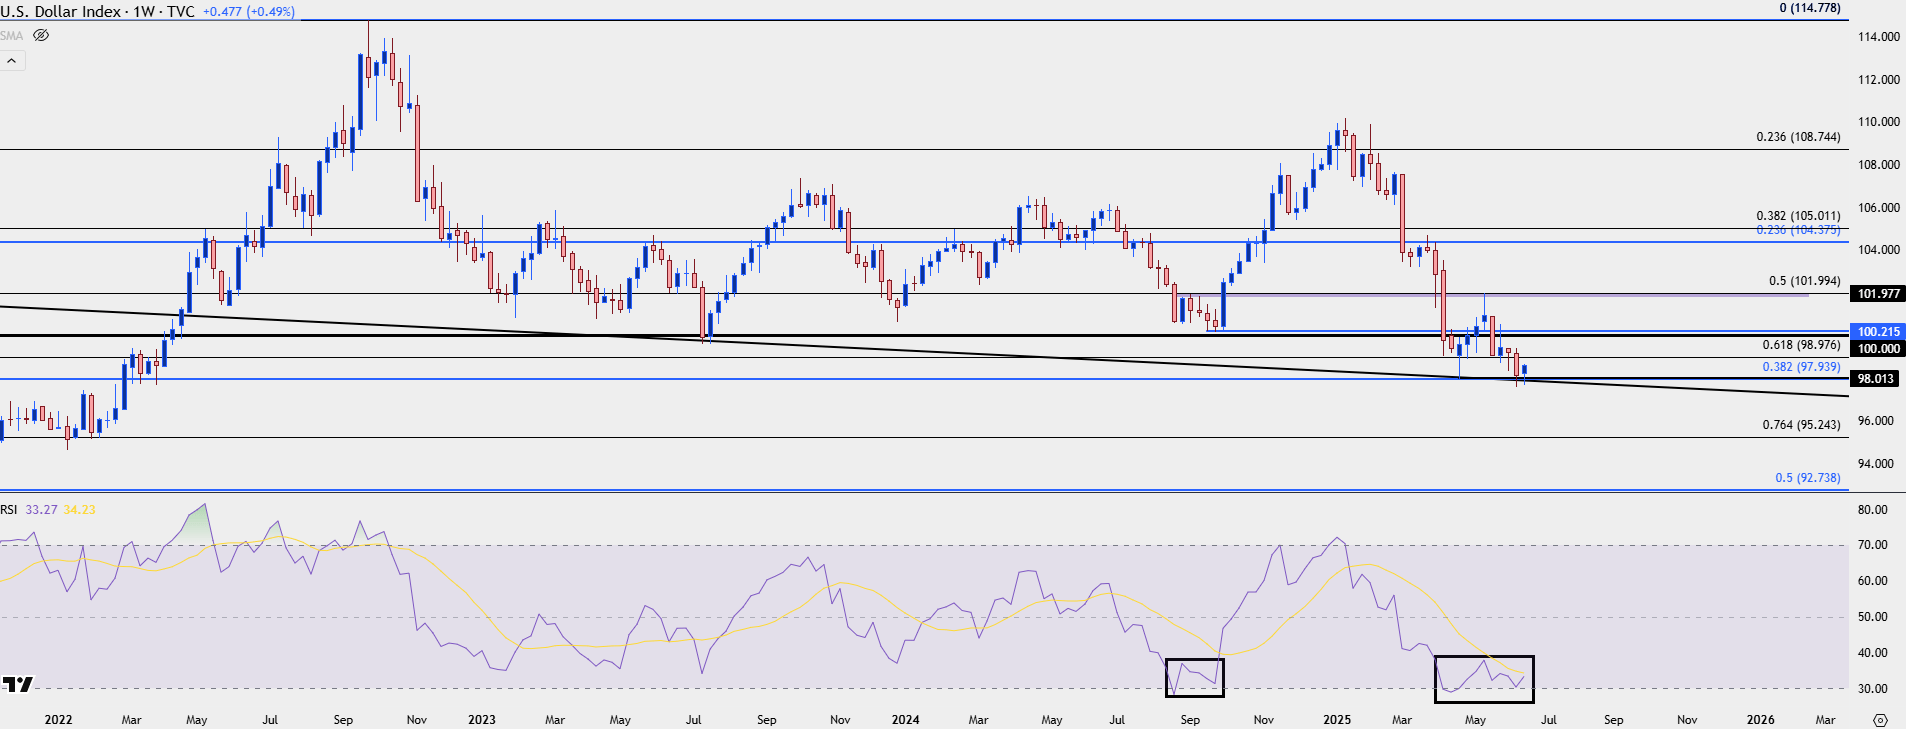 Chart prepared by James Stanley; data derived from Tradingview
EUR/USD
EUR/USD continues to hold on to short-term bullish price action, and in the webinar I went over scenarios on either side of the matter, highlighting 1.1373 and 1.1275 as supports below the 1.1500 level that’s currently being tested.
Of note, RSI on the weekly has just left overbought territory and the indicator has shown divergence after the prior overbought reading in April.
For USD turns, EUR/USD remains of attraction.
EUR/USD Weekly Chart
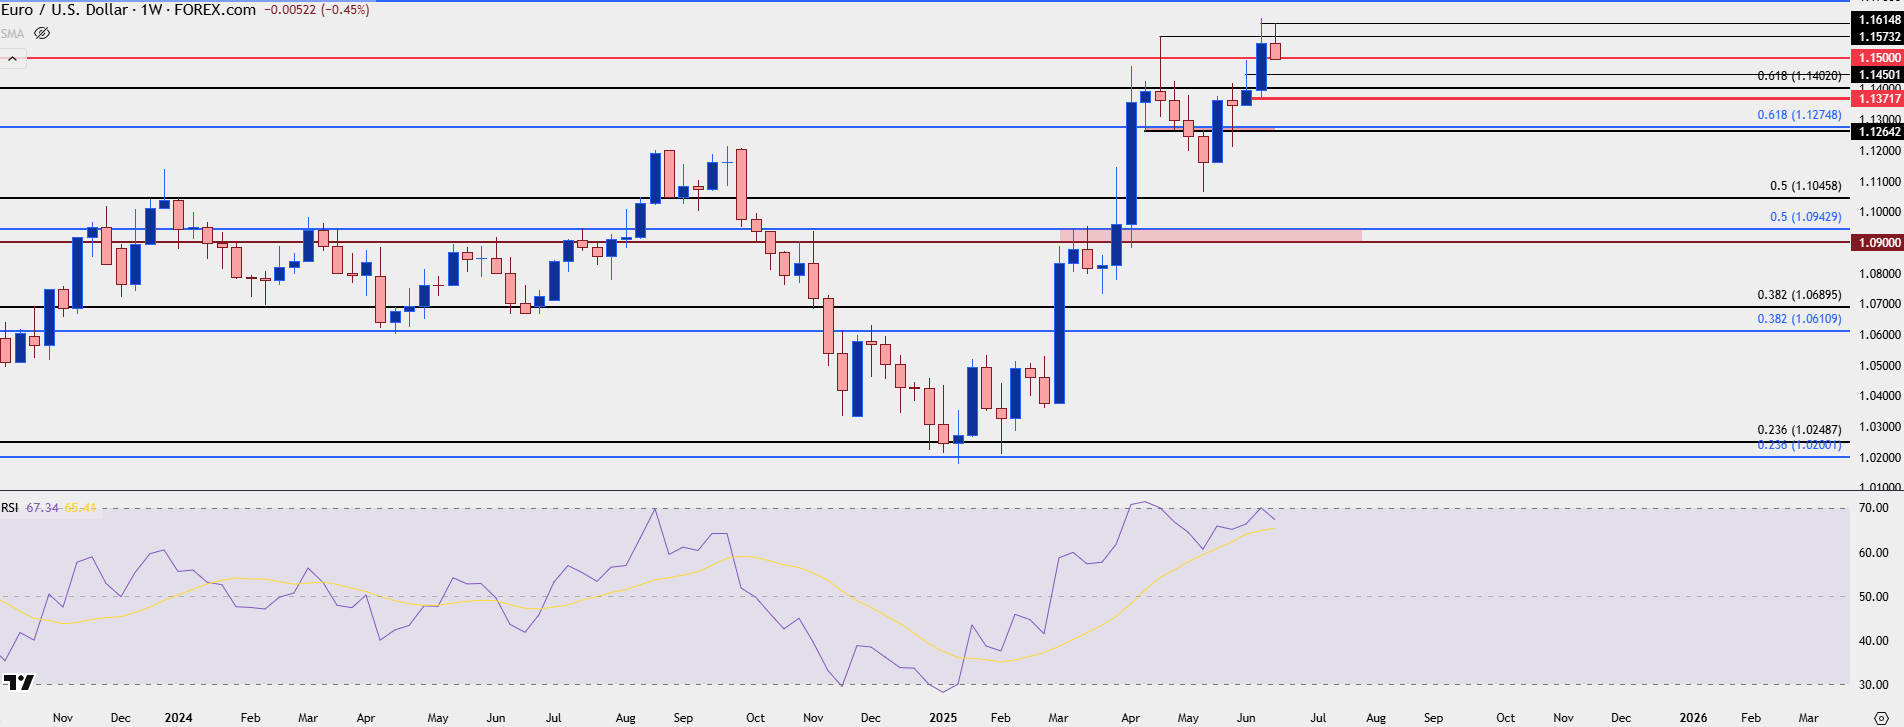 Chart prepared by James Stanley; data derived from Tradingview
USD/JPY
I continue to think that USD/JPY is exhibiting enormous sway over the USD, perhaps more than the 13.6% allocation of JPY in the DXY basket normally would. This dials back to the long-term carry trade and the fact that USD/JPY is still about 40% above early-2021 lows.
The 140 area has held three rigid bounces since December of 2023 and signs of the Fed readying for rate cuts could cause more motivation of unwind as hedges come off. But, if we do see the Fed lean a bit more hawkish, driven by fear of inflation around tariffs, that could produce a short squeeze scenario in both the USD and USD/JPY and that could help to reinforce the USD turn thesis.
USD/JPY is currently pushing through the 145.00 level and that’s been a big spot of late, as looked at in yesterday’s and last week’s articles. Overhead, 145.92 and 146.54 show before the key decision point around the 148.00 handle that caught the highs back in May.
USD/JPY Daily Chart
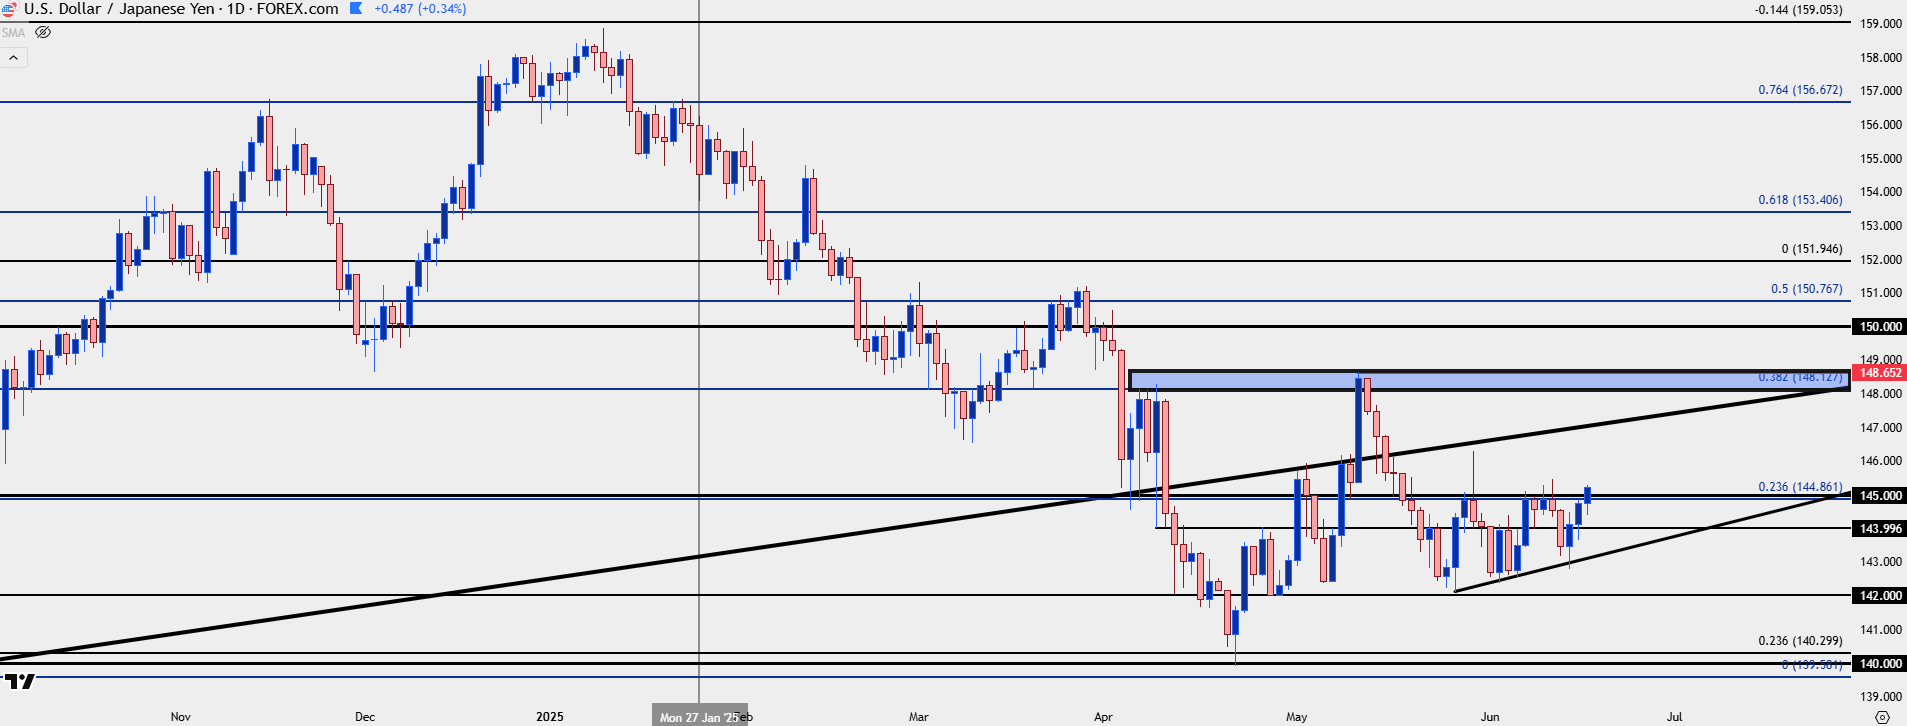 Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Strategist
USD, EUR/USD, USD/JPY, Gold Talking Points:
- Tomorrow brings a quarterly rate decision from the Federal Reserve at which the FOMC will provide updated guidance and projections.
- The big question is whether the Fed is still expecting to cut rates 50 basis points this year as they had last said in their projections in March. Since then, inflation has fallen more than they had expected but labor markets have remained stronger, thereby removing some of the possible motivation to cut. The tariff topic continues to loom large as multiple members of the bank fear of a supply shock, which could lead to higher inflation.
Markets continue to expect the Fed to cut by 50 basis points or more into the end of the year and this pretty much aligns with the bank’s forecasts from the March meeting when they last issued updated projections. With the ECB sounding finished with rate cuts, this has helped to push additional USD weakness as the Dollar has broken down to fresh three-year-lows.
As shown in the video, USD is testing some pretty big support on a bigger picture basis, and the potential for a turn still remains – but for that to come to fruition we’re likely going to need to hear the Fed push rate cut expectations towards 2026 or 2027.
As of this writing, markets are expecting the FOMC to cut rates by 50 basis points by the end of the year to a 65% probability.
Rate Probabilities into End of 2025
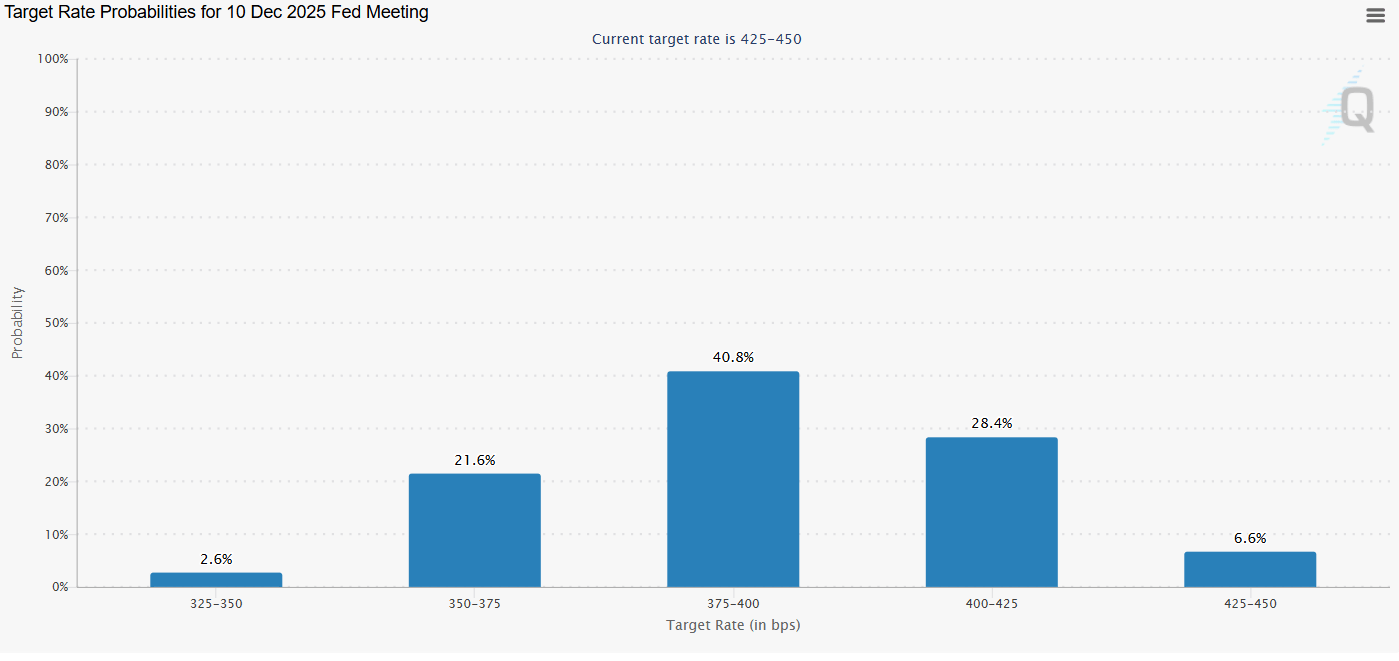 Data derived from CME Fedwatch
Supporting the argument for FOMC cuts is the fact that inflation is well-below what the Fed was last projecting. In the March update, the FOMC said that they were looking for PCE at 2.7% this year, with Core PCE at 2.8%.
At the last update of that data point the numbers were far below that, with PCE at 2.1% and Core PCE at 2.5%. So, from that perspective, the Fed has an open door to cut rates as inflation isn’t as problematic as they were expecting.
On the other side of the argument, however, the labor market has held up a bit better than they were expecting, with the unemployment rate most recently printing at 4.2% and the Fed was looking for that to go up to 4.4% this year. So, the perceived need for rate cuts isn’t as high as the labor market has held up a bit better.
The outside addition to the argument and something we’ve heard multiple Fed members opine on recently is the impact of tariffs. This has seemed to be an overriding concern around the FOMC as the tariff topic remains a very big part of President Trump’s administration, and while some progress has been made on some fronts, it continues to add a healthy amount of uncertainty to the equation.
So the big question here is whether the Fed forges ahead with their 50 bp expectation for rate cuts this year despite the labor market not looking especially bad, and with the risk of additional inflation as produced by tariffs.
FOMC Data Projections from the March Meeting
Data derived from The Federal Reserve; data derived from Tradingview
USD
The US Dollar is grasping on to some long-term supports and chasing the Dollar lower could be a challenge here. I think for bearish outcomes the Fed would need to lean pretty heavily in setting the stage for rate cuts in September when they next provide updated guidance.
The tariff risk could complicate that but with inflation coming in relatively low and recent dimming of data points like retail sales, this has to be entertained a possibility.
There’s also the USD/JPY element, from which the long-term carry trade continues to drive flows around the USD and I’ll look at that a little lower in this article.
Also of note is the RSI divergence showing on the weekly, where last week’s lower-low on price matches with a higher-low via RSI.
U.S. Dollar Weekly Price Chart
Chart prepared by James Stanley; data derived from Tradingview
EUR/USD
EUR/USD continues to hold on to short-term bullish price action, and in the webinar I went over scenarios on either side of the matter, highlighting 1.1373 and 1.1275 as supports below the 1.1500 level that’s currently being tested.
Of note, RSI on the weekly has just left overbought territory and the indicator has shown divergence after the prior overbought reading in April.
For USD turns, EUR/USD remains of attraction.
EUR/USD Weekly Chart
Chart prepared by James Stanley; data derived from Tradingview
USD/JPY
I continue to think that USD/JPY is exhibiting enormous sway over the USD, perhaps more than the 13.6% allocation of JPY in the DXY basket normally would. This dials back to the long-term carry trade and the fact that USD/JPY is still about 40% above early-2021 lows.
The 140 area has held three rigid bounces since December of 2023 and signs of the Fed readying for rate cuts could cause more motivation of unwind as hedges come off. But, if we do see the Fed lean a bit more hawkish, driven by fear of inflation around tariffs, that could produce a short squeeze scenario in both the USD and USD/JPY and that could help to reinforce the USD turn thesis.
USD/JPY is currently pushing through the 145.00 level and that’s been a big spot of late, as looked at in yesterday’s and last week’s articles. Overhead, 145.92 and 146.54 show before the key decision point around the 148.00 handle that caught the highs back in May.
USD/JPY Daily Chart
Chart prepared by James Stanley; data derived from Tradingview
--- written by James Stanley, Senior Strategist


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.

Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.

EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.