



S&P 500 Forecast: SPX remains cautious as risk appetite weakens
It has not been an easy stretch for the S&P 500. Over the last 5 trading sessions, the index has accumulated a decline of nearly -0.9%, while the broader outlook continues to show a phase of neutrality and indecision.
Share this:
It has not been an easy stretch for the S&P 500. Over the last 5 trading sessions, the index has accumulated a decline of nearly -0.9%, while the broader outlook continues to show a phase of neutrality and indecision.
For now, appetite for the SPX has not managed to strengthen consistently, in a context where tensions in the Middle East continue to limit market confidence. If this dynamic continues, the index could remain trapped in a cautious phase over the next few trading sessions.


Is risk appetite weakening?
Regarding the situation in the Middle East, the most relevant update for markets has been the attack on a tanker in the Strait of Hormuz. In response to the deterioration of the situation, the United States carried out new rounds of airstrikes against Iranian targets over the last few sessions.
This scenario suggests that the interim agreement aimed at stopping attacks and supporting a more relevant ceasefire has gradually weakened. As a result, doubts have increased around a possible diplomatic solution to the conflict in the short term.
This event has increased uncertainty across financial markets and kept the geopolitical risk premium elevated. In addition, WTI crude oil is already trading above the 86-dollar area, which also raises concerns about possible inflationary pressure over the coming months.
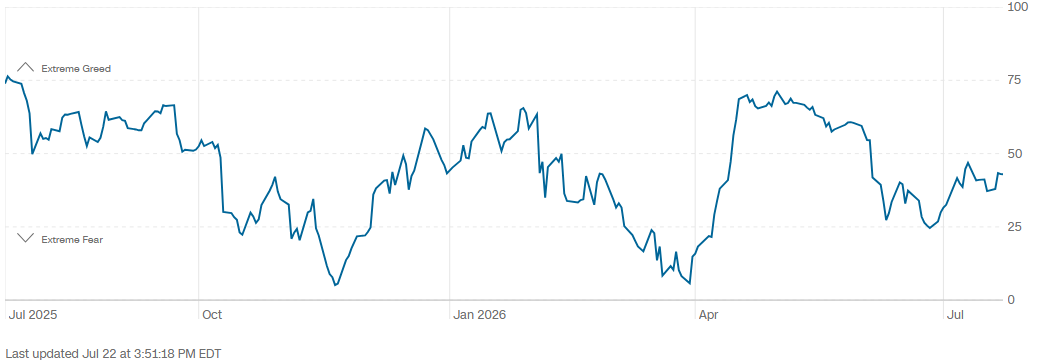
This chain of events has prevented confidence in risk markets from stabilizing. This can be seen in the recent behavior of the financial markets’ fear and greed index, which still remains below the 50-point area and has not fully moved out of the “fear” zone. In fact, the recovery in the confidence indicator started to become more limited as tensions in the Middle East intensified again.
Source: CNN
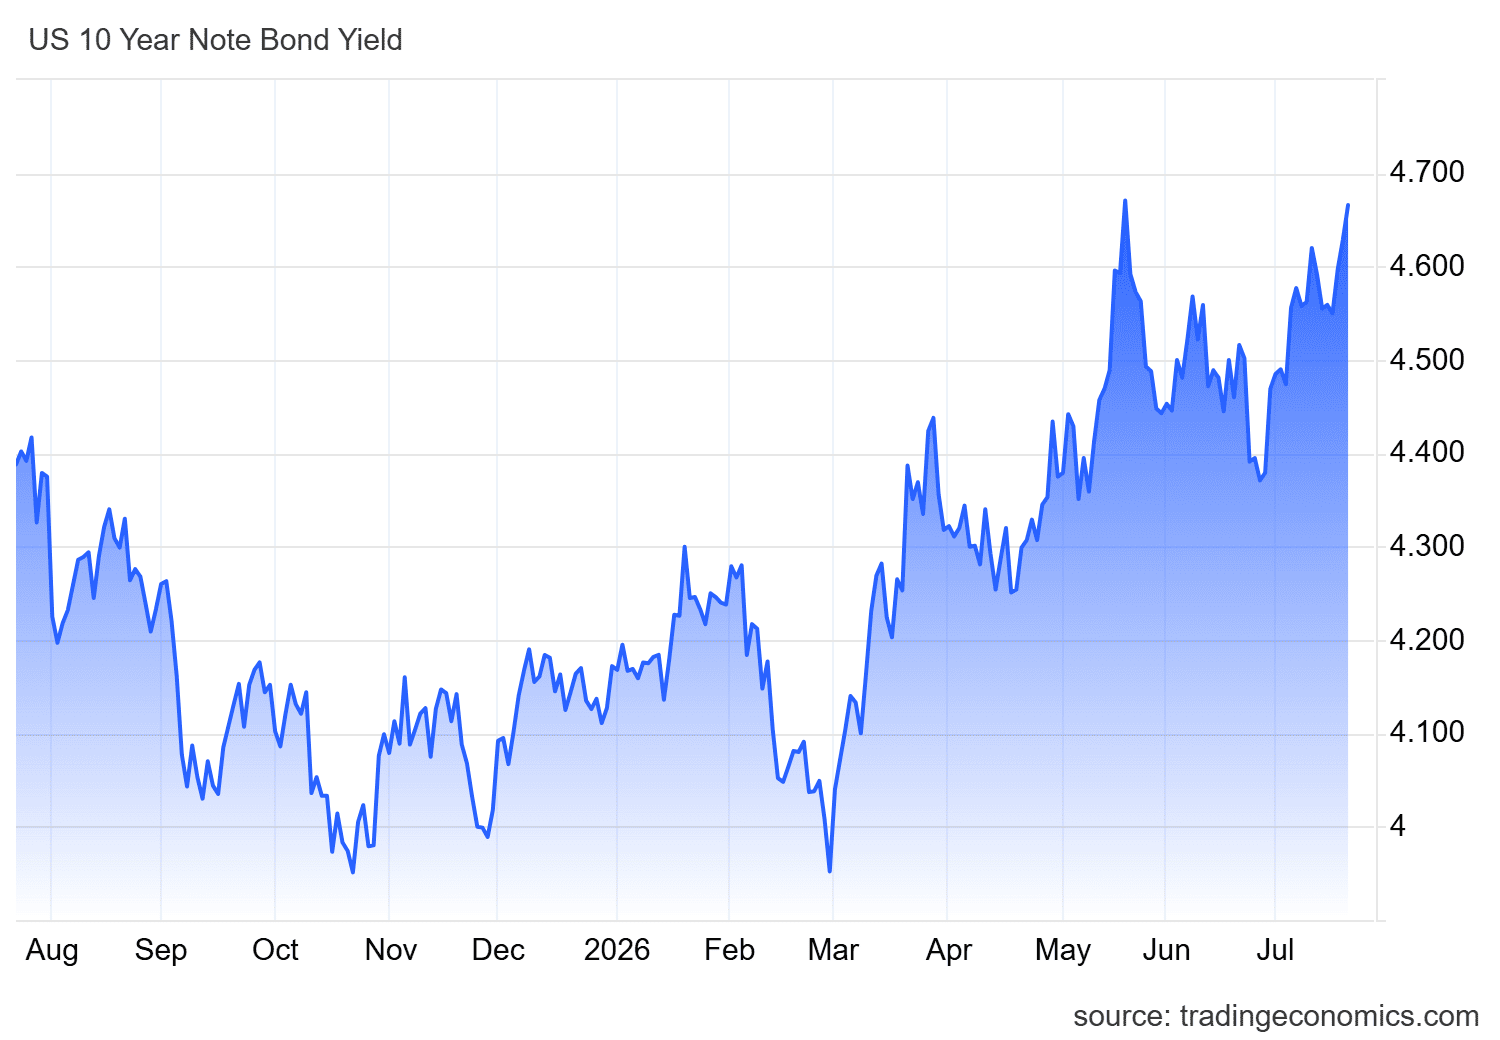
Another important short-term factor has been the behavior of the 10-year U.S. Treasury market, one of the main safe-haven markets and substitutes for equity indices.
As the conflict in the Middle East increases inflation concerns, the 10-year Treasury yield has maintained an upward slope and is already above the 4.6% area, moving close again to yearly highs. This makes one of the world’s safest markets more attractive and may limit appetite for higher-risk assets such as equities.
Source: TradingEconomics
With all of this in mind, the combination of higher tensions in the Middle East, risks around the Strait of Hormuz, more expensive oil and higher U.S. Treasury yields is creating a less favorable environment for the S&P 500.
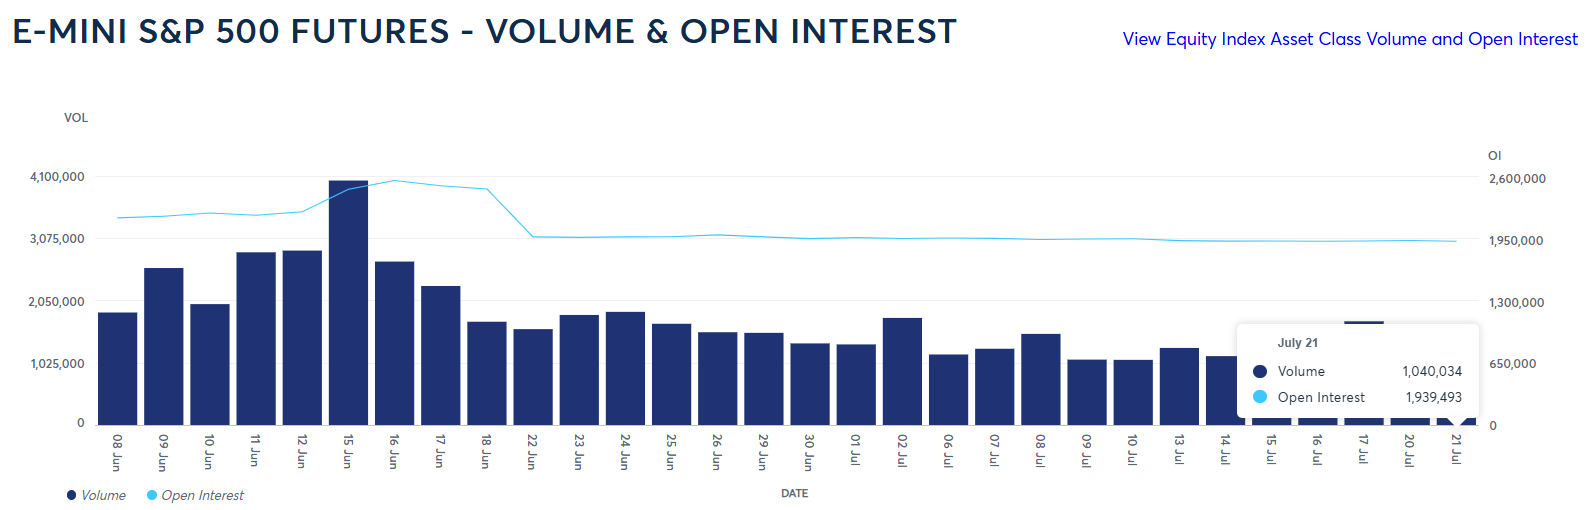
This dynamic is also reflected in the index futures market. During this week, as the escalation of the conflict and the rise in Treasury yields became more relevant, activity in E-mini S&P 500 futures showed a decline in volume toward an area close to 1 million contracts traded on July 21, a lower figure compared with previous weeks.
This lower activity may reflect greater caution among market participants, in a context where the conflict remains active and risk appetite continues to be limited.
Source: CMEGROUP
Therefore, the combination of higher bond market yields and confidence that has not managed to recover consistently could continue to weigh on appetite for risk markets such as the SPX. If this scenario continues, the phase of indecision around the S&P 500 could remain in place over the next few trading sessions.
Technical forecast for S&P 500
Source: StoneX, Tradingview
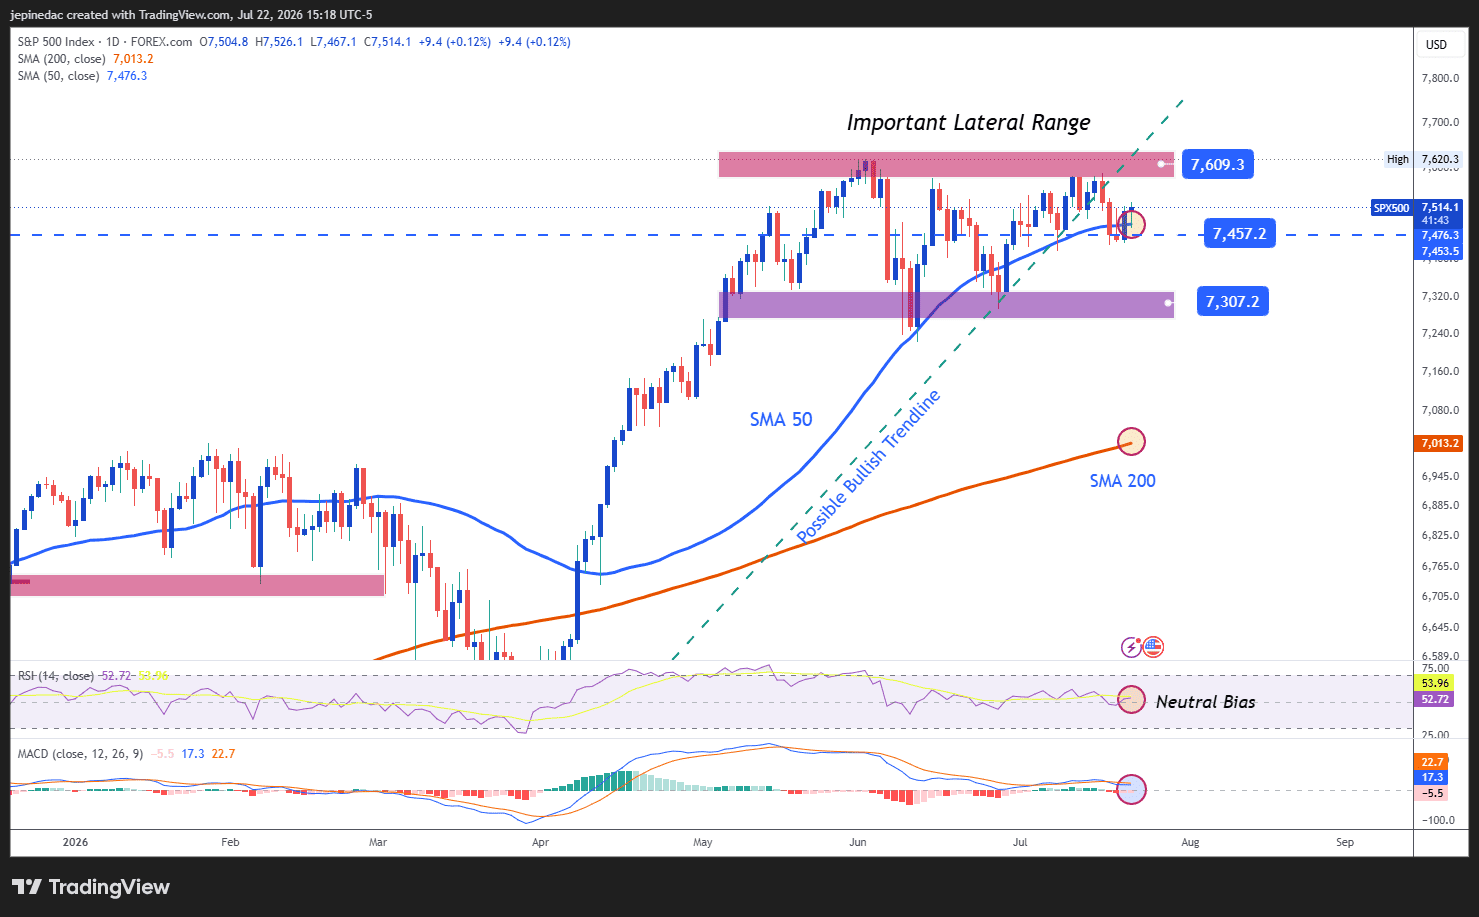
- Sideways range continues to dominate: For several weeks, the S&P 500 has continued to trade within a relevant sideways range, with an upper barrier near 7,600 points and a lower area around 7,300 points. So far, price movements have not been enough to establish a clear direction outside these levels. For this reason, the sideways range remains the most important technical structure on the chart and could keep the indecision phase in place over the next few trading sessions.
- RSI: Recent RSI movements remain close to the neutral 50 level. This suggests a balance between buying and selling impulses in the market over the last 14 sessions. As long as this behavior continues, price neutrality could remain relevant in the short term.
- MACD: A similar scenario can be seen in the MACD, whose histogram remains very close to the neutral 0 line. This suggests balance in the strength of short-term moving averages and reinforces the possibility that indecision remains present on the chart.
Key levels:
- 7,600 points – Relevant resistance: This area corresponds to the index’s all-time highs and remains the main bullish reference. A move toward this level could strengthen the buying bias and reactivate the bullish trend observed in previous weeks.
- 7,450 points – Near-term barrier: This level works as an important neutral zone, as it coincides with recent retracements and the 50-period simple moving average. If price continues to trade near this reference, the indecision phase could extend and keep the sideways range in place over the next few sessions.
- 7,300 points – Key support: This area coincides with relevant lows from recent weeks and remains the main bearish barrier. Sustained moves below this level could reinforce the selling bias and open room for more consistent bearish pressure over the coming weeks.
Written by Julian Pineda, CFA, CMT – Market Analyst
Follow him on: @julianpineda25
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
ASX 200 Futures Hold Relatively Firm as Nikkei Plunges After Wall Street Rout
Wall Street's AI-led rout sends Nikkei futures plunging 9%, while ASX 200 futures hold relatively firm despite surging volatility and broader risk aversion.
S&P 500 Update: SPX Records Its Biggest Selloff of the Year Ahead of NFP
The trading week has not been particularly favorable for risk appetite in the short term, and this is now becoming increasingly evident in the performance of the S&P 500. During today's session, the index is down nearly 4.2%, marking its largest intraday decline of 2026.
Nasdaq 100 forecast: Tech stocks remain under pressure despite mid terms rally
The Democratic sweep in the US midterms delivered the negative dollar reaction I had anticipated, but that upsurge in stocks was not something I or many others had anticipated. Fears that a Democrat-controlled Congress would trigger a broader sell-off in technology stocks proved premature. Nevertheless, the sector remains under pressure. The political outcome may help explain the Nasdaq’s relative underperformance with futures falling 0.8% today. Sharp falls in shares of Arm and Qualcomm following their results are certainly not helping. While the removal of midterm uncertainty provided a broad-based boost to risk appetite yesterday, investors may be starting to price in the prospect of tighter regulatory scrutiny of Big Tech, particularly around AI, under greater Democratic influence in Congress. This could become a headwind for technology valuations, even if the immediate impact on corporate earnings remains unclear.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.