



US open: Futures pare gains after hot PPI
Share this:

US futures
Dow futures +0.1% at 29250
S&P futures +0.25% at 3596
Nasdaq futures +0.41% at 10835
In Europe
FTSE -0.91% at 6826
Dax -0.24% at 12150
FOMC minutes due later
US stocks are set to open higher on Wednesday after a mixed close in the previous session but pared gains following PPI inflation data. The rise comes after the Nasdaq has fallen across the past five days, hitting a new 2-year low yesterday.
US PPI inflation rose 8.5% YoY in September, down from 8.7%; expectations had been for PPI to ease to 8.4% YoY. The hot inflation reading boosted bets of more aggressive action from the Federal Reserve. Given that PPI is considered a lead indicator for consumer prices, the data suggests that the lowering in inflation will be a very slow process.
Looking ahead attention turns to the minutes to the September FOMC, which are expected to confirm the Fed’s hawkish outlook. The minutes are from the meeting where the Fed raised interest rates by 75 basis points and raised the likelihood of more aggressive hikes in the coming meetings.
Corporate news:
PepsiCo rises pre-market after it raised its annual revenue and profit forecasts. The beverage and snack form managed to raise its prices on several occasions to impact rising costs. Consumers are eating more at home than in restaurants amid a cutback in discretionary spending.
Where next for Dow Jones?
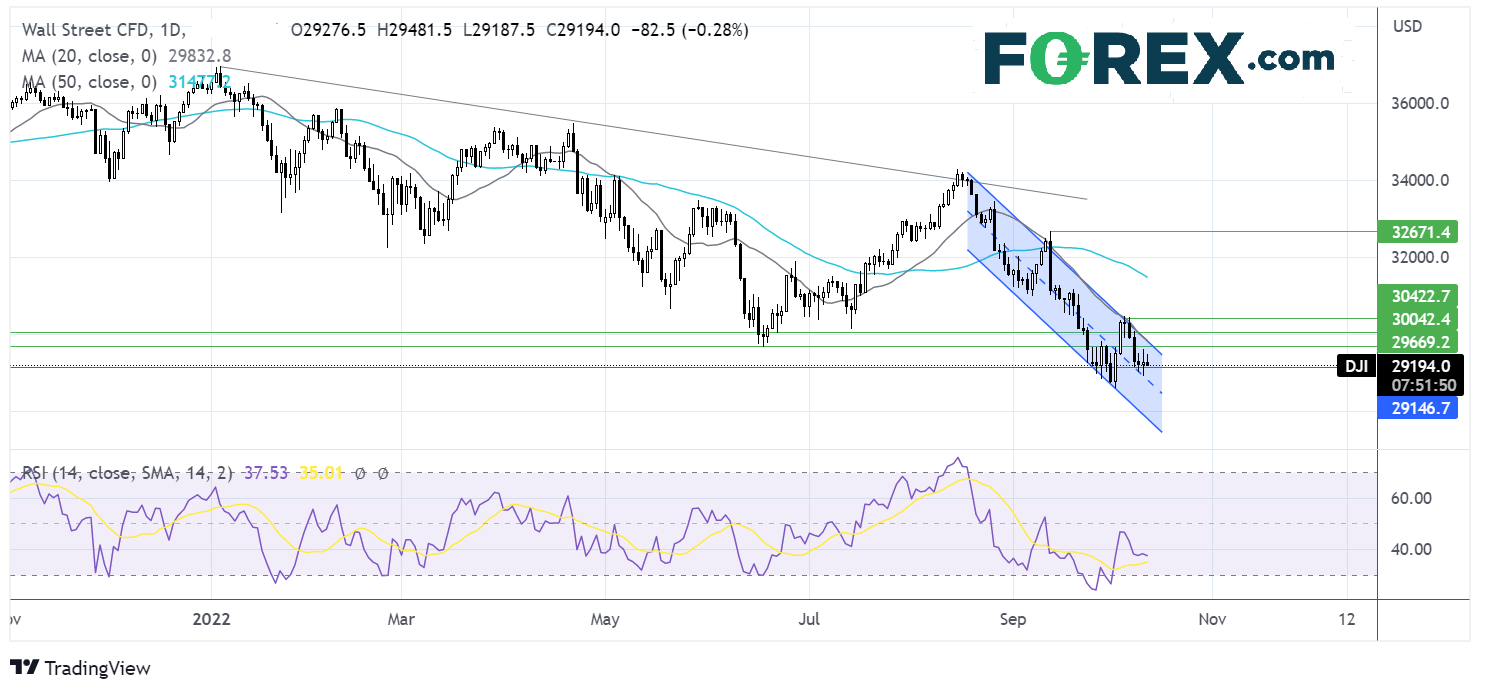
The Dow Jones is trading within a descending trendline since mid-August. It trades below its 20 & 50 sma, and the RSI remains in bearish territory, suggesting that there is more downside to come. Sellers will look for a break below 28900, opening the door to 28500, the 2022 low. A break below here brings 28000 the round number, and lower band of the falling trendline into focus. On the flipside, buyers will look for a move over 29720, the June low, and 30,000, the round number. A move over 30450 creates a higher high.
FX markets – USD slips, GBP rises
The USD is edging lower after five straight days of gains. Hawkish comments from Federal Reserve speakers boosted the USD in the previous session. Attention is now shifting to the FOMC minutes later today.
EUR/USD is holding steady after stronger-than-expected industrial production, which rose 1.5% MoM in August after falling -2.3% in July. Attention now shifts to ECB President Lagarde who is due to speak later.
GBPUSD is rising, paring losses from the previous session. The pound is rising despite dismal data, which showed that GDP unexpectedly fell -0.3% MoM in August after rising 0.2% in July. Expectations had been for 0%. The BoE also confirmed that it would be ending its bond-buying programme on Friday after some confusion over whether it would be prolonged to offer additional support.
GBP/USD +0.18% at 1.1070
EUR/USD +0.18% at 0.9726
Oil falls for a third day
Oil prices are heading lower for a third straight session, as investors fret over declining demand as recession worries rise. The IMF cut its global growth outlook yesterday and warned of the increasing risk of a global recession. The IMF encouraged central bankers to keep up the fight against inflation, even if this meant slowing growth or a recession.
OPEC cut oil demand growth for 2022 and 2023. This is the fourth such cut in demand since April
Rising COVID cases in China are also a concern. Testing is being ramped up in Shanghai and Shenzhen as cases rose to the highest level since August.
On the supply side, crude stocks have risen by 1.8 million barrels after falling for the past two weeks. API stockpile data is due later today.
WTI crude trades -0.6% at $88.70
Brent trades -0.6% at $94.50
Learn more about trading oil here.
Looking ahead
14:30 ECB President Lagarde to speak
19:00 FOMC minutes
US futures
Dow futures +0.1% at 29250
S&P futures +0.25% at 3596
Nasdaq futures +0.41% at 10835
In Europe
FTSE -0.91% at 6826
Dax -0.24% at 12150
Learn more about trading indices
FOMC minutes due later
US stocks are set to open higher on Wednesday after a mixed close in the previous session but pared gains following PPI inflation data. The rise comes after the Nasdaq has fallen across the past five days, hitting a new 2-year low yesterday.
US PPI inflation rose 8.5% YoY in September, down from 8.7%; expectations had been for PPI to ease to 8.4% YoY. The hot inflation reading boosted bets of more aggressive action from the Federal Reserve. Given that PPI is considered a lead indicator for consumer prices, the data suggests that the lowering in inflation will be a very slow process.
Looking ahead attention turns to the minutes to the September FOMC, which are expected to confirm the Fed’s hawkish outlook. The minutes are from the meeting where the Fed raised interest rates by 75 basis points and raised the likelihood of more aggressive hikes in the coming meetings.
Corporate news:
PepsiCo rises pre-market after it raised its annual revenue and profit forecasts. The beverage and snack form managed to raise its prices on several occasions to impact rising costs. Consumers are eating more at home than in restaurants amid a cutback in discretionary spending.
Where next for Dow Jones?
The Dow Jones is trading within a descending trendline since mid-August. It trades below its 20 & 50 sma, and the RSI remains in bearish territory, suggesting that there is more downside to come. Sellers will look for a break below 28900, opening the door to 28500, the 2022 low. A break below here brings 28000 the round number, and lower band of the falling trendline into focus. On the flipside, buyers will look for a move over 29720, the June low, and 30,000, the round number. A move over 30450 creates a higher high.

FX markets – USD slips, GBP rises
The USD is edging lower after five straight days of gains. Hawkish comments from Federal Reserve speakers boosted the USD in the previous session. Attention is now shifting to the FOMC minutes later today.
EUR/USD is holding steady after stronger-than-expected industrial production, which rose 1.5% MoM in August after falling -2.3% in July. Attention now shifts to ECB President Lagarde who is due to speak later.
GBPUSD is rising, paring losses from the previous session. The pound is rising despite dismal data, which showed that GDP unexpectedly fell -0.3% MoM in August after rising 0.2% in July. Expectations had been for 0%. The BoE also confirmed that it would be ending its bond-buying programme on Friday after some confusion over whether it would be prolonged to offer additional support.
GBP/USD +0.18% at 1.1070
EUR/USD +0.18% at 0.9726
Oil falls for a third day
Oil prices are heading lower for a third straight session, as investors fret over declining demand as recession worries rise. The IMF cut its global growth outlook yesterday and warned of the increasing risk of a global recession. The IMF encouraged central bankers to keep up the fight against inflation, even if this meant slowing growth or a recession.
OPEC cut oil demand growth for 2022 and 2023. This is the fourth such cut in demand since April
Rising COVID cases in China are also a concern. Testing is being ramped up in Shanghai and Shenzhen as cases rose to the highest level since August.
On the supply side, crude stocks have risen by 1.8 million barrels after falling for the past two weeks. API stockpile data is due later today.
WTI crude trades -0.6% at $88.70
Brent trades -0.6% at $94.50
Learn more about trading oil here.
Looking ahead
14:30 ECB President Lagarde to speak
19:00 FOMC minutes
Related tags:
Latest market news



Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.
Dow Jones Slide Shows What Rate Hike Bets Mean for Stocks
The Dow Jones support breakdown shows rising bond yields and rate hike bets hitting U.S. stocks while tech giants prop up the Nasdaq.
EUR/USD forecast remains tilted lower with French bond troubles ahead of US jobs report
The EUR/USD has tagged a fresh year-to-date low as French public-finance concerns trigger a government bond sell-off. Today's US jobs report may change little, with resilient activity, elevated energy prices and hawkish Fed bets keeping the greenback supported. With the pair trapped below resistance at 1.1410, the risk to the near-term EUR/USD forecast is tilted to the downside.
This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.