



US open: Stocks fall as peace talk optimism fades
US stocks point lower and oil prices higher after the Kremlin says that there has been no breakthrough in peace talks yet. The ADP report showed a strong labour market.
Share this:

US futures
Dow futures -0.43% at 35183
S&P futures -0.56% at 4607
Nasdaq futures -0.6% at 15150
In Europe
FTSE +0.1% at 7540
Dax -1.5% at 14580
Euro Stoxx -1.2% at 3945
Learn more about trading indices
Stocks drop, oil rallies
Stocks on Wall Street are pointing to a weaker open after strong gains in the previous session. Optimism surrounding the Russia, Ukraine peace talks boosted risk appetite yesterday, lifting stocks and pulling oil prices lower. Today as that optimism fades, stocks are falling.
The Kremlin has said that there is no sign of a breakthrough in talks yet, pouring cold water on yesterday’s relief rally. Yesterday Russia had vowed to cut its military activity around Kyiv, but this has yet to be translated into action on the ground.
Concerns over the war, rising energy prices, and surging inflation have hit sentiment in the first quarter of the year.
Data wide, ADP data revealed that 455K jobs were added in the private sector in March, roughly in line with estimates of 450k. The US labour market remains tight, and the data bodes well for an upbeat non-farm payroll on Friday.
However, US Q4 GDP was 7.1% QoQ, slightly short of the 7.2% forecast but still up firmly from 5.9% previously.
In corporate news:
Micron Technologies rises over 3% premarket following a solid forecast for the current quarter, indicating that demand for memory chips from data centres remains strong.
BioNTech rises 7% premarket after beating Q4 estimates, helped the strong COVID vaccine sales and also announced a special dividend and a $1.5 billion share buyback programme.
Where next for the Nasdaq?
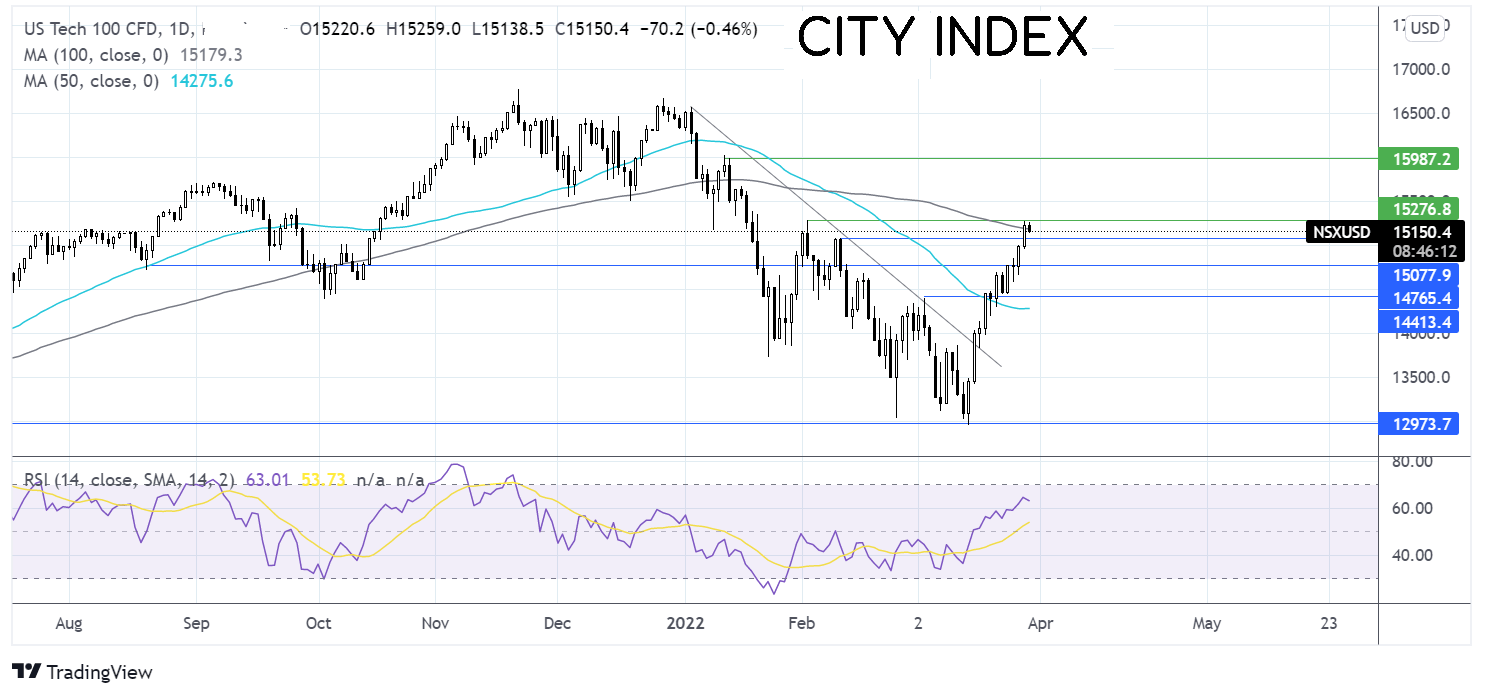
The NASDAQ has extended its rebound from the 12950 March low. It has retaken the 50 SMA and ran into resistance at 15275, the February 2nd high and a potential double top formation. The RSI supports further upside, although the 4-hour chart shows overbought, so today’s selloff could also be technical. Buyers will need to recapture 15200 to target 16000 the January 12 high. Should momentum slow, the NASDAQ could fall back to test 15070, the Feb 10 high and 14700, a level that has offered support and resistance on several occasions across the past six months.
FX markets USD drops, EUR extends gains
USD is trading sharply lower for a second straight session. USD was out of favour on safe-haven outflows yesterday, with the selling coming across today, despite equity markets falling.
The euro continues to charge higher, building on gains from yesterday on optimism of a diplomatic solution to the war. Investors have looked past falling economic sentiment in the region. German inflation rose to 7.6% YoY in March, well above the 5.5% registered in February.
GBP/USD rises for a second day on USD weakness and as investors shrug off a cautious sounding BoE vice Governor Broadbent. Broadbent said that the interest rate outlook was unpredictable given the shocks that the UK economy is experiencing.
GBP/USD +0.5% at 1.3156
EUR/USD +0.4% at 1.1130
Oil rebounds on tight supply concerns
After falling 8% across the first two days of this week, oil prices are rebounding higher on tight supply and potential new sanctions on Russia.
Despite suggestions that peace talks made progress yesterday, the fact that oil is rising today suggests that the market is far from convinced that war is ending soon.]
Furthermore, concerns over more sanctions on Moscow are keeping oil prices supported. So far, Europe is split over whether to apply sanctions on Russian oil.
API data revealed that crude stockpiles fell by 3 million barrels; this was three times the expected draw, highlighting how tight the market is. EIA data is due later.
OPEC+ are due to meet tomorrow and are not expected to ride to the rescue, considering that there is sufficient supply and that this is a geopolitical problem.
WTI crude trades +2.17% at $106.14
Brent trades +2.2% at $110.07
Learn more about trading oil here.
Looking ahead
15:30 EIA crude oil inventory
How to trade with City Index
Follow these easy steps to start trading with City Index today:
- Open a City Index account, or log-in if you’re already a customer.
- Search for the market you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels
- Place the trade.
US futures
Dow futures -0.43% at 35183
S&P futures -0.56% at 4607
Nasdaq futures -0.6% at 15150
In Europe
FTSE +0.1% at 7540
Dax -1.5% at 14580
Euro Stoxx -1.2% at 3945
Stocks drop, oil rallies
Stocks on Wall Street are pointing to a weaker open after strong gains in the previous session. Optimism surrounding the Russia, Ukraine peace talks boosted risk appetite yesterday, lifting stocks and pulling oil prices lower. Today as that optimism fades, stocks are falling.
The Kremlin has said that there is no sign of a breakthrough in talks yet, pouring cold water on yesterday’s relief rally. Yesterday Russia had vowed to cut its military activity around Kyiv, but this has yet to be translated into action on the ground.
Concerns over the war, rising energy prices, and surging inflation have hit sentiment in the first quarter of the year.
Data wide, ADP data revealed that 455K jobs were added in the private sector in March, roughly in line with estimates of 450k. The US labour market remains tight, and the data bodes well for an upbeat non-farm payroll on Friday.
However, US Q4 GDP was 7.1% QoQ, slightly short of the 7.2% forecast but still up firmly from 5.9% previously.
In corporate news:
Micron Technologies rises over 3% premarket following a solid forecast for the current quarter, indicating that demand for memory chips from data centres remains strong.
BioNTech rises 7% premarket after beating Q4 estimates, helped the strong COVID vaccine sales and also announced a special dividend and a $1.5 billion share buyback programme.
Where next for the Nasdaq?
The NASDAQ has extended its rebound from the 12950 March low. It has retaken the 50 SMA and ran into resistance at 15275, the February 2nd high and a potential double top formation. The RSI supports further upside, although the 4-hour chart shows overbought, so today’s selloff could also be technical. Buyers will need to recapture 15200 to target 16000 the January 12 high. Should momentum slow, the NASDAQ could fall back to test 15070, the Feb 10 high and 14700, a level that has offered support and resistance on several occasions across the past six months.

FX markets USD drops, EUR extends gains
USD is trading sharply lower for a second straight session. USD was out of favour on safe-haven outflows yesterday, with the selling coming across today, despite equity markets falling.
The euro continues to charge higher, building on gains from yesterday on optimism of a diplomatic solution to the war. Investors have looked past falling economic sentiment in the region. German inflation rose to 7.6% YoY in March, well above the 5.5% registered in February.
GBP/USD rises for a second day on USD weakness and as investors shrug off a cautious sounding BoE vice Governor Broadbent. Broadbent said that the interest rate outlook was unpredictable given the shocks that the UK economy is experiencing.
GBP/USD +0.31% at 1.3130
EUR/USD +0.9% at 1.1080
Oil rebounds on tight supply concerns
After falling 8% across the first two days of this week, oil prices are rebounding higher on tight supply and potential new sanctions on Russia.
Despite suggestions that peace talks made progress yesterday, the fact that oil is rising today suggests that the market is far from convinced that war is ending soon.]
Furthermore, concerns over more sanctions on Moscow are keeping oil prices supported. So far, Europe is split over whether to apply sanctions on Russian oil.
API data revealed that crude stockpiles fell by 3 million barrels; this was three times the expected draw, highlighting how tight the market is. EIA data is due later.
OPEC+ are due to meet tomorrow and are not expected to ride to the rescue, considering that there is sufficient supply and that this is a geopolitical problem.
WTI crude trades +2.17% at $106.14
Brent trades +2.2% at $110.07
Looking ahead
15:30 EIA crude oil inventory


Open an account in minutes
Experience award-winning platforms with fast and secure execution, and enjoy tight spreads from 0.5 pts on FX and 0.3 pts on indices.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
USD/JPY weekly outlook: Quarter turn scrambles rates regime
USD/JPY’s tight relationship with front-end US rates broke down sharply last week, but quarter-turn flows and positioning suggest the disconnect may prove temporary.

USD/CAD forecast: rally could accelerate above June highs at 1.4250
USD/CAD recovered quickly after weaker US jobs data, keeping the bullish trend in focus. A move above the June highs could accelerate the rally as inflation keeps the Fed under pressure.


USD Sets Fresh Yearly High as EUR/USD Drops Dramatically, USD/JPY Stable
Well, it was a week of USD strength that wasn’t entirely pushed by USD/JPY, as a strong sell-off in EUR/USD has pushed the major pair to its most oversold state in a decade.

This report is intended for general circulation only. It should not be construed as a recommendation, or an offer (or solicitation of an offer) to buy or sell any financial products. The information provided does not take into account your specific investment objectives, financial situation or particular needs. Before you act on any recommendation that may be contained in this report, independent advice ought to be sought from a financial adviser regarding the suitability of the investment product, taking into account your specific investment objectives, financial situation or particular needs.
StoneX Financial Pte. Ltd., may distribute reports produced by its respective foreign entities or affiliates within the StoneX group of companies or third parties pursuant to an arrangement under Regulation 32C of the Financial Advisers Regulations. Where the report is distributed to a person in Singapore who is not an accredited investor, expert investor or an institutional investor (as defined in the Securities Futures Act), StoneX Financial Pte. Ltd. accepts legal responsibility to such persons for the contents of the report only to the extent required by law. Singapore recipients should contact StoneX Financial Pte. Ltd. at 6826 9988 for matters arising from, or in connection with the report.
In the case of all other recipients of this report, to the extent permitted by applicable laws and regulations neither StoneX Financial Pte. Ltd. nor its associated companies will be responsible or liable for any loss or damage incurred arising out of, or in connection with, any use of the information contained in this report and all such liability is hereby expressly disclaimed. No representation or warranty is made, express or implied, that the content of this report is complete or accurate.
StoneX Financial Pte. Ltd. is not under any obligation to update this report.
Trading CFDs carries a high level of risk that may not be suitable for some investors. Consider your investment objectives, level of experience, financial resources, risk appetite and other relevant circumstances carefully. The possibility exists that you could lose some or all of your investments, including your initial deposits. If in doubt, please seek independent expert advice. Visit www.forex.com/en-sg/terms-and-policies for the complete Risk Disclosure Statement.