



Risk assets drop with escalated trade concerns again hurting sentiment
Investors are watching the deteriorating US-China trade relationship closely this week after tensions escalated by both nations increasing tariffs on each other.
Share this:

This morning, European stocks were finding themselves under pressure again with US index futures also pointing to a sharply weaker open on Wall Street. Risk aversion was also noticeable in other markets, with crude oil and copper prices trading lower. Meanwhile gold and silver struggled to find buyers after their mid-week reversal last week on the back of demand concerns from China and the US amid tariff wars. Instead, haven flows were evident in the FX markets. For example, Japanese yen and Swiss franc were both on the rise again, while the offshore Chinese yuan was on the back foot again.
Aussie dollar’s election boost could be short-lived
Meanwhile, the AUD/USD, which jumped at the Asian open overnight in reaction to the surprise victory for Australia Prime Minister, was still trading in the black at the time of writing. Scott Morrison’s pledges to pass tax cuts to shore up a slowing economy is seen as being positive for Australian stocks and the Aussie dollar. However, with the US-China trade weighing on risk sentiment can the risk-sensitive AUD hold onto its overnight gains? In the short-term, we are doubtful given the recent escalation in trade wars between Australia’s largest trading partner China and the US. On top of this, the Reserve Bank of Australia is likely to cut interest rates in the next meeting on 4th June from 1.5% to 1.25% after surprising the markets last time by holding rates unchanged when a cut was expected. A rate cut from the RBA should provide downward pressure on the Aussie, at least in the short-term.
Further retaliatory reaction from China expected amid Huawei row
Investors are watching the deteriorating US-China trade relationship closely this week after tensions escalated by both nations increasing tariffs on each other. News that US tech firms such as Google have started to cut off software and components from China's Huawei under the new US ban is likely to trigger further retaliatory reaction from China. In trying to offset the risks the trade war brings, the People’s Bank of China is likely to introduce further monetary stimulus which could lead to further weakness for the renminbi. Sentiment is only likely to turn decidedly positive if the two nations put their differences aside and come up with a trade agreement. At the moment, this looks unlikely and the markets are not optimistic either with stocks dropping.
Is Fed’s Powell concerned about escalation in US-China trade spat?
Meanwhile the economic calendar is light today, although the Federal Reserve Chairman Jerome Powell will be speaking at the Atlanta Fed’s annual Financial Markets Conference. Investors will be listening carefully to any remakes Mr Powell May make about the ongoing trade tensions and how this might impact the US and global economies, and whether this will have any potential implications for inflation and therefore interest rates. The greenback could weaken should we hear surprising dovish remarks from the Fed Chair, especially against haven currencies JPY and CHF.
Chart to watch: USD/JPY
With risk off the menu, the USD/JPY has started the week on the backfoot despite printing a bullish hammer candle on the weekly chart last week. The bulls would be worried by the fact price has failed to hold above last week’s high around 110.20/22, as this could potentially mean they are trapped. If the USD/JPY fails to turn positive by mid-week then we would expect rates to take out liquidity below last week’s low around 109.00 next. And if there is acceptance below 109.00 then a much deeper correction could be on the way.
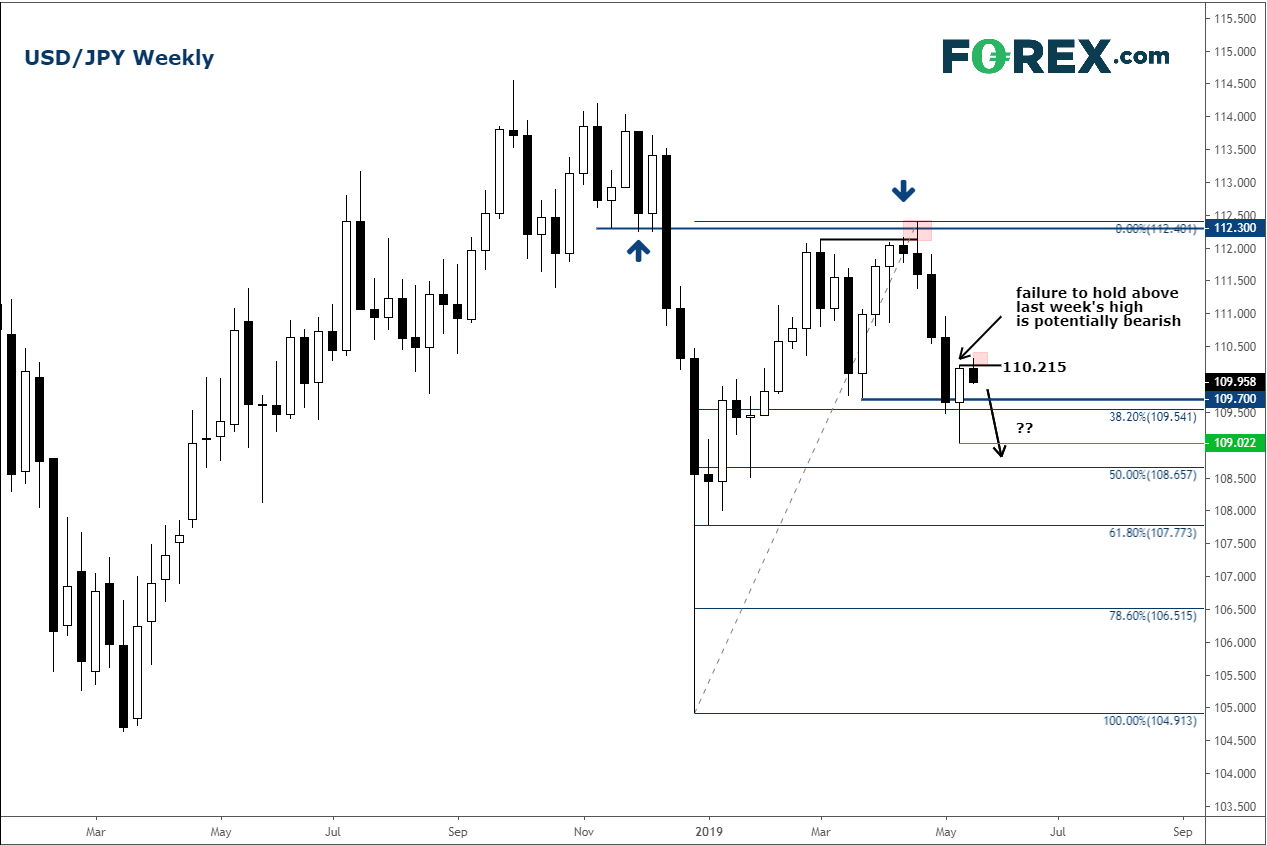
Source: TradingView and FOREX.com
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.