



Stocks rise ahead of a busy week
Will the positively last or will central bank tightening and inflation concerns come back to haunt investors?
Share this:

Sentiment has improved with European stocks and US futures on the rise first thing this morning, but with much of Europe on holiday, trading volumes are naturally thin, and the macro calendar is light. Things will get busier, with the RBA, ECB and US CPI all to come later in the week. But first, Boris is Johnson, the UK Prime Minister, is facing a key vote around 18:00 to 20:00 BST today. Will the positively last or will central bank tightening and inflation concerns come back to haunt investors?
BoJo unlikely to lose no-confidence vote
Ahead of all that, the UK PM Bris Johnson is facing a no-confidence vote later this evening, which could prompt sharp moves in the pound and FTSE. Should Johnson lose, he will be forced to stand down as prime minister. But that requires at least 180 votes from his Conservative MPs, which may be a tall order – even if a growing number of Tories – including Jeremy Hunt – are turning their backs towards him. Indeed, with the GBP/USD and FTSE both being among the top risers in their respective fields this morning, it is clear that investors do not expect to see any surprises in the vote.
China’s easing of lockdowns help sentiment
For now, investors are happy that China has moved to ease Covid restrictions, reducing concerns about demand from the world’s largest economy and largest consumer of many commodities. This is why the Shanghai Composite Index closed up nearly 1.3% overnight, as investors looked to add to the gains made during May. China’s gradual re-opening has boosted industrial metals such as copper, which has helped to boost shares in basic resources.
Central Bank tightening could come back to haunt investors
The focus is going to return to monetary policy this week, potentially weighing on optimism that has been trigged by China. So, will inflation and rate-hike concerns come back to rattle the markets?
The Fed remains the most hawkish of central banks out there, although others are also catching up. On Friday we saw a stronger-than-expected US jobs data for May. The data suggests the US Federal Reserve will continue its aggressive tightening to rein in price pressures. Speaking of which, we will US CPI to look forward to on Friday, which is going to be the key data the week. US inflation edged a little lower in April to 8.3% but it remains to be seen whether prices have peaked. If CPI doesn’t come down fast, this could keep stocks under pressure as the Fed will have to continue with its aggressive hiking until price pressures come down meaningfully. The market is fully expecting another 50-bps increase in interest rates on June 15, and another similar hike in July. In fact, Cleveland Fed President Loretta Mester said she would even back a 50-basis point hike in September if inflation has not started to fall back by then. Markets are currently 85% confident that there will be a third 50-basis-point increase in September.
Focus turns to RBA and ECB
Ahead of the Fed’s decision next week, we have the likes of the Reserve Bank of Australia (Tuesday) and European Central Bank (Thursday) to look forward to this week.
- RBA: The Reserve Bank of Australia lifted interest rates by 25 basis points at its last meeting, which was 10 more than expected. It is set to hike again. The main uncertainty is whether it will be a 25bp hike to 0.60% as it did in May or a 40bp increase to 0.75%, back to where the cash rate was pre pandemic and to realign with the 25bp increments it has historically moved the cash rate by.
- ECB: While no rate hikes are expected at the June 9 meeting, Christine Lagarde and her ECB colleagues will use this to prepare the markets for what is to come later in the summer. In July, the ECB is seen lifting the deposit rate from the current -0.5% by a quarter-point. But one thing that is almost certain is that the ECB will announce an end to bond purchases this week. It will therefore formally join global peers tightening monetary policy in the face of hot inflation.
If the above central banks and inflation data this week all point towards more aggressive policy tightening then this, along with ongoing concern over the war in Ukraine, will add to investor worries and once again pressure global stocks.
FTSE testing resistance
Ahead of the above macro events, the FTSE has reached a key area of resistance again between 7645 to 7685ish:
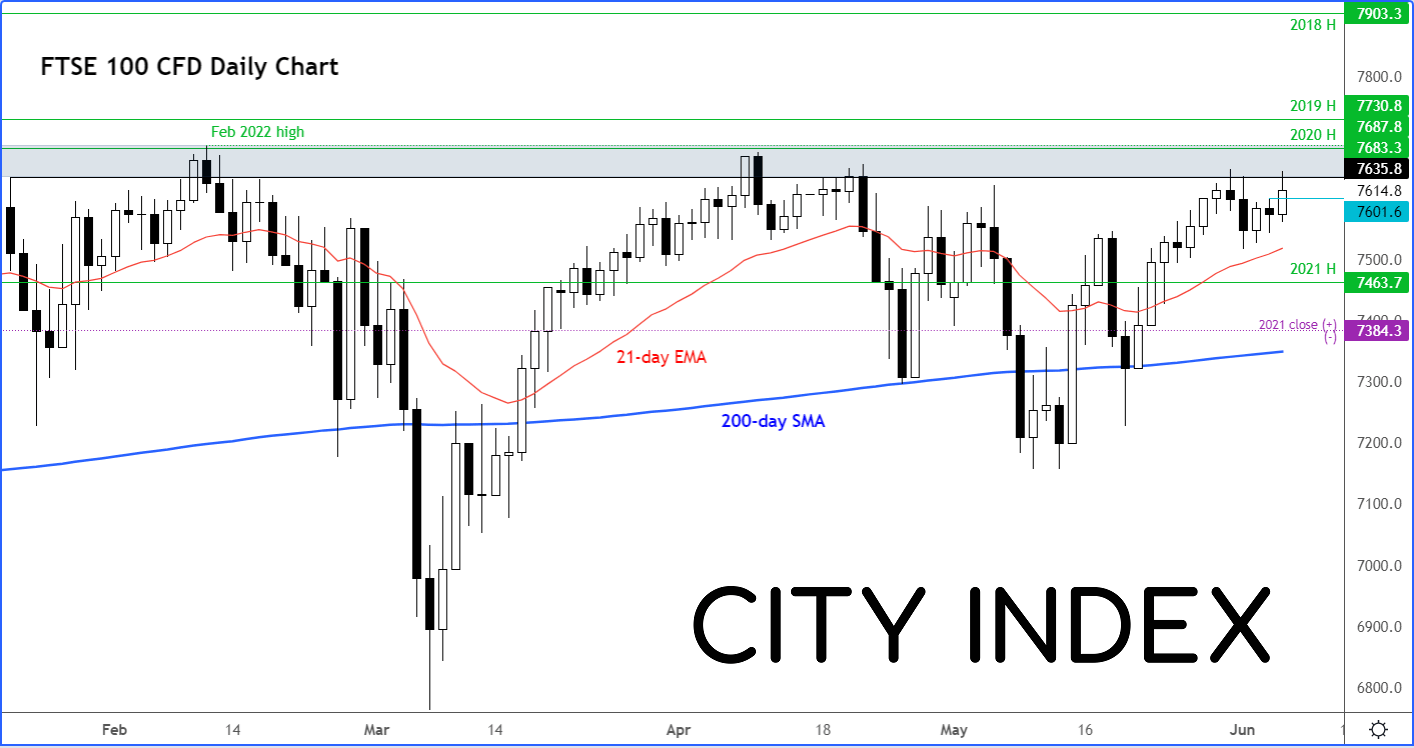
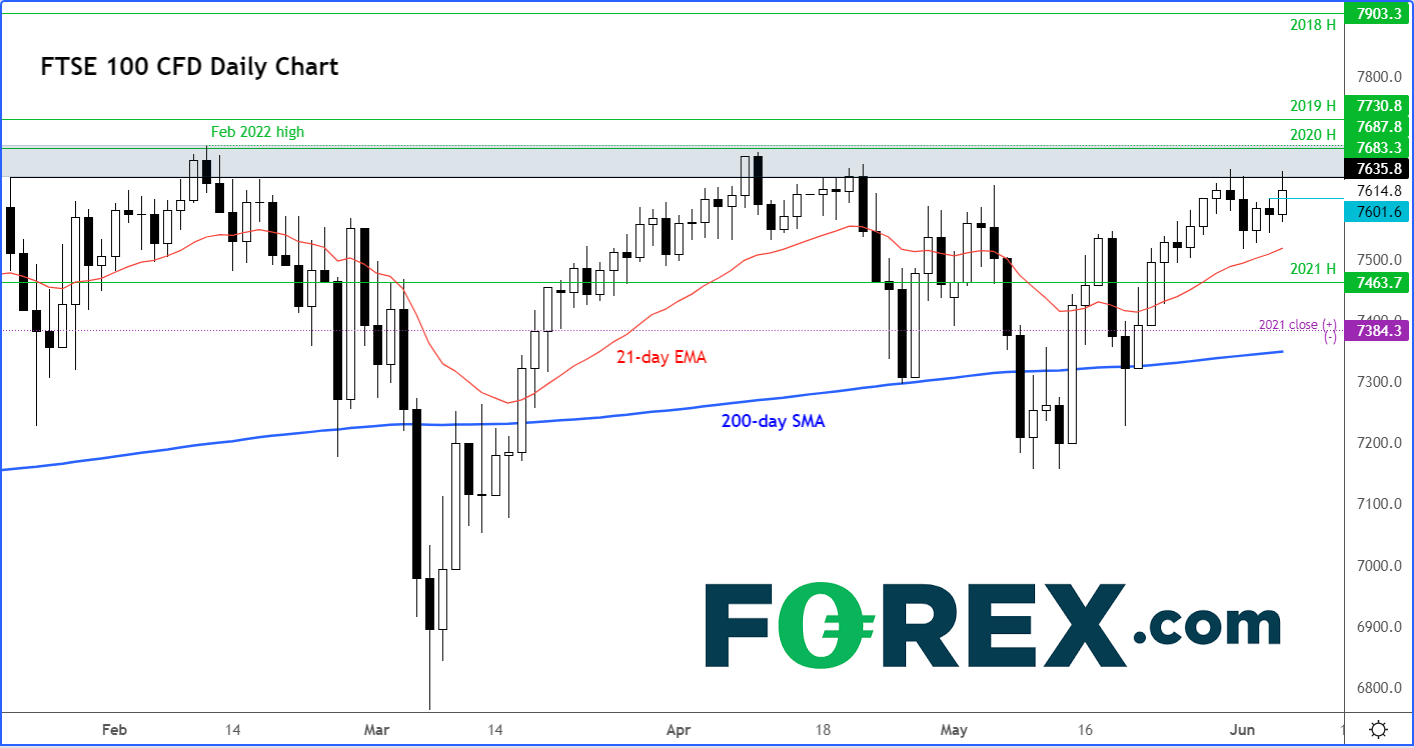
It is possible we could see a reversal here, but bearish speculators must wait to see that before pouncing as the FTSE has been one of the strongest among the major global indices this year.
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log-in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
How to trade with City Index
You can trade with City Index by following these four easy steps:
Open an account, or log in if you’re already a customer
Search for the market you want to trade in our award-winning platform
Choose your position and size, and your stop and limit levels
Place the trade
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.


Gold and silver forecast: Precious metals extend drop but seasonality hopes keeps bullish case alive
It has been a risk off session so far today with stocks, gold and especially silver (-4%) all taking a drop. Gold has fallen to a fresh 2026 low and its now more than $100 below the psychologically important $4,000 mark. A firmer US dollar, rising US rate expectations and fading safe-haven demand have combined to undermine the metal, despite continued central bank buying. This year has so far been a bad one for gold.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.