



Asian Open: Conflicting headlines around Russian Invasion sparks volatility
It was another volatile day’s trade on Wall Street with the US closing its embassy in Kyiv and Ukraine President announcing a Russian invasion could be on Wednesday.
Share this:
Monday US cash market close:
- The Dow Jones Industrial fell -171.89 points (-0.49%) to close at 34,566.17
- The S&P 500 index fell -16.97 points (-0.39%) to close at 4,401.67
- The Nasdaq 100 index rose 14.756 points (0.1%) to close at 14,268.60
Asian futures:
- Australia's ASX 200 futures are down -64 points (-0.9%), the cash market is currently estimated to open at 7,179.90
- Japan's Nikkei 225 futures are down -40 points (-0.15%), the cash market is currently estimated to open at 27,039.59
- Hong Kong's Hang Seng futures are down -99 points (-0.41%), the cash market is currently estimated to open at 24,457.57
- China's A50 Index futures are up 9 points (0.06%), the cash market is currently estimated to open at 14,961.22

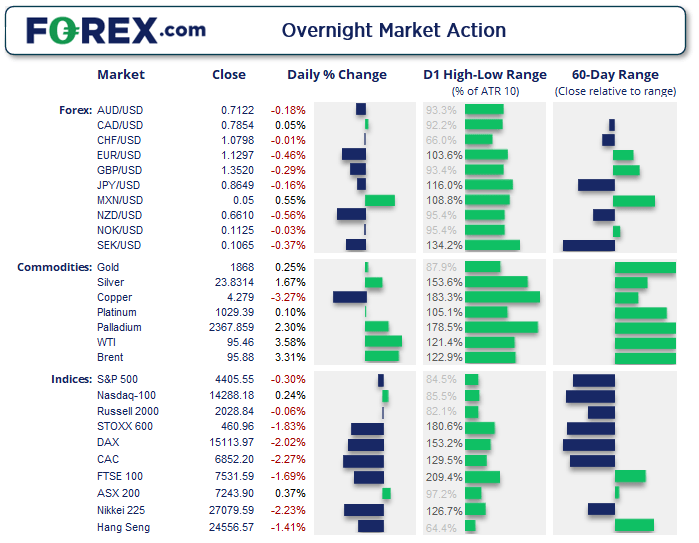
It was another volatile day’s trade on Wall Street with the US closing its embassy in Kyiv and Ukraine President announcing a Russian invasion could be on Wednesday. Earlier reports claimed Russia would continue talks with NATO and the US. And the invasion claim has since been walked back by a senior official which helped US indices recoup earlier losses, with tech stocks even posting a minor gain. Small bullish hammers formed on the Dow Jones and S&P 500 daily charts and the Nasdaq 100 posted a minor gain of around 0.3% by the close.
Yet energy prices weren’t taking any chances on conflicting reports of a Russian invasion, as they simply rose on demand concerns. Crude oil is up around 1.8%, natural gas rose 5.6%, heating oil gained 1.2% and gasoline around 1%.
ASX 200 to get off lightly again today?
The ASX 200 defied the gravity of a Wall Street selloff yesterday, dare we say, may get off lightly again today. The utilities and financial sectors, which account for around 50% of the index, continue to perform well overall and were top performers last week, which is providing a decent level of support for the broader market. And with energy prices higher overnight then logic assumes the energy sector will continue to shine. It’s up 16% YTD, rose over 3% yesterday and looks set to be the top performer again today.
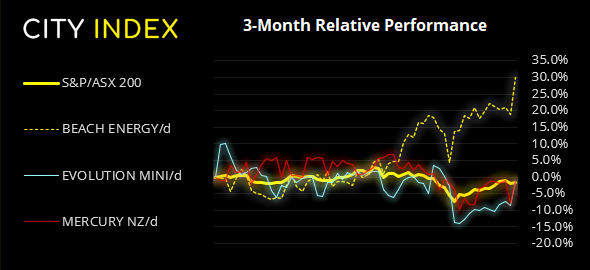

ASX 200: 7243.9 (0.37%), 11 February 2022
- Energy (3.36%) was the strongest sector and Healthcare (-1.37%) was the weakest
- 6 out of the 11 sectors closed higher
- 5 out of the 11 sectors closed lower
- 4 out of the 11 sectors outperformed the index
- 82 (41.00%) stocks advanced, 107 (53.50%) stocks declined
Outperformers:
- +9.43% - Beach Energy Ltd (BPT.AX)
- +7.9% - Evolution Mining Ltd (EVN.AX)
- +7.35% - Mercury NZ Ltd (MCY.AX)
Underperformers:
- -10.8% - Novonix Ltd (NVX.AX)
- -9.52% - Imugene Ltd (IMU.AX)
- -7.89% - Liontown Resources Ltd (LTR.AX)
USD and yen took safe-haven bids
The US dollar was the strongest major throughout most of the session as it enjoyed its safe-haven bid yet, similar to US indices, saw a reversal later in the session to hand back earlier gains. Strong oil prices ultimately helped CAD take the top spot, the US dollar index rose to a 9-day high on the back of a weaker EUR.
NZD/CAD feels the weight of the Loonie


Of all the CAD pairs, NZD/CAD has caught our eye. It remains within an established downtrend on the daily chart and has undergone a corrective phase recently. Yet the bearish hammer at the 38.2% Fibonacci ratio warned that the correction has completed, then yesterday’s bearish range expansion day suggests momentum has now realigned with the dominant bearish trend. Our bias remains bearish beneath the cycle high, although tighter risk management could be considered suing yesterday’s high. Initial target is the cycle low.
Gold continued to rise amidst risk-off trade
The yellow metal has set another YTD high and, at 1870 now sits at its most bullish level since November. 1877.125 is the next key level for bulls to conquer to pave the way for a move to 1900. And its ability to hit that milestone sooner than later is likely tied to expectations of a pending invasion from Russia.
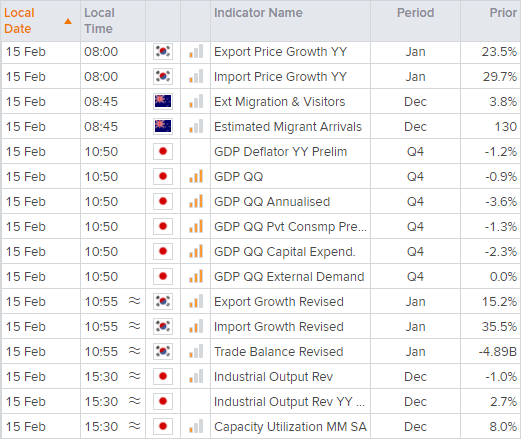
Japan’s Q4 GDP is scheduled for 10:50 AEDT
GDP in the final quarter of 2021 is expected to have rebounded in Japan due to a solid rise in consumption, according to a Reuters poll. The median forecast pencils in a 5.8% annualised rise, up from -3.6% in Q3 with a 2.2% rebound in private consumption expected to be the key driver in its recovery. Yet that could be short lived with estimates for Q1 2022 seeing it slip back into contraction due to the rise in Omicron cases. Industrial output is scheduled for 15:30. Export prices and growth for South Korea are also released today and can be a good proxy for global demand.
Up Next (Times in AEDT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
How to trade with FOREX.com
Follow these easy steps to start trading with FOREX.com today:
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.