



Asian Open: Copper breaks out in style following US CPI
To be fair, plenty of markets broke out during the predominantly weak USD environment, but copper’s large daily volume and clear break of resistance really caught our eye.
Share this:
Wednesday US cash market close:
- The Dow Jones Industrial rose 38.3 points (0.11%) to close at 36,290.32
- The S&P 500 index rose 13.28 points (0.29%) to close at 4,726.35
- The Nasdaq 100 index rose 60.973 points (0.38%) to close at 15,905.10
Asian futures:
- Australia's ASX 200 futures are down 0 points (-0.01%), the cash market is currently estimated to open at 7,438.90
- Japan's Nikkei 225 futures are down -90 points (-0.31%), the cash market is currently estimated to open at 28,675.66
- Hong Kong's Hang Seng futures are up 173 points (0.71%), the cash market is currently estimated to open at 24,575.17
- China's A50 Index futures are up 145 points (0.94%), the cash market is currently estimated to open at 15,656.14
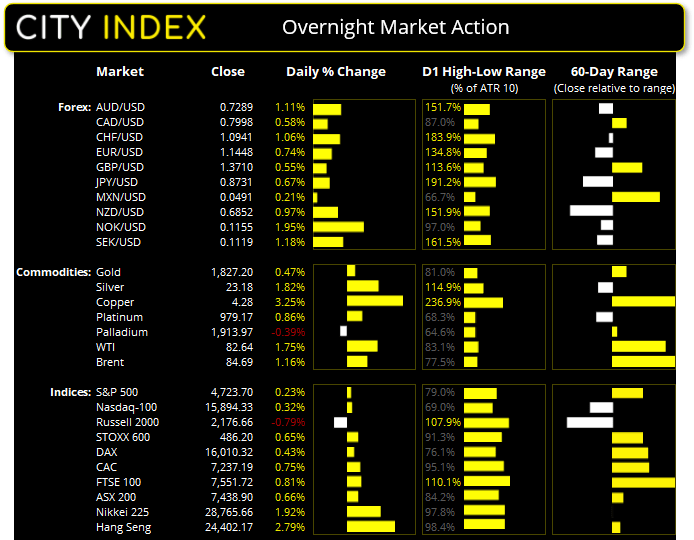
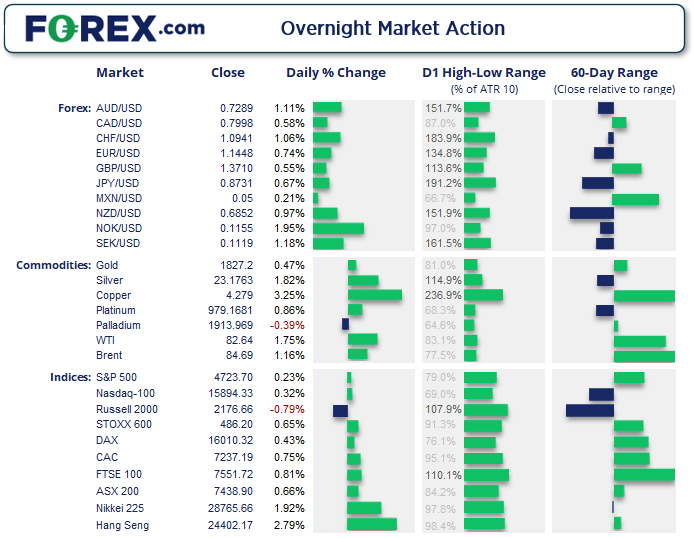
Equity markets weathered the well telegraphed inflation print of 7%, although that may not have been the case had Jerome Powell not soothed inflationary concerns at his confirmation hearing the day prior. The S&P 500 rose 0.2% by the close although (like DJI and Nasdaq) printed small Doji’s. But given the levels of inflation and hawkishness of the Fed that could be taken as a positive sign overall.
The ASX 200 is holding above its 50-day eMA and trend support from the December low, yet 7470 resistance continues to cap. But, even if we are to see a break above here, we’d want to see a break above 7500 before switching to a bullish bias. Until then, we remain neutral.
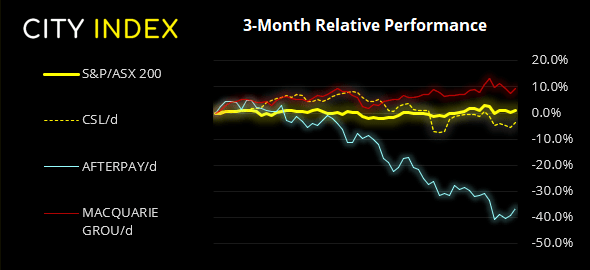
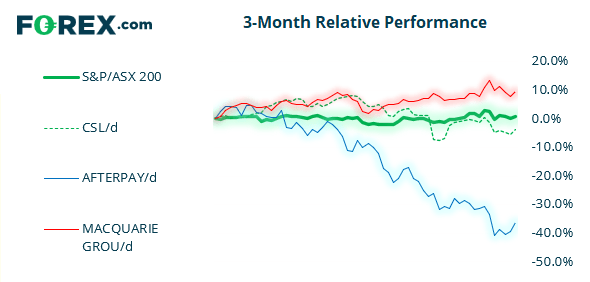
ASX 200: 7438.9 (0.66%), 12 January 2022
- Energy (3.02%) was the strongest sector and Consumer Staples (-0.59%) was the weakest
- 8 out of the 11 sectors closed higher
- 3 out of the 11 sectors closed lower
- 5 out of the 11 sectors outperformed the index
- 133 (66.50%) stocks advanced, 51 (25.50%) stocks declined
Outperformers:
- +1.87% - CSL Ltd (CSL.AX)
- +4.75% - Afterpay Ltd (APT.AX)
- +1.64% - Macquarie Group Ltd (MQG.AX)
Underperformers:
- -4.19% - Domino's Pizza Enterprises Ltd (DMP.AX)
- -3.52% - Reece Ltd (REH.AX)
- -2.34% - Metcash Ltd (MTS.AX)
US inflation hits its high consensus, dollar gets whacked
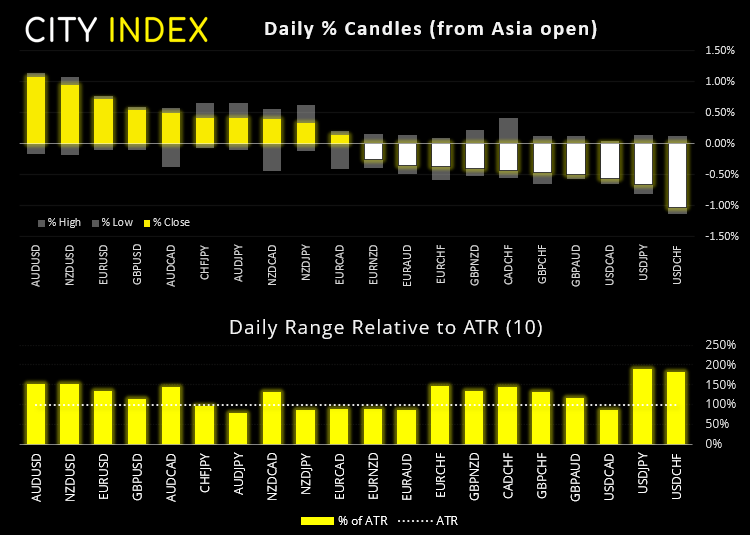
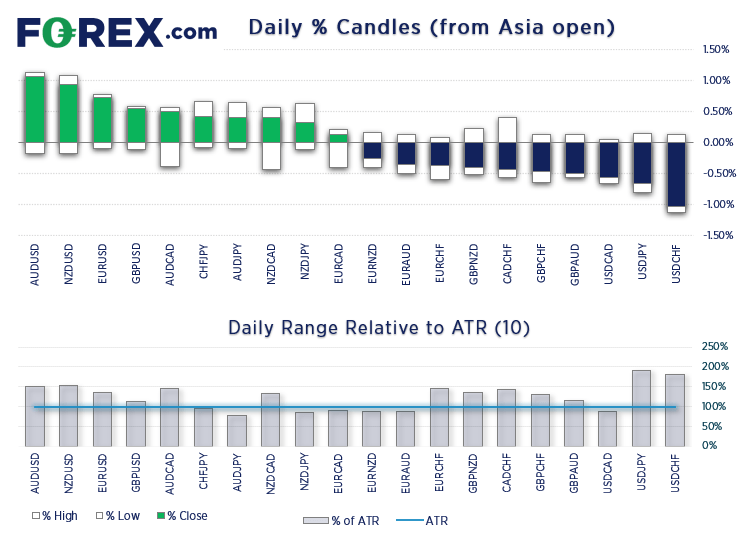
Inflation rose 7% y/y as expected in December, which is its highest rate in 39 years. Core CPI, which excluded food and energy rose 5.5% y/y, it’s highest level since Feb 1991. As Joe Biden and his low approval rating know full well, these inflation numbers are not to be taken lightly. But form a trader’s perspective they did come in as expected which removes the element of surprise. And with Jerome Powell effectively confirming a March hike, markets pricing in an 80% chance of said hike and many expecting 3 more this year, traders were keen to book profits after the release.
The US dollar was the weakest currency and fell broadly against all of its major peers, which saw USD/CHF fall over 1% and USD/JPY break firmly below 115. The US dollar index finally broke out of its 2-month range, below 95.50 support and has challenged the June trend support. Naturally, this allowed the euro to hit a 2-month high and close firmly above 1.14. The Australian dollar was the strongest major currency, with the Swiss franc and New Zealand dollar close behind and all rising over 1% against the US dollar.
Commodities embraced the weaker dollar with metals (mostly) leading the way
With a weaker dollar and strong (even if a bit too hot) economy, commodities were quick to rally. The Thomson Reuters core commodity index rose another 1.5% after hitting a 7-year high yesterday. Natural gas is up nearly 40% over the past 8 days alone and was the strongest commodity of the session, with oil rising around 1.5%. Excluding palladium, metals were also broadly higher with gold reaching a 1-week high of 1227, silver rose 1.8% and closed firmly above $23. Yet it was arguable copper which stole the metal show.
Copper breaks out with a vengeance
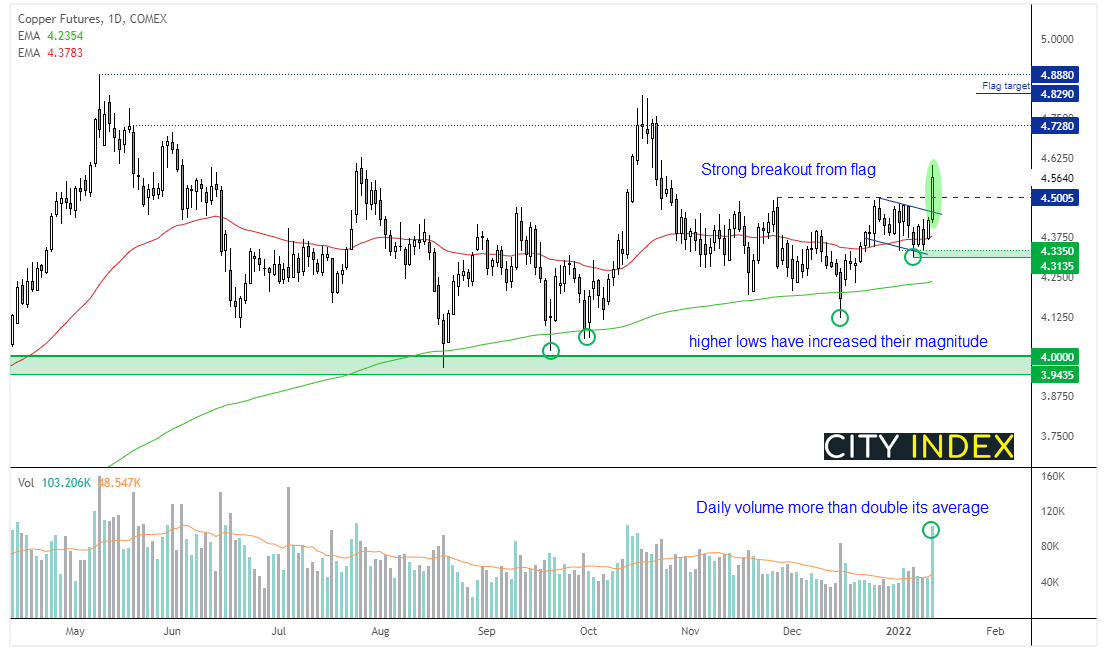
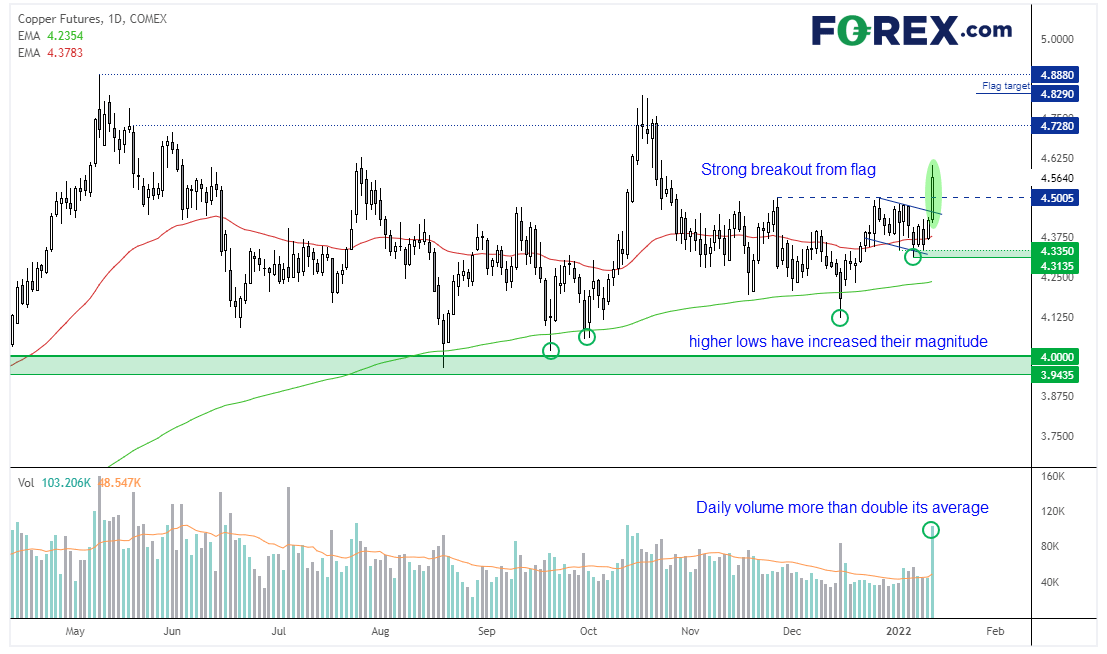
We noted copper’s potential to breakout ahead of yesterday’s European open, and it did not disappoint. Rising over 4% by its daily high on more than double it’s daily average volume, it’s a classic breakout from a flag pattern on the daily chart. The flag projects a target near the October high around $4.83 and easily cleared $4.50 resistance on a closing bases. Given it has been slowly building a base since the $4.00 low and higher lows have increased in magnitude, it is possible we may see it return to its loner-term trend. But for now, we’re happy to target the highs around $4.75 whilst prices hold above the $4.30 low. But if this is flag breakout then prices should not retreat back beneath the flag itself.
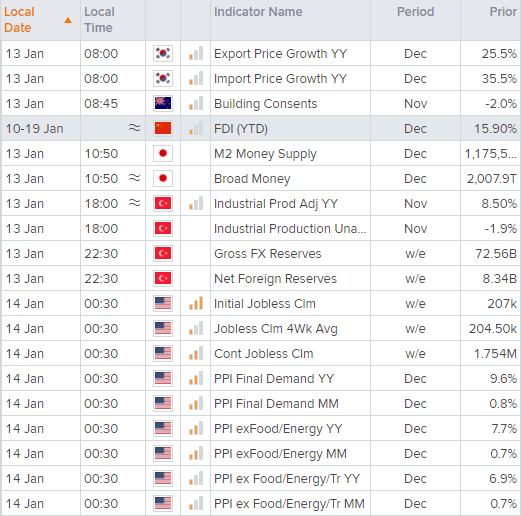
Up Next (Times in AEDT)
How to trade with City Index
You can easily trade with City Index by using these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
Related tags:


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

NZD/USD Forecast: Kiwi faces historic breakdown as RBNZ survey looms
NZD/USD is teetering above support that held through the pandemic and Liberation Day turmoil. With RBNZ hawks repeatedly disappointed, today's inflation expectations survey could open the door to a slide towards the GFC lows.

USD/JPY, AUD/JPY: Central Bank Divergence Creates Two-Way Risk
USD/JPY eyes a breakout above 160, while AUD/JPY faces further losses as Fed, RBA and BoJ interest rate expectations diverge.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.