



ASX200 Afternoon Report August 3rd 2022
The ASX200 trades 24 points lower at 6973 at 3.20 pm Sydney time.
Share this:
The ASX200 trades 24 points lower at 6973 at 3.20 pm Sydney time.
The ASX200 has pared early losses after a quickfire 80-point plunge shortly after the open, sparking memories of the selloff in June.
The weaker session follows losses on Wall Street, and a round of hawkish comments from Fed officials, in response to a dramatic easing in Financial Conditions that followed last week's FOMC meeting.
Financial Conditions consist of stock prices, credit spreads, the U.S dollar and interest rates, all of which have gone the wrong way for the Fed in recent days as it attempts to clamp down on inflation at multi-decade highs.
In that respect, the fall in U.S 10-year yields from 3.5% to 2.5% over the past six weeks is likely done for now. Stock markets will be forced to reacquaint themselves with the headwinds of higher yields and a stronger U.S dollar in the sessions ahead.
This accounts for the fall today in the Consumer Discretionary Sector, led lower by Domino's Pizza which fell 3.3% to $71.44, Star Entertainment fell 2.6% to $3.01, Aristocrat Leisure fell 2% to $34.62, and Wesfarmers fell 1.5% to $46.86.
Falls also for the Financial Sector. Westpac fell 1.45% to $21.68, CBA fell 1.34% to $100.52, NAB fell 0.9% to $30.68, ANZ fell 0.66% to $22.66, while Macquarie fell 1.25% to $176.58.
The energy sector has edged lower ahead of this week's OPEC+ meeting, which is likely to disappoint as producers cast a nervous glance toward global recession risks. Santos fell 1.86% to $7.11; Woodside Energy fell 0.77% to $32.43. Beach Energy bucked the trend rising by 0.56% to $1.81.
The IT Sector has been the day's outperformer as it added 2%, helped by the continued renaissance of the BNPL sector. Zip surged 10.25% to $1.35, Sezzle added 6% to $1.13, EML Payments climbed 6.5% to $1.07, Tyro Payments added 7% to $0.83c and Megaport added 5.5% to $8.66.
The Materials sector has gained led by Lynas Rare Earths, which added 7.31% to $9.53. Mineral Resources added 3.9% to $55.16, South 32 added 1.6% to $3.80, FMG added 0.8% to $18.04, and BHP gained 0.13% to $38.63.
Lithium stocks have continued their rebound, led by Lake Resources, which added 8% to $0.87c. Galan Lithium added 6.17% to $1.21, Vulcan Energy added 3.9% to $7.44, and Core Lithium added 2.9% to $1.16.
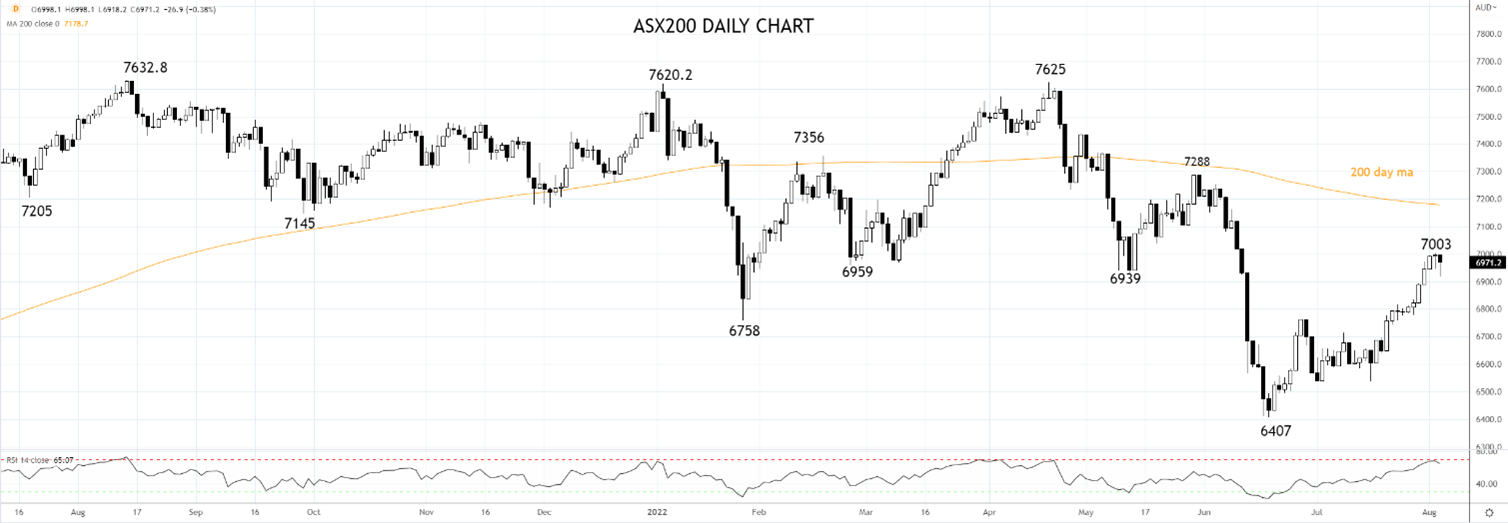
In theory, the ASX200's second consecutive daily close above 6960 negates the technical damage caused by the selloff in June. However, as the rally in U.S equity markets appears close to completion, we will hold off for the time being on moving to a more positive bias for the local bourse.
Source Tradingview. The figures stated are as of August 3rd, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
The ASX200 trades 24 points lower at 6973 at 3.20 pm Sydney time.
The ASX200 has pared early losses after a quickfire 80-point plunge shortly after the open, sparking memories of the selloff in June.
The weaker session follows losses on Wall Street, and a round of hawkish comments from Fed officials, in response to a dramatic easing in Financial Conditions that followed last week's FOMC meeting.
Financial Conditions consist of stock prices, credit spreads, the U.S dollar and interest rates, all of which have gone the wrong way for the Fed in recent days as it attempts to clamp down on inflation at multi-decade highs.
In that respect, the fall in U.S 10-year yields from 3.5% to 2.5% over the past six weeks is likely done for now. Stock markets will be forced to reacquaint themselves with the headwinds of higher yields and a stronger U.S dollar in the sessions ahead.
This accounts for the fall today in the Consumer Discretionary Sector, led lower by Domino's Pizza which fell 3.3% to $71.44, Star Entertainment fell 2.6% to $3.01, Aristocrat Leisure fell 2% to $34.62, and Wesfarmers fell 1.5% to $46.86.
Falls also for the Financial Sector. Westpac fell 1.45% to $21.68, CBA fell 1.34% to $100.52, NAB fell 0.9% to $30.68, ANZ fell 0.66% to $22.66, while Macquarie fell 1.25% to $176.58.
The energy sector has edged lower ahead of this week's OPEC+ meeting, which is likely to disappoint as producers cast a nervous glance toward global recession risks. Santos fell 1.86% to $7.11; Woodside Energy fell 0.77% to $32.43. Beach Energy bucked the trend rising by 0.56% to $1.81.
The IT Sector has been the day's outperformer as it added 2%, helped by the continued renaissance of the BNPL sector. Zip surged 10.25% to $1.35, Sezzle added 6% to $1.13, EML Payments climbed 6.5% to $1.07, Tyro Payments added 7% to $0.83c and Megaport added 5.5% to $8.66.
The Materials sector has gained led by Lynas Rare Earths, which added 7.31% to $9.53. Mineral Resources added 3.9% to $55.16, South 32 added 1.6% to $3.80, FMG added 0.8% to $18.04, and BHP gained 0.13% to $38.63.
Lithium stocks have continued their rebound, led by Lake Resources, which added 8% to $0.87c. Galan Lithium added 6.17% to $1.21, Vulcan Energy added 3.9% to $7.44, and Core Lithium added 2.9% to $1.16.
In theory, the ASX200's second consecutive daily close above 6960 negates the technical damage caused by the selloff in June. However, as the rally in U.S equity markets appears close to completion, we will hold off for the time being on moving to a more positive bias for the local bourse.
Source Tradingview. The figures stated are as of August 3rd, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Brazil Elections: Is Investor Confidence Beginning to Fade?
One of the most relevant events for emerging markets in recent sessions has been the outcome of Brazil’s presidential election. Following Lula da Silva’s victory in the second round, investor sentiment began to deteriorate noticeably. This can be observed in both the iShares MSCI Brazil ETF and the VanEck Brazil Small-Cap ETF, two important benchmarks for tracking the Brazilian equity market, both of which have posted declines of more than 15% at the start of the week.


ASX 200 Outlook: A Rates Trade Disguised as a Stock Market?
Australian bond futures have exhibited a far stronger relationship with the ASX 200 than Wall Street over recent months. Now both markets are displaying remarkably similar price structures.
Dow Jones Analysis: Is the DJIA Making a Comeback?
Recent trading sessions have become increasingly relevant for the Dow Jones, as the index has started to regain bullish momentum heading into the end of the week. Over the last three sessions, the DJIA has advanced by more than 0.6%, allowing buying pressure to regain prominence and raising the possibility of a more consistent short-term recovery.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.