

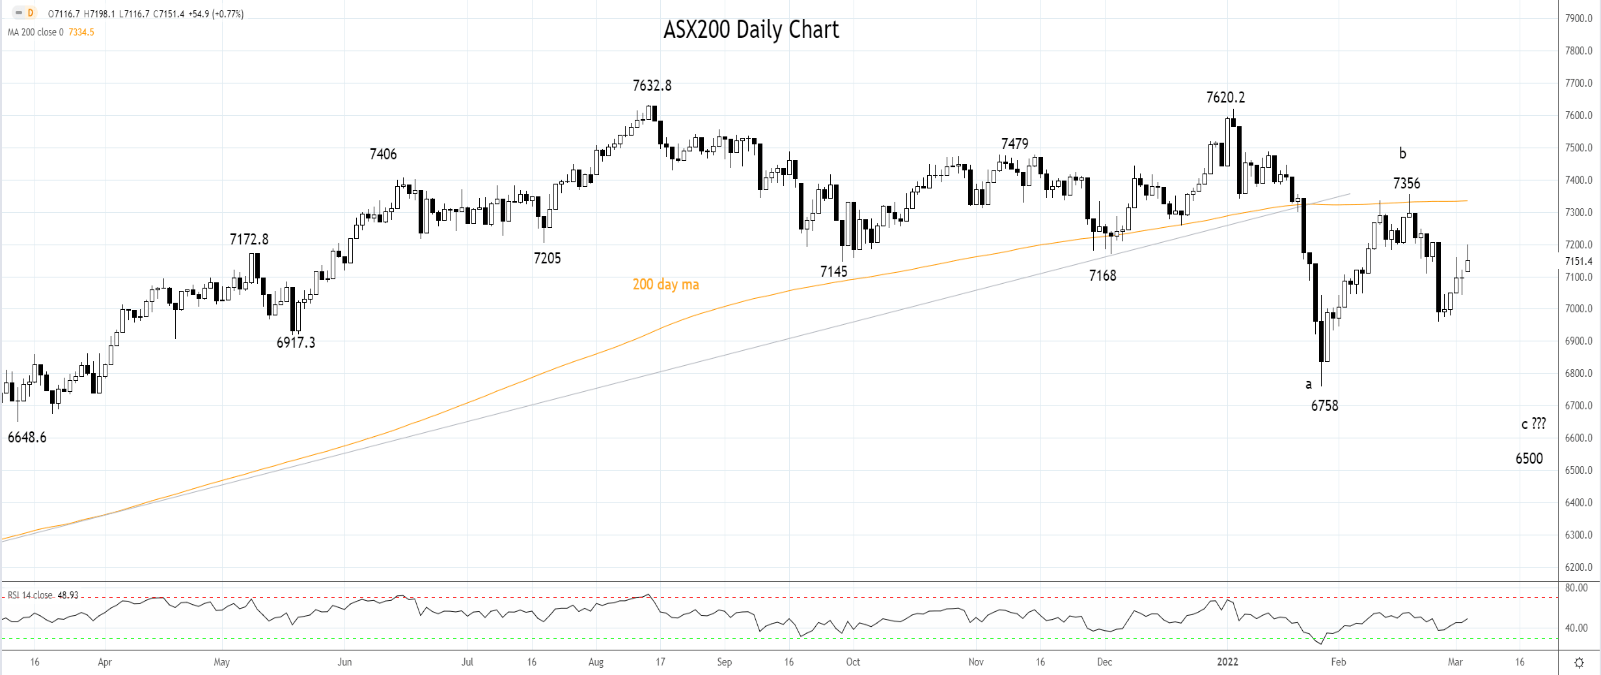


ASX200 Afternoon Wrap 3rd of March
Surging commodity prices have helped the ASX200 lock in a fifth straight day of gains to close at 7151, +34 points eyeing the 7200 level that it broke down from last week following the Russian invasion of Ukraine.
Share this:
In a throwback to pre the current ESG era, it’s been coal mining stocks that have been the star of today’s show, sparked by sanctions on Russia that have resulted in extreme panic in the coal futures market overnight. ICE Newcastle coal futures rallied +46% in a single session.
Russia produces around 15% of both met coal (steel making) and thermal coal (power generation). Elsewhere, Indonesian coal exports are down 20% this year while Australian exports are also lower, making the market very tight and more susceptible to shocks.
In response, Whitehaven Coal (WHC) is up 10.61% today to close at $3.96, Yancoal (YAL) closed 10.98% higher at $4.75, while New Hope Coal (NHC) added 4.27% to close at $2.93.
Crude oil futures surged another 3.64% during today’s session in Asia to be trading near $114.50 p/bbl, up a jaw-dropping 25% for the week. The latest leg of the rally came after buyers of crude oil rejected Russian supply overnight and as OPEC+ maintained its existing policy of increasing output by 400k bpd, despite calls for a supply increase.
Beach Energy (BPT) has added 4.67% to close at $1.68. Origin Energy (ORG) added 3.55% to close at $5.84, while Woodside Petroleum (WPL) gained 2.96% to close $31.34.
Another strong day also for the materials sectors as the price of iron ore futures rallied 9% in Asia. Fortescue Metals Group (FMG) added 4.20% to close at $19.37, Rio Tinto (Rio) added 3.72% to close at $127.85, and BHP Group (BHP) finished the session 3.60% higher at $50.06.
In the day's two key economic events, the notoriously volatile data series that is Australian building approvals collapsed in January, down by 27.9%. The decline was much larger than economists had expected (consensus estimate of -3%).
The January trade surplus increased to $12.9bn from $8.8bn in the prior month. Exports rose strongly, up by 7.6% and imports were down by 1.6% which tells a neat story of Australia’s Terms of Trade currently making fresh record highs.
Source Tradingview. The figures stated are as of March 3rd, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
How to trade with City Index
You can trade with City Index by following these four easy steps:
- Open an account, or log in if you’re already a customer
• Open an account in the UK
• Open an account in Australia
• Open an account in Singapore
- Search for the company you want to trade in our award-winning platform
- Choose your position and size, and your stop and limit levels
- Place the trade
In a throwback to pre the current ESG era, it’s been coal mining stocks that have been the star of today’s show, sparked by sanctions on Russia that have resulted in extreme panic in the coal futures market overnight. ICE Newcastle coal futures rallied +46% in a single session.
Russia produces around 15% of both met coal (steel making) and thermal coal (power generation). Elsewhere, Indonesian coal exports are down 20% this year while Australian exports are also lower, making the market very tight and more susceptible to shocks.
In response, Whitehaven Coal (WHC) is up 10.61% today to close at $3.96, Yancoal (YAL) closed 10.98% higher at $4.75, while New Hope Coal (NHC) added 4.27% to close at $2.93.
Crude oil futures surged another 3.64% during today’s session in Asia to be trading near $114.50 p/bbl, up a jaw-dropping 25% for the week. The latest leg of the rally came after buyers of crude oil rejected Russian supply overnight and as OPEC+ maintained its existing policy of increasing output by 400k bpd, despite calls for a supply increase.
Beach Energy (BPT) has added 4.67% to close at $1.68. Origin Energy (ORG) added 3.55% to close at $5.84, while Woodside Petroleum (WPL) gained 2.96% to close $31.34.
Another strong day also for the materials sectors as the price of iron ore futures rallied 9% in Asia. Fortescue Metals Group (FMG) added 4.20% to close at $19.37, Rio Tinto (Rio) added 3.72% to close at $127.85, and BHP Group (BHP) finished the session 3.60% higher at $50.06.
In the day's two key economic events, the notoriously volatile data series that is Australian building approvals collapsed in January, down by 27.9%. The decline was much larger than economists had expected (consensus estimate of -3%).
The January trade surplus increased to $12.9bn from $8.8bn in the prior month. Exports rose strongly, up by 7.6% and imports were down by 1.6% which tells a neat story of Australia’s Terms of Trade currently making fresh record highs.
Source Tradingview. The figures stated are as of March 3rd, 2022. Past performance is not a reliable indicator of future performance. This report does not contain and is not to be taken as containing any financial product advice or financial product recommendation
- Open a Forex.com account, or log in if you’re already a customer.
- Search for the pair you want to trade in our award-winning platform.
- Choose your position and size, and your stop and limit levels.
- Place the trade.
Related tags:



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
China's steel slump leaves iron ore bulls under the pump
Iron ore has broken major support, threatening a return to the lows of 2022 as mounting evidence of weakness in China's steel sector reinforces the bearish outlook.

DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

Tankers Still Get Hit but Brent Crude Oil Keeps Falling
Brent crude oil has turned bearish after breaking its uptrend, as de-escalation signals outweigh tanker strikes near the Strait of Hormuz.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.