



Could EU stocks find some much needed love
So, there is a good possibility, we think, that the stock markets, especially in Europe, may find support soon. Central banks could very well decide to keep monetary conditions looser for longer than previously thought amid a weakening global economy and lower oil prices reducing inflationary pressures. Meanwhile bargain hunters could provide their support for downbeat stocks that have good fundamentals.
Share this:

With the US out celebrating thanksgiving holiday today, the afternoon session should be a quieter one. This morning, though, volatility has remained elevated as the pound surged higher on the back of a leaked draft text on the UK’s future relationship with the EU after Brexit. Meanwhile, European stock indices started well into the red despite yesterday’s sharp rebound. But despite today’s pullback, a sizeable rally for stocks could potentially be on the way soon – if not today, then perhaps in the near future.
Monetary conditions looser for longer could support equities
Granted, there has been no major fundamental development to help shore up investor confidence. However, the stock markets could still rise nonetheless, for a start on the back of short covering given the extent of recent falls. But the potential rebound need not be a short covering rally. With the global economy apparently slowing down again, and given the risks stemming from the Italian budget and Brexit, to name but a few, central banks may decide against tightening their respective monetary policies aggressively in order to avoid another downturn. Indeed, there is a real risk that the German economy could fall into a technical recession after it contracted more than expected in the third quarter. Consequently, Friday’s Eurozone PMI data will be scrutinised closely. The recent slowdown of growth here is in part due to the emerging market currency crisis hitting demand for exports of luxury goods. With EM currencies still not much higher from their worst levels hit in the summer, and given the potential for further escalation in the US-China trade dispute, demand could be hit even more – although the downside risks may well have been priced in by now. In fact, a couple of Federal Reserve members have already expressed concerns about these risks last week and hinted at the prospects of slower rate hikes going forward. Meanwhile, inflationary pressures stemming from the crude oil market should also be weakening given the big recent falls for Brent and WTI amid concerns over excessive supply and slower demand growth for the black stuff. This is an additional reason why central banks may decide to keep monetary conditions extremely loose for the foreseeable future.
So, there is a good possibility, we think, that the stock markets, especially in Europe, may find support soon. Central banks could very well decide to keep monetary conditions looser for longer than previously thought amid a weakening global economy and lower oil prices reducing inflationary pressures. Meanwhile bargain hunters could provide their support for downbeat stocks that have good fundamentals.
FTSE could outperform
While we still haven’t seen a clear reversal pattern for the major indices as none of them have broken a previous high to form a higher high – a prerequisite for us to turn bullish – there has been tentative signs that the selling pressure may be easing a little. Indeed, the FTSE managed to rally yesterday and created an apparent bullish picture in that it formed a higher low relative to its low at the end of October. Meanwhile other European indices, such as the DAX, also closed in the green. However, the German benchmark stock index still created a lower low for the year before bouncing back sharply. The FTSE, therefore, continued to show relative strength in that it formed a higher low. Granted, the UK benchmark index hasn’t showed any bullish follow-through yet, which may be due in part to today’s sizeable rebound in the pound, but it could still turnaround and outperform its peers. Technically, the FTSE is still holding that long-term support in the 6900 region, so there is indeed a good chance it could stage a recovery here. That being said, we would certainly not rule out the possibility for even more short term pain than gain for stock market bulls given that the trend for the global indices is currently bearish. In other words, momentum could potentially push the indices further lower in the short term. But we are now on the lookout for bullish price action to emerge.
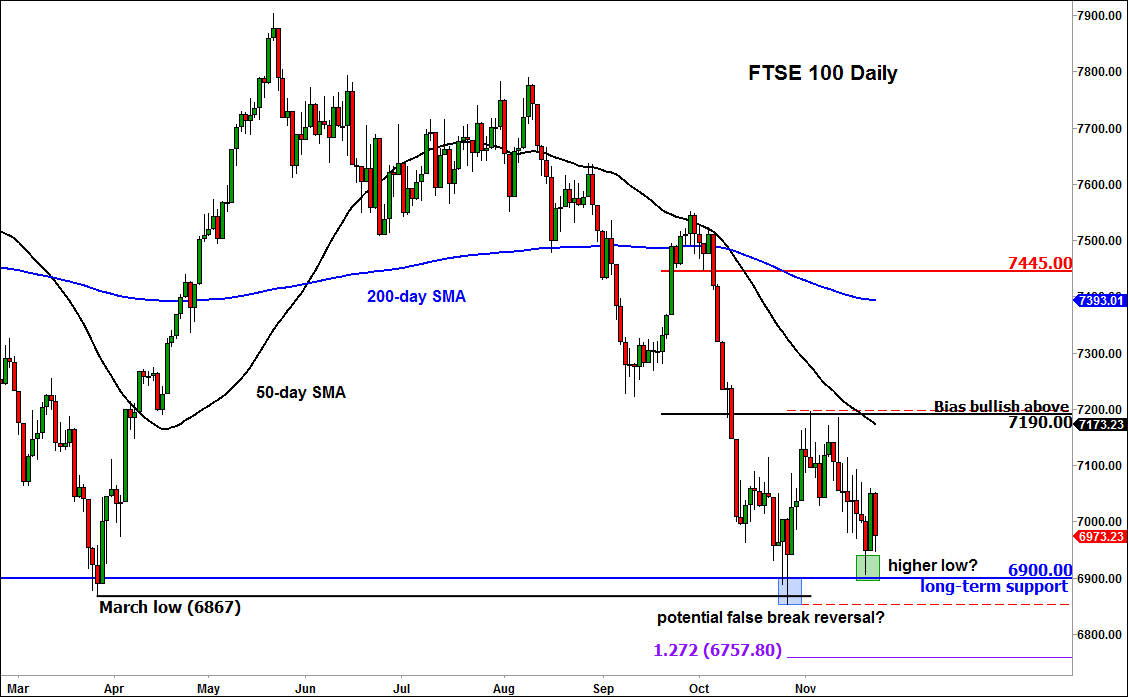
Source: eSignal and FOREX.com. Please note, this product is not available to US customers.




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
Brazil Elections: Is Investor Confidence Beginning to Fade?
One of the most relevant events for emerging markets in recent sessions has been the outcome of Brazil’s presidential election. Following Lula da Silva’s victory in the second round, investor sentiment began to deteriorate noticeably. This can be observed in both the iShares MSCI Brazil ETF and the VanEck Brazil Small-Cap ETF, two important benchmarks for tracking the Brazilian equity market, both of which have posted declines of more than 15% at the start of the week.

Dow Jones Analysis: Is the DJIA Making a Comeback?
Recent trading sessions have become increasingly relevant for the Dow Jones, as the index has started to regain bullish momentum heading into the end of the week. Over the last three sessions, the DJIA has advanced by more than 0.6%, allowing buying pressure to regain prominence and raising the possibility of a more consistent short-term recovery.
ASX 200 Slides as Oil, Yields and Rate Risks Hit Sentiment
The ASX 200 suffered its worst week in six months as surging oil, higher bond yields and renewed rate-hike bets drove a broad risk-off move.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.