



Crude oil drops for third day amid growing demand concerns
Crude oil prices are lower for the third day, after Brent and WTI both hit new highs for the year on Monday following a sharp kick-back rally in January.
Share this:

Crude oil prices are lower for the third day, after Brent and WTI both hit new highs for the year on Monday following a sharp kick-back rally in January. The political crisis in Venezuela was part of the reason prices were rising in previous weeks, but this seems to have been priced in by now. In any case, it is likely that other OPEC countries will step up production to compensate for any potential loss from Venezuela due to sanctions from the West. Looking ahead, the 2019 demand outlook for oil is not great, while the prospects of increased shale supply and competition elsewhere could keep the pressure on prices. That being said, the downside could be limited as the OPEC and 10 partner producers outside the cartel are supposed to be actively managing output in an effort to rebalance the market.
In the near term, demand concerns could keep prices under pressure, with China slowing down and concerns are rising over a recession in Germany. In a latest sign of a slowdown in Eurozone’s largest economy, German factory orders unexpectedly slumped 1.6% in December. After a 0.2% decline in the third quarter, some economists predict the German economy to have shrank again in Q4, thus putting it in a technical recession. The official growth figure from Destatis will be published next Thursday. Italy, meanwhile, has already fallen in a recession as its GDP contracted 0.2% in Q4 following a contraction of 0.1% in the July to September period. So, things aren’t great in the Eurozone, and this bodes ill for demand for oil from one of the biggest economic regions of the world. Meanwhile, the latest factory data from the world’s largest economy wasn’t great either on Monday, with orders here unexpectedly falling by 0.6% month-on-month in December following a 2.1% decline the month before.
The very short-term focus will now be on the official US oil inventories data from the Energy Information Administration (EIA) due for release later this afternoon. Last night, the American Petroleum Institute (API) reported inventory data that disappointed expectations with a headline stockpiles build of 2.5 million barrels vs. 1.4 million expected. The potential is therefore there for the EIA data to disappoint expectations today, potentially leading to renewed selling pressure in oil. However, if we see a surprise drawdown then this could potentially cause prices to rebound.
WTI: Breaking down from a bear flag?
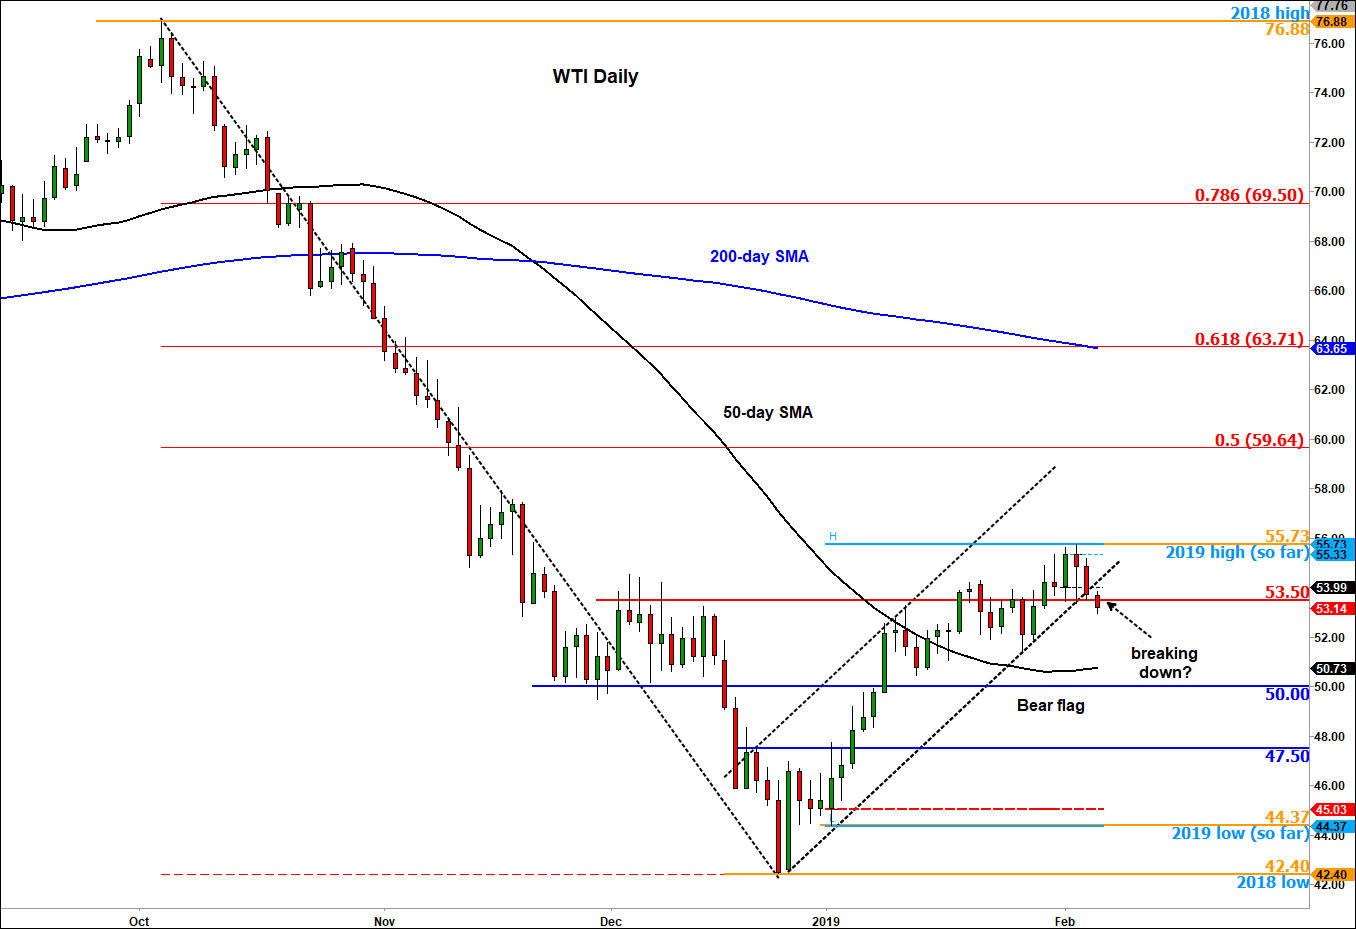
From a technical point of view, the latest drop in oil prices could be a worrying sign for the bulls. For one, both Brent and WTI have so far failed to hold above January’s highs. Admittedly, the month of February has just begun. Still, you’d expect to see some immediate follow-through in momentum had the trend still been bullish. For another, the WTI contract is breaking below its short-term bullish channel, or a bear flag pattern if you believe the trend since October is still bearish.
With WTI breaking below the $53.50 short-term support and outside of the flag pattern, the bears would be keen to see if there will be acceptance below this level now. If so, prices could head sharply lower over the coming days with the potential to drop to the next big level at $50.00, or even lower over time. However, if WTI were to go back above the broken $53.50 level now, and hold there on a closing basis, then this would suggest selling pressure was weak. In this potential scenario we could see a quick rally back to towards and possibly above the highs of this year at $55.70s.
Source: eSignal and FOREX.com. Please note, this product is not available to US clients
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Forecast: NDX falls ahead of Nvidia’s earnings & Anthropic’s debut this week
U.S. stocks are heading for a weaker open amid a challenging macro backdrop and with AI-linked stocks once again under pressure ahead of Nvidia's results later this week. Attention is also turning to Anthropic's highly anticipated IPO.


Crude Oil Weekly Outlook: Geopolitics vs Oversupply Risks
Crude Oil Weekly Outlook: The IEA has flagged the risk of an oil supply surplus since the Iran war began. Yet WTI and Brent have held onto bullish rebounds from key support near 84 and 89, respectively, as geopolitical risks persist.

S&P 500 forecast: SPX struggles for direction ahead of PPI data
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.