



Crude Oil Price Outlook: Strait of Hormuz Scenario Analysis
Crude Oil Price Outlook: WTI and Brent are tracing stable price action between $90 and $100 on IEA and Russian oil supply alternatives, maintaining a bullish risk for global markets in terms of inflation, as energy infrastructure and the Strait of Hormuz in the Middle East remain at risk.
Share this:
WTI and Brent continue to trade within the $90–$100 range, supported by IEA and Russian supply alternatives, while maintaining upside risks for inflation as tensions around energy infrastructure and the Strait of Hormuz persist.
The Fed is expected to deliver its rate decision and economic outlook today during the FOMC meeting, as the DXY holds above the 99.50 support. This keeps global indices on a cautious uptrend, while the dollar shows signs of a mild pullback. Wait-and-see scenarios, in line with rate hold expectations, are anticipated to gradually absorb inflationary shocks stemming from energy and petrochemical supply disruptions, which are expected to reflect in consumer prices within 4–8 weeks should the conflict persist.
Below are three possible scenarios for the Strait of Hormuz and crude oil price action, followed by long-term and technical outlooks for Brent and WTI:
- Scenario 1 — Rapid de-escalation (low probability)
Naval escorts become operational by the end of March, a ceasefire framework emerges in Q2, and tanker confidence gradually returns. Brent retraces below the June 2025 conflict highs toward $75, unwinding the geopolitical risk premium. This remains the least likely outcome, as Iran’s leadership has been explicit about keeping the Strait closed, and no credible resolution framework is currently in sight.
- Scenario 2 — Prolonged disruption, partial bypass (medium probability) The Strait remains effectively closed through H1 2026. Pipeline workarounds and IEA reserve releases provide only partial relief, with 400 million barrels covering roughly 20 days of normal Strait flows. Crude holds in the $90–$110 range, inflation pressures build globally, and Russia deepens its role in Asian markets as a structural beneficiary of Gulf supply disruptions. The full inflation impact through petrochemicals, plastics, and fertilizers is still 4–8 weeks away from fully feeding into consumer prices, suggesting that the worst of this scenario, including potential global market drawdowns, may still lie ahead.
- Scenario 3 — Full closure with key infrastructure strikes (increasing risk)
Iran expands its targeting to include bypass alternatives and critical energy infrastructure, lifting risk sentiment and crude prices higher. Central banks face a stagflationary backdrop, while recession risks rise sharply. From a technical perspective, a sustained break above $115 on WTI and Brent opens the path toward $130, with $150 in scope. Futures markets continue to underprice this risk, as reflected in the $38 premium of physical Dubai crude over paper markets.
Technical Analysis: Quantifying Uncertainty
Brent Price Outlook: 2-Week Time Frame – Log Scale

Source: Trading view
Brent price action is currently stalling below the 2022 highs and the 118 resistance, aligned with the 50% Fibonacci extension of the trend between 69.20 in February 2026, the 118 peak, and the recent 98 low. Three zones are outlined on the chart in line with the previous scenarios:
- Bullish scenario: a close above 115 and 118 boosts price action toward 125, 130, and 150, in line with Fibonacci extension levels of 61.8%, 78.6%, and 100%.
- Short-term bearish scenario: the base case remains the stable range between 98 and 110. A close below 98 supports a short-term correction toward the 2023 highs near 93.60 and the 2024 highs near 88, before re-exposing the June 2025 highs, with resistance aligning near the 78 mark from the previous Middle East conflict.
- Long-term bearish scenario: a close below last year’s conflict highs, under 78 and 75, extends consolidation risks toward 74 and 69 respectively.
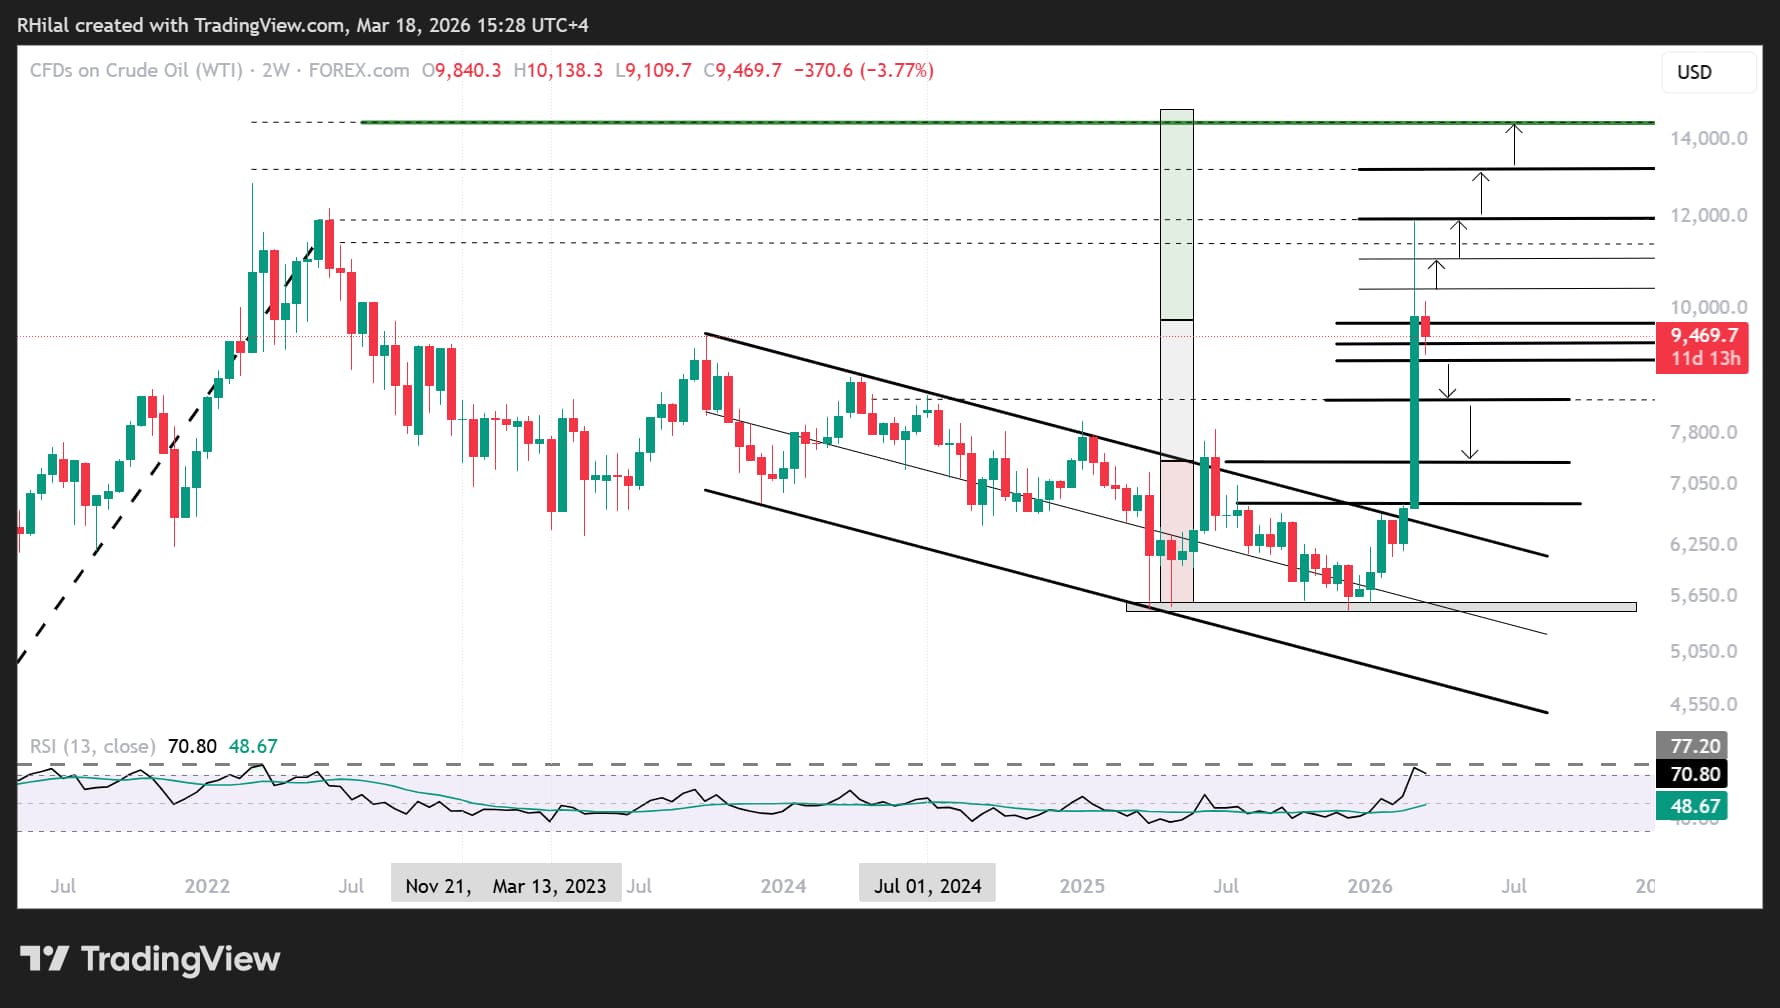
WTI Price Outlook: 2 Week Time Frame – Log Scale
Source: Trading view
In line with the Strait outlook and Brent price action, the WTI scenarios are as follows:
- Bullish scenario: a close above 98 extends upside risk toward 105, 110, 132, and 150 respectively.
- Short-term bearish scenario: the base case remains the stable range between 93 and 98. A close below 93 supports a short-term correction toward the 2023 highs near 90 and the 2024 highs near 84, before re-testing the June 2025 highs, with resistance aligning near the 75–73 range from the previous Middle East conflict.
- Long-term bearish scenario: a close below last year’s conflict highs, under 75 and 73, extends consolidation risks toward 67.
Written by Razan Hilal, CMT
Follow on X: @Rh_waves
Related tags:




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Nasdaq 100 Forecast: NDX rises ahead of Nvidia earnings
U.S. stocks are pointing to a mixed open, with Nasdaq futures inching higher as recently battered tech stocks steady ahead of Nvidia's earnings after the close and Anthropic's highly anticipated IPO tomorrow. Investors are also digesting slower retail sales growth, while Fed speakers will be watched closely.

Nasdaq 100 Forecast: NDX falls ahead of Nvidia’s earnings & Anthropic’s debut this week
U.S. stocks are heading for a weaker open amid a challenging macro backdrop and with AI-linked stocks once again under pressure ahead of Nvidia's results later this week. Attention is also turning to Anthropic's highly anticipated IPO.

Crude Oil Weekly Outlook: Geopolitics vs Oversupply Risks
Crude Oil Weekly Outlook: The IEA has flagged the risk of an oil supply surplus since the Iran war began. Yet WTI and Brent have held onto bullish rebounds from key support near 84 and 89, respectively, as geopolitical risks persist.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.