


DAX at Key Level; Alibaba Surges, Japan Tech Slumps
Markets opened September mixed. US inflation risks remain sticky, while weak consumer sentiment and PMI data weigh on the Fed outlook. Japan’s tech-heavy Nikkei dropped sharply on chip sector losses, while Alibaba surged in Hong Kong on new AI chip development. In Europe, inflation was mixed, with Germany seeing a slight rise. The DAX remains stuck below resistance, signaling fading bullish momentum unless bulls reclaim 24,300.
Share this:
1. Market Holidays
- USA: Markets closed for Labor Day.
- Canada: Markets also closed for Labor Day.
2. US Market Recap (Friday)
- Equities:
- US stocks closed lower.
- Nasdaq underperformed due to tech weakness.
- Sectors:
- Losses: Tech, Consumer Discretionary.
- Gains: Consumer Staples, Health Care.
- Data Highlights:
- PCE inflation came in line with expectations, but “supercore” measure rose for a third consecutive month → concerns about sticky inflation amid tariffs.
- Chicago PMI: Fell to 41.5 (vs. 47.1 prior), well below forecasts, signaling contraction.
- Trade deficit: Widened due to higher imports.
- University of Michigan Sentiment (final, Aug): Revised down to 58.2 (from 61.7), expectations component weakened.
- Inflation expectations: Revised lower.
- Market Impact:
- Fed expectations unchanged—focus remains on August jobs report (due Friday).
- Short-term Treasury yields and the US dollar eased after weak data.
3. Japan: Market & Economy
- Nikkei 225:
- Dropped 2%+ to a 3-week low, driven by heavy selling in chip-related stocks.
- Major contributors:
- Advantest (chip-testing/Nvidia supplier) plunged 9%, dragging 280 points off the Nikkei.
- SoftBank Group fell 6%, alongside losses in Disco, Socionext, Furukawa Electric.
- Topix Index: Fell only 0.8%, showing the sell-off was concentrated in tech.
- Economic Data:
- Industrial production (July): -1.6% MoM (worse than expected).
- Auto sector: -6.7%, hurt by new US tariffs.
- Retail sales: -1.6%, missing forecasts.
- Inflation (Tokyo, Aug): Slowed to 2.6%, largely due to energy subsidies. Core inflation (ex-food & energy) held at 3.0%.
- BoJ Outlook: Governor Ueda sees scope for further rate hikes as wages rise and labor market stays tight.
- Sectoral Trends:
- Export industries pressured by tariffs.
- Domestic demand: Supported by higher wages, benefiting services and banks.
4. China & Alibaba
- Alibaba Stock Surge:
- Shares jumped ~19% in Hong Kong on cloud and semiconductor optimism.
- New Chip Development:
- Alibaba unveiled a new AI chip, more advanced than prior models, aiming to reduce reliance on US semiconductors restricted by export bans.
- Limitations: Designed for running AI applications, not training large AI models (where Nvidia remains dominant).
- Competitive Context: Raises competitive concerns for Nvidia, while highlighting China’s drive for AI self-sufficiency.
5. Europe & Inflation
- Germany (Aug CPI):
- Rose to 2.2% YoY (vs. 2.0% prior months).
- Food prices: +2.5%.
- Energy prices: -2.7%.
- Core inflation: Steady at 2.7% for the third month.
- Services: +3.1%.
- Other Countries:
- France: Inflation eased slightly.
- Italy & Spain: Unchanged from prior month.
- Eurozone Outlook:
- Analysts expect August inflation to rise modestly to 2.1%.
- ECB likely to remain cautious; markets price only ~35% chance of another cut by year-end.
6. DAX Technical Analysis 4 hours
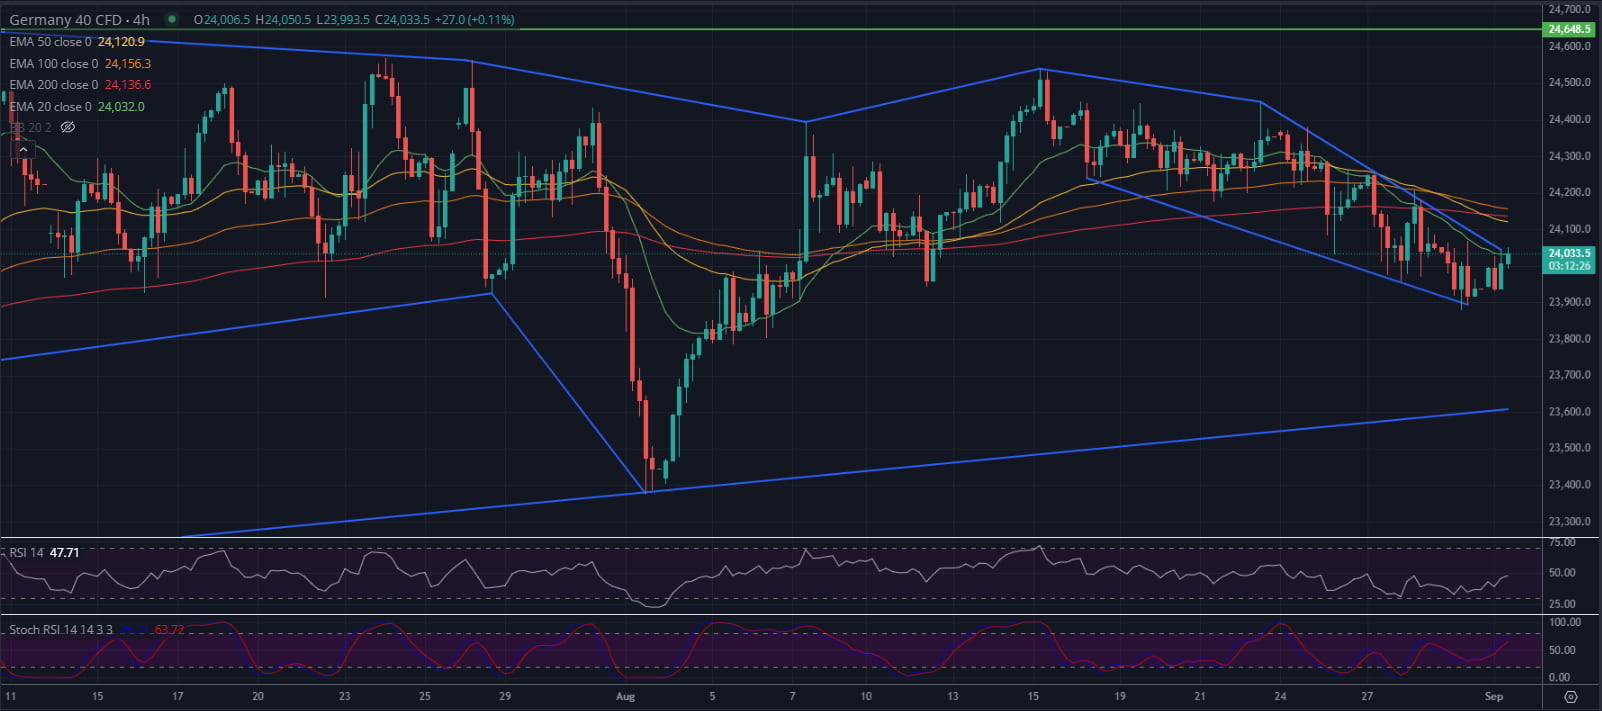
The Germany 40 (DAX) index remains within a broad ascending channel, but price action has grown increasingly compressed. A series of lower highs and sideways consolidation beneath the 50/100/200 EMAs points to fading bullish momentum. Price has also formed a clear descending structure within the larger uptrend, and while the recent bounce off channel support near 23,600 provided temporary relief, it’s now stalling again near 24,150–24,200 resistance. The RSI remains below 50, and the Stochastic RSI has just curled from overbought, suggesting upside may be limited in the immediate term.
For now, the bias is neutral-to-bearish in the short term, unless bulls can regain the 24,300–24,450 area. A break above this would expose the 24,648 highs, while failure to do so and a breakdown below 23,900 would likely open the door for another leg down toward 23,500 or even 23,200. With moving averages flattening out and price chopping within a narrowing structure, patience is warranted — but bulls need to act quickly to avoid further deterioration.
7. Key Takeaways
- US: Sticky inflation risks but weak business activity & consumer sentiment. Fed focus remains on jobs data.
- Japan: Tech stocks slump and weak industrial data raise concerns, though wages and services offset some drag.
- China: Alibaba signals ambition to fill the AI hardware gap left by Nvidia amid export controls.
- Europe: Inflation picture mixed; ECB still cautious, with limited scope for further easing.
- Global Markets: Tech sector remains the dominant driver of volatility at the start of September.
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

Gold under the pump as dollar sensitivity surges
Gold's sensitivity to the US dollar is approaching historical extremes, while its reaction to the latest Treasury yield shock ranks among the most severe in decades.

USD/JPY, DAX Forecast: Two trades to watch
Will USD/JPY break out of its 2-month range? DAX nears record highs as oil prices fall to 2-month lows.

US Dollar Bears Lose Their Grip Ahead of NFP, USD/JPY Vols Elevated
US dollar selling pressure fades ahead of NFP as Fed hike bets retreat. USD/JPY stands out with a 141-pip implied move as FX volatility takes centre stage.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.