



DAX forecast: German equities close in on record territory
European equities pushed higher this morning, joining the global rally. Investors are balancing ongoing geopolitical uncertainty in the Middle East against the relentless strength of the global technology sector. While European benchmarks have lagged behind Wall Street’s technology-led advance for much of the year, it appears like other areas of the market are catching up a little as risk appetite returns.
Share this:
European equities pushed higher this morning, joining the global rally. Investors are balancing ongoing geopolitical uncertainty in the Middle East against the relentless strength of the global technology sector. While European benchmarks have lagged behind Wall Street’s technology-led advance for much of the year, it appears like other areas of the market are catching up a little as risk appetite returns. We maintain a bullish DAX forecast, barring a major escalation in the US-Iran tensions.
DAX could be heading to new highs
The technology rally remains the dominant force across global markets. The Nasdaq 100 continues to register fresh record highs, while major Asian benchmarks in Japan and South Korea have also climbed to historic levels in recent weeks. European markets are now beginning to participate more fully in the broader equity advance, with the DAX once again approaching record territory.
A key factor supporting sentiment has been the recent decline in oil prices. Investors appear increasingly confident that, despite recent setbacks, Washington and Tehran will eventually find a diplomatic path forward. While negotiations remain unpredictable, the market is placing greater weight on the prospect of a future agreement than on the latest setbacks in talks.
Inflation concerns fail to derail equity momentum
The retreat in crude prices has helped soothe concerns that geopolitical tensions could trigger another inflation shock. Even as conflict in the Middle East has generated volatility across energy markets, investors have largely looked through the risks and maintained their focus on corporate earnings and economic resilience.
That confidence was tested slightly by the latest eurozone inflation figures. Core consumer prices rose by 2.5% year-on-year in May, marginally above expectations and up from 2.2% previously. Headline inflation matched forecasts at 3.2%.
With the next European Central Bank meeting approaching, the inflation data reinforces the case for policymakers to tighten their policy. The rise in price pressures reflects the earlier surge in energy costs stemming from US-Iran tensions.
Inflation in the euro area has now accelerated steadily from 2.6% in March to 3.0% in April and 3.2% in May, leaving it comfortably above the ECB’s 2% target. Given Europe’s heavy reliance on imported energy, the region remains particularly exposed to fluctuations in oil and gas markets.
Financial markets continue to anticipate a 25-basis-point interest rate increase from the ECB at its upcoming meeting, with investors viewing such a move as a precautionary step rather than the start of an aggressive tightening cycle.
Technology optimism continues to dominate
Despite geopolitical headlines and concerns over monetary policy, the investment narrative remains centred on artificial intelligence and the broader technology sector.
Investors continue to view AI-driven spending as one of the most powerful growth themes in global markets. Strong earnings from major technology companies have reinforced confidence that the current investment cycle still has room to run, even as valuations in parts of the sector remain stretched by historical standards.
For now, equity investors appear willing to overlook both geopolitical risks and valuation concerns. Whether that confidence ultimately proves justified will be one of the defining questions for markets over the second half of the year.
German equities are benefiting not only from improving global sentiment but also from domestic fiscal support. Germany’s substantial infrastructure and defence spending programme continues to provide a favourable backdrop for sectors such as industrials, construction and utilities, helping to offset otherwise subdued economic growth.
Technical DAX forecast: resistance levels coming into focus
From a technical perspective, the DAX forecast remains constructive. The index has demonstrated impressive resilience throughout the recent period of geopolitical uncertainty and has continued to build on its sequence of higher lows.
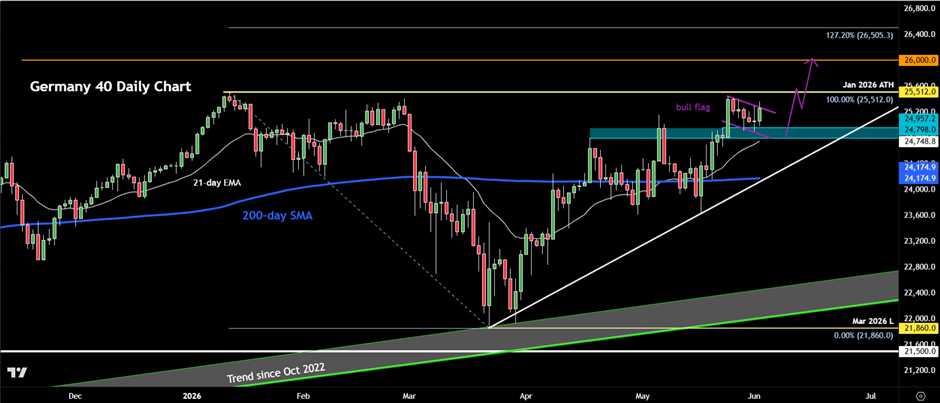
The recovery above the psychologically important 25,000 level reinforced the bullish structure and has encouraged further buying interest. As long as the index remains above this threshold, traders are likely to maintain a positive bias.
On the upside, the first area of resistance sits around 25,400, followed closely by the previous record high near 25,512. A decisive break above those levels would open the door towards the next major psychological milestone at 26,000.
Support remains concentrated around the 25,000 area, which now serves as an important pivot for the broader trend. Additional near-term support can be found around 25,180 and 25,100 should profit-taking emerge.
Looking ahead, the key question is whether investors continue to buy market dips as geopolitical tensions gradually ease and technology-led optimism remains intact. Unless a fresh escalation in the Middle East triggers a meaningful shift in sentiment, the path of least resistance for the DAX continues to point higher.

-- Written by Fawad Razaqzada, Market Analyst
Follow Fawad on Twitter @Trader_F_R


Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
US dollar rally loses yield support as Nvidia looms
US yields are retreating, but the dollar isn't following. With risk aversion potentially keeping it supported, Nvidia's results could determine whether emerging reversal signals in AUD/USD and EUR/USD develop further.

GBP/USD, GBP/JPY, GBP/AUD: Sterling Eyes UK Inflation Catalyst
Sterling faces a pivotal UK inflation test as traders weigh BoE tightening, Fed minutes and Australian employment data across GBP/USD, GBP/JPY and GBP/AUD.


EUR/USD outlook: euro back above 1.1000 as dollar rally loses steam
EUR/USD has recovered back above 1.1000 after a brief break lower, a sign the dollar's inflation-driven rally may be losing momentum. With a December Fed hike largely priced in and oil a potential tailwind for the euro, the risks are starting to tilt to the upside.
StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.