



Dow Jones at key juncture
<p>Today is the second last trading day of the week for stocks ahead of the Easter break, and there’s little further data to provide significant direction. The focus will be on the official weekly US oil inventories data later today. Stockpiles have been rising relentlessly despite signs of lower oil output in recent months. Last night, the American Petroleum Institute (API), an industry group, again reported a sharp build of 8.8 million barrels for the prior week. This was much higher than expected, although it didn’t cause a notable decline in oil prices. However, if confirmed by the official data from the Energy Information Administration (EIA) later this afternoon then this could pressurise oil prices, which in turn may have an impact on commodity stocks. But it should be noted that during this time of the year when refineries carry out their maintenance works ahead of the driving season, inventories do tend to rise. Thus, a bigger surprise would be if we see a drawdown, or even a small build. In this case, oil and possibly stocks could extend their recent gains. The other key US data to watch for the remainder of this week includes durable goods orders tomorrow and the final GDP estimate on Friday. From Europe, this week’s key remaining data includes the German Gfk Consumer Climate survey and the ECB’s Target LTRO results, both tomorrow. The start of next week will also be a slow one as far as the economic calendar is concerned, but things should pick up later on in the week with the monthly US jobs report scheduled for release on Friday April 1.</p>
Share this:

Today is the second last trading day of the week for stocks ahead of the Easter break, and there’s little further data to provide significant direction. The focus will be on the official weekly US oil inventories data later today. Stockpiles have been rising relentlessly despite signs of lower oil output in recent months. Last night, the American Petroleum Institute (API), an industry group, again reported a sharp build of 8.8 million barrels for the prior week. This was much higher than expected, although it didn’t cause a notable decline in oil prices. However, if confirmed by the official data from the Energy Information Administration (EIA) later this afternoon then this could pressurise oil prices, which in turn may have an impact on commodity stocks. But it should be noted that during this time of the year when refineries carry out their maintenance works ahead of the driving season, inventories do tend to rise. Thus, a bigger surprise would be if we see a drawdown, or even a small build. In this case, oil and possibly stocks could extend their recent gains. The other key US data to watch for the remainder of this week includes durable goods orders tomorrow and the final GDP estimate on Friday. From Europe, this week’s key remaining data includes the German Gfk Consumer Climate survey and the ECB’s Target LTRO results, both tomorrow. The start of next week will also be a slow one as far as the economic calendar is concerned, but things should pick up later on in the week with the monthly US jobs report scheduled for release on Friday April 1.
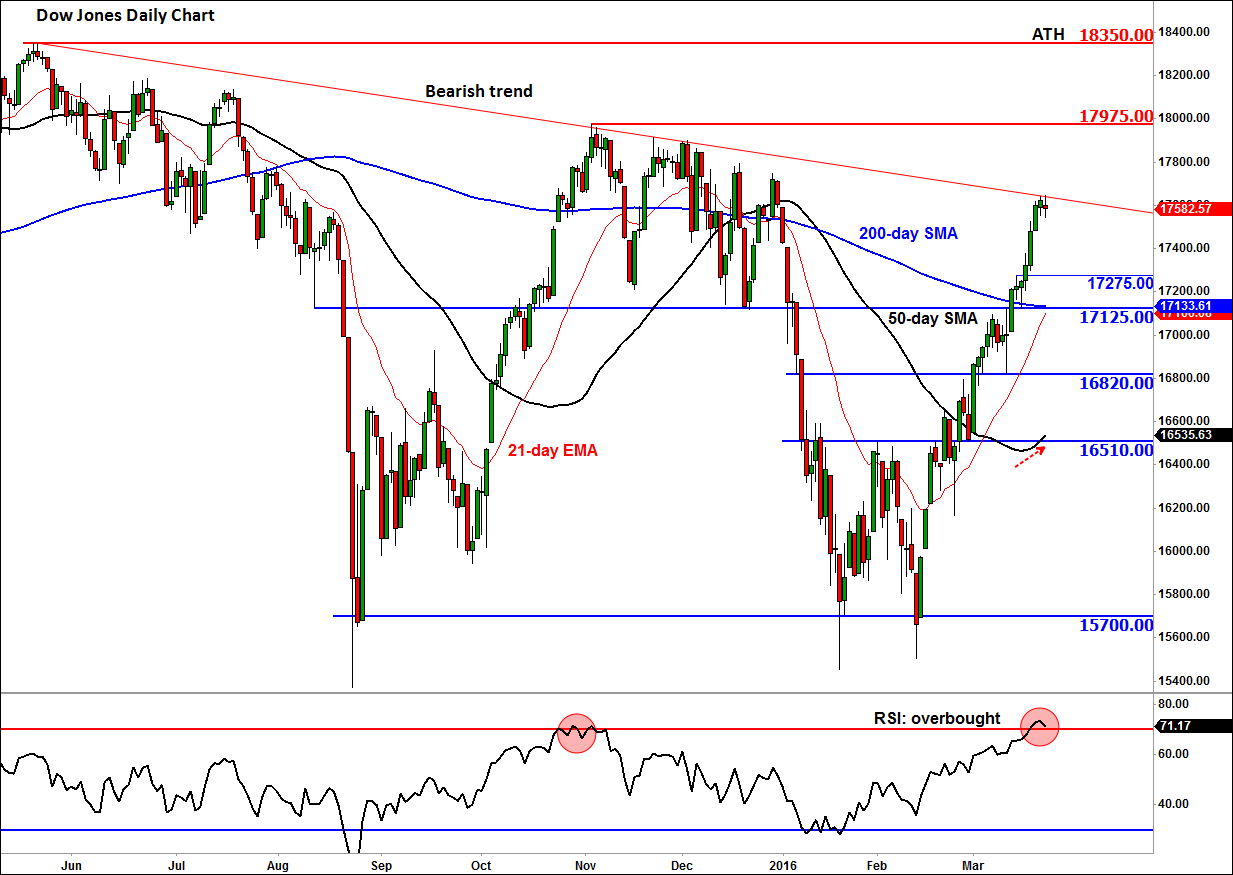
Because of the lack of significant data in the interim, technical analysis will garner more attention than usual, especially as the lower expected volumes over the coming days should make the markets more vulnerable to sharp moves and more headline-driven. On this front, the daily chart of the Dow Jones Industrial Average is an interesting to watch. It has been the best performing US index this year, undoubtedly due to the performance of the commodity stocks (as a result of rallying oil prices) that make up a large portion of this index. And overall the market conditions are favourable for the bulls, given the extremely low and negative interest rates as well as other nonconventional stimulus measures such as quantitative easing from some of the major central banks.
But a short-term pullback looks likely now that the Dow has reached a key level around the 17640/50 area, which corresponds with a bearish trend line off the previous record high, while the RSI momentum indicator has climbed above the "overbought" threshold of 70. So, there is potential for a pullback here, in part due to profit-taking from the longs. The sellers are only likely to show up in force if and when the index forms a reversal-looking candlestick pattern on the higher time frames such as the daily chart.
However, the bulls would argue that a pullback at this stage would actually be a positive outcome as it would allow the oscillators to work off ‘overbought’ conditions. The 50-day moving average is pointing higher and the 200 is flattening. So we could see a short-term pullback, potentially towards support levels at 17275 or 17125, before the rally resumes. Otherwise, a continuation of the rally towards the early November high at 17975 could be likely. The bulls may wish to proceed with extra caution over the next several days while the bears need to wait for some confirmation.
Related tags:
Latest market news




Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles
DXY, GBP/USD, AUD/USD, USD/CAD, USD/JPY, Gold Weekly Technical Outlook 11 16 2026
Sr. Technical Strategist Michael Boutros highlights the levels that matter on the USD Majors, commodities, and equity indices charts this week.

Crude Oil Weekly Outlook: Geopolitics vs Oversupply Risks
Crude Oil Weekly Outlook: The IEA has flagged the risk of an oil supply surplus since the Iran war began. Yet WTI and Brent have held onto bullish rebounds from key support near 84 and 89, respectively, as geopolitical risks persist.


Nikkei swings harder than Nasdaq as AI fears deepen
Nikkei 225 volatility is running well ahead of Nasdaq 100, with the index construction and Japan's heavy exposure to AI manufacturing potentially explaining the difference.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.