



Fed Recap Somewhat Dovish Hike Not Enough for Stocks
Heading into arguably the last major market event of 2018, traders felt they had a decent grasp on what the Federal Reserve would do.
Share this:

Heading into arguably the last major market event of 2018, traders felt they had a decent grasp on what the Federal Reserve would do.
Despite a wobble in financial markets and rising global concerns over the last few months, delaying the long-telegraphed interest rate increase would likely do more harm than good, as we noted in our numerous Fed preview reports. That said, with fears of a global economic slowdown in 2019 on the rise and the yield curve nearing inversion, traders expected a so-called “dovish hike,” with Powell and company emphasizing that future monetary policy decisions would be heavily data dependent, with the potential for a substantial pause in the rate hike cycle if the US economy turned south.
In other words, the market pretty much nailed it:
1) The Interest Rate Decision and Statement
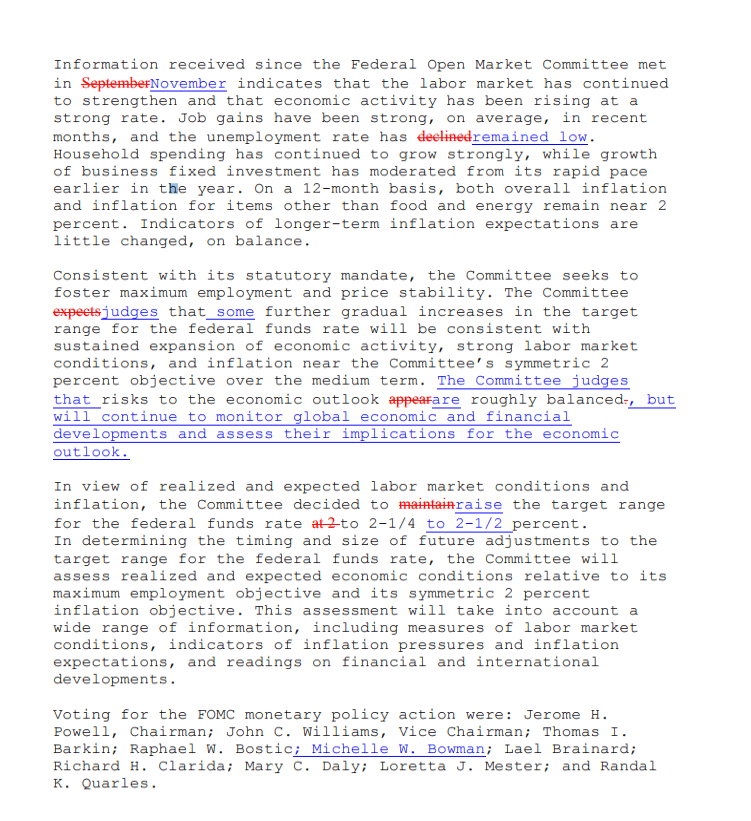
As widely expected, the Fed raised interest rates by 25bps to the 2.25-2.50% range, marking the 9th such interest rate increase since the Fed left zero interest rate policy (ZIRP) behind in December 2015. The decision to raise interest rates was unanimous (perhaps on-the-fence voters opted to show solidarity with Chairman Powell rather than be seen bending to political pressure?).
That said, the central bank did make some (slight) dovish tweaks to its monetary policy statement. Policymakers reiterated that the risks to the economic outlook were “roughly balanced,” but did add a clause about continuing to “monitor global economic and financial developments and assess[ing] their implications for the economic outlook.” The central bank also updated its forward outlook, noting that “some further gradual increases” in interest rates are expected. Many analysts expected Powell and Company to remove the “further gradual increases” wording entirely, so while this is a marginal dovish shift, it may be less dovish than traders were anticipating.
Source: FOREX.com
2) The Summary of Economic Projections
There were a couple of notable tweaks to the Fed’s quarterly economic forecasts. Most importantly, five of the potential Fed voters revised their 2019 interest rate forecasts lower, meaning that the median policymaker now expects just two rate hikes in 2019 (down from three at the September meeting). Now, the majority of Fed members (11/17) expect two or fewer interest rate increases next year.
On a macroeconomic front, the median Fed member’s forecast generally reflected a more cautious outlook for the economy in 2019:
- GDP Growth now expected at 2.3% (from 2.5% in September)
- Unemployment Rate expected at 3.5% (unchanged)
- Core PCE inflation now expected at 2.0% (from 2.1%)
Finally, the longer run so-called “neutral” Fed Funds rate estimate dropped from 3.0 to 2.8%, suggesting that the median Fed member thinks we’re within two rate increases of a neutral level.
3) Fed Chair Powell’s Press Conference
Jerome Powell is still taking questions as we go to press, but so far his comments have reinforced the slight dovish tone of the statement and economic projections. He’s emphasized international crosswinds, tame inflation, and market volatility as possible risks, but noted that recent developments have not fundamentally altered the central bank’s outlook.
Powell also noted that the central bank has now reached the bottom end of estimates of the neutral interest rate, meaning the Fed will be more data-dependent than ever moving forward. Finally, the Fed Chairman expressed no concerns with the central bank’s “balance sheet runoff” (Trump’s so-called “50 B’s”), suggesting that the Fed will continue to tighten policy through asset holding reductions.
Market Reaction
As I speculated on twitter this morning, today’s “dovish hike” was not quite as dovish as many traders were expecting. As a result, we’ve seen the US dollar index bounce back 50 pips to trade back in positive territory on the day, while the S&P 500 has dropped 3% off its intraday peak to its lowest level since last September. A close here would mark a significant break below support in the 2530 range, potentially opening the door for further downside heading into the typically low liquidity holiday period.



Open an account in minutes
Experience award-winning platforms with fast and secure execution.
Economic calendar
Web Trader platform
Our sophisticated web-based platform is packed with features.
Related articles

S&P, Nasdaq Slide as NVDA, AI Worries Continue to Build
It was a busy weekend in the headlines as a campaign to bring back Jensen Huang atop NVDA gained steam, even with accusations of possible treason and a circular funding model that has started to raise questions.


S&P 500, Nasdaq 100 Claw Back But NVDA Cloud Looms Overhead
Last week was green for both the Nasdaq and S&P 500 but given the sell-off that led into that bounce there’s still a very real question as to whether bears still have a statement to make. And the NVDA situation presents a very real threat.

S&P 500 forecast: SPX struggles for direction ahead of PPI data
U.S. stocks are struggling for direction on Friday as investors continue to weigh up the fallout from Nvidia’s leadership change, rising Treasury yields and the upcoming U.S. producer price inflation data.

StoneX Financial Ltd (trading as "FOREX.com") is an execution-only service provider. This material, whether or not it states any opinions, is for general information purposes only and it does not take into account your personal circumstances or objectives. This material has been prepared using the thoughts and opinions of the author and these may change. However, FOREX.com does not plan to provide further updates to any material once published and it is not under any obligation to keep this material up to date.
This material is short term in nature and may only relate to facts and circumstances existing at a specific time or day. Nothing in this material is (or should be considered to be) financial, investment, legal, tax or other advice and no reliance should be placed on it. No opinion given in this material constitutes a recommendation by FOREX.com or the author that any particular investment, security, transaction or investment strategy is suitable for any specific person.
The material has not been prepared in accordance with legal requirements designed to promote the independence of investment research. Although FOREX.com is not specifically prevented from dealing before providing this material, FOREX.com does not seek to take advantage of the material prior to its dissemination. This material is not intended for distribution to, or use by, any person in any country or jurisdiction where such distribution or use would be contrary to local law or regulation. For further details see our full non-independent research disclaimer and quarterly summary.